
Technology
Squarespace Announces Fourth Quarter and Full Year 2023 Financial Results and $500 Million Share Repurchase Authorization

Published
3 years agoon
By

Revenue Increased 18% in the Fourth Quarter and 17% for the Full Year 2023, Topping $1 Billion
Squarespace to Host Investor Day on May 15, 2024
NEW YORK, Feb. 28, 2024 /PRNewswire/ — Squarespace, Inc. (NYSE: SQSP), the design-driven platform helping entrepreneurs build brands and businesses online, today announced results for the fourth quarter and year ended December 31, 2023.
“Squarespace surpassed $1 billion in revenue for the first time in its 20-year history in 2023, driven by new customer growth across markets and strong retention, which speaks to our robust product offering,” said Anthony Casalena, Founder & CEO of Squarespace. “During 2023 we also made important strides in enhancing the foundation of our long-term growth through our acquisition of Google Domains, the launch of Squarespace Payments, and key product and feature introductions including new AI capabilities that expand our ecosystem and broaden accessibility to entrepreneurs wherever they are on their journey. Entering our third decade, we are in a strong position to capitalize across our core verticals of enabling small business, commerce and international expansion.”
“Squarespace delivered a record fourth quarter that exceeded our expectations across the board,” said Nathan Gooden, CFO of Squarespace. “We are combining increased scale and profitability with consistent execution and a relentless focus on innovation for entrepreneurs to set a strong foundation for sustainable growth and value creation. We view share repurchases as an integral part of our capital allocation strategy and the $500 million authorization announced today underscores the strong financial momentum in our business.”
Fourth Quarter 2023 Financial Highlights
Total revenue grew 18% year over year to $270.7 million in the fourth quarter, compared with $228.8 million in the fourth quarter of 2022, and 16% in constant currency.Presence revenue grew 20% year over year to $188.4 million and 18% in constant currency.Commerce revenue grew 14% year over year to $82.3 million and 13% in constant currency.Net income totaled $5.3 million, compared with a net loss of $234.0 million in the fourth quarter 2022. The 2022 result included a $225.2 million non-cash goodwill impairment charge. Excluding the impairment charge, net loss for the fourth quarter of 2022 was $8.8 million.Earnings per share totaled $0.04 based on 136,153,002 basic and 139,387,350 dilutive weighted average shares in the fourth quarter, compared with a loss per share of $1.72 based on 136,340,283 basic and dilutive weighted average shares in the fourth quarter of 2022.Cash flow from operating activities increased 56% to $61.1 million for the three months ended December 31, 2023, compared with $39.1 million for the three months ended December 31, 2022.Total bookings grew 23% year over year to $286.1 million in the fourth quarter, compared to $232.1 million in the fourth quarter of 2022.Unlevered free cash flow increased 57% to $65.0 million representing 24% of total revenue for the three months ended December 31, 2023, compared with $41.5 million for the three months ended December 31, 2022.Adjusted EBITDA increased to $64.7 million in the fourth quarter, compared with $63.1 million in the fourth quarter of 2022.
Full Year 2023 Financial Highlights
Total revenue grew 17% year over year to $1,012.3 million in 2023, compared with $867.0 million in 2022, and 16% in constant currency.Presence revenue grew 18% year over year to $704.3 million and 17% in constant currency.Commerce revenue grew 14% year over year to $308.0 million and 14% in constant currency.Net loss was $7.1 million, compared with a net loss of $252.2 million in 2022. The 2022 result included a $225.2 million non-cash goodwill impairment charge. Excluding the impairment charge, net loss for the full year 2022 was $27.1 million.Loss per share of $0.05 based on 135,531,363 basic and dilutive weighted average shares in 2023, compared with a loss per share of $1.82 based on 138,409,491 basic and dilutive weighted average shares in 2022.Cash flow from operating activities increased 41% to $231.1 million in 2023, compared with $164.2 million in 2022.Total bookings grew 19% year over year to $1,075.1 million in 2023, compared to $906.1 million in 2022.Unlevered free cash flow increased 46% to $241.0 million representing 24% of total revenue in 2023, compared with $165.6 million in 2022.Adjusted EBITDA increased to $235.4 million in 2023, compared with $147.5 million in 2022.Cash and cash equivalents at year-end 2023 of $257.7 million; total debt was $568.8 million, of which $49.0 million is current, debt net of cash and investments totaled $311.1 million.Total unique subscriptions increased 10% year over year to over 4.6 million in 2023, compared to 4.2 million in 2022.Average revenue per unique subscription (“ARPUS”) increased 9% year over year to $228.02 in 2023, compared to $209.16 in 2022.Annual run rate revenue (“ARRR”) grew 19% year over year to $1,105.7 million in 2023, compared to $931.7 million in 2022.
A reconciliation of GAAP to non-GAAP financial measures has been provided in the tables included in this press release. An explanation of these measures is also included below under the heading “Non-GAAP Financial Measures.”
2023 Business Highlights
Product Innovation
Squarespace provides superior design and ease of use technology for entrepreneurs everywhere. Our passion for innovation drove all areas of our business. In 2023, the Company:
Relaunched Squarespace Domains with a more complete domain management experience for domain-first customers following our acquisition of Google Domains Assets.Launched Squarespace Payments, which fully integrates with our customers’ online stores to accept fast and secure payments and provides a seamless purchase experience for their customers all in one place.Unveiled Squarespace Blueprint, our guided website design system that provides professionally-curated layouts and styling options.Advanced Acuity Scheduling’s platform technologies and introduced new branding to help streamline the client booking experience with a centralized dashboard, mobile app tools, and payment features.Invested in Squarespace AI to make it easier than ever for users to generate custom content. Generative AI integrations help populate websites, email campaigns, and commerce store descriptions, enabling customers to efficiently publish and specialize content for their brand identity.Released our annual compilation of new products and features, Squarespace Refresh, where we showcased new tools spanning commerce, client invoicing, courses, email marketing, enterprise customer collaboration, and more.Enhanced Tock’s User System with a new iOS app and new reservation features, and integrated Reserve with Google to help Tock customers increase their visibility and drive diners to their businesses.Established a partnership with SoundCloud to bring SoundCloud Next Pro artists the opportunity to create a beautiful website with unique, music-themed domains.
Marketing & Brand
Our marketing investments, design-centric ethos, and go-to-market channels bolster our brand recognition and keep Squarespace top of mind for new audiences. This year, Squarespace:
Continued to globalize our product suite by increasing our currency options by 5x.Introduced the second edition of Squarespace Collection (formerly Squarespace Icons) with Magnum Photos, where we partnered with six world renowned photographers to create signature website designs inspired by each photographer’s creativity and built on our website editor, Fluid Engine™.Teamed up with Adam Driver for our 9th Big Game campaign, “The Singularity,” where we honored Squarespace’s founding history as a pioneer in website building.Hosted our second Circle Day where we engaged thousands of members of our Circle partner program from around the world. Members shared advice and strategies on how to leverage strengths, skills, and connections to expand every web designer’s professional toolkit.Received multiple Fast Company awards, including Fast Company’s Most Innovative Companies and Innovation by Design, won two Webby Awards and our Big Game commercial won top honors from ADC, AICP, Cannes Lions, Ciclope, D&AD and the One Show.
Corporate
Squarespace is focused on creating and delivering value to entrepreneurs, partners, and investors. In 2023, the Company:
Acquired Google’s Domains business, representing millions of domains, and established an exclusive reseller agreement for any customer purchasing a domain along with their Google Workspace subscription from Google directly.Won multiple awards recognizing the excellence of our organization including Comparably’s Best Places to Work in New York.Celebrated our 20th anniversary; across two decades the Squarespace platform has been used by millions to build beautiful brands and businesses online.Returned approximately $26.0 million to shareholders under our share repurchase program as of December 31, 2023, which represents approximately 1.3 million shares.
Share Repurchase Program
Squarespace’s board of directors authorized a general share repurchase program of the Company’s Class A common stock of up to $500 million with no fixed expiration. These Class A common stock repurchases may occur in the open market, through privately negotiated transactions, through block purchases, other purchase techniques including the establishment of one or more plans under Rule 10b5-1 of the Securities Exchange Act of 1934 or by any combination of such methods. The timing and actual amount of shares repurchased will depend on a variety of different factors and may be modified, suspended or terminated at any time at the discretion of the board of directors.
Outlook & Guidance
For the first quarter of fiscal year 2024, Squarespace currently expects:
Revenue of $274 million to $277 million, or year-over-year growth of 16% to 17%.Non-GAAP unlevered free cash flow of $83 million to $86 million. This is the result of:Cash flow from operating activities of $77 million to $81 million, minusCapital expenditures, expected to be approximately $2 million to $3 million; plusCash paid for interest expense net of associated tax benefit, expected to be approximately $8 million.
For the full fiscal year 2024, Squarespace currently expects:
Revenue of $1,170 million to $1,190 million, or year-over-year growth of 16% to 18%, which includes contributions in the range of $85 million to $88 million related to our acquisition of Google Domains Assets.Non-GAAP unlevered free cash flow of $290 million to $310 million. This is the result of:Cash flow from operating activities of $266 million to $288 million, minusCapital expenditures, expected in the range of $4 million to $6 million; plusCash paid for interest expense net of associated tax benefit, expected to be approximately $28 million.
Webcast Conference Call & Shareholder Letter Information
Squarespace will host a conference call on February 28, 2024 at 8:30 a.m. ET to discuss its financial results. A live webcast of the event will be available in the Events & Presentations section of the Squarespace Investor Relations website. An archived replay of the webcast will be available following the conclusion of the call. Additionally, we invite you to read our shareholder letter available on our Investor Relations website.
Squarespace to Host Investor Day
Squarespace will host an Investor Day on May 15, 2024 in New York City. A live webcast of the event will be available in the Events & Presentations section of the Squarespace Investor Relations website. Interested investors and analysts are encouraged to email investors@squarespace.com for an invitation.
Non-GAAP Financial Measures
Revenue growth in constant currency is being provided to increase transparency and align our disclosures with companies in our industry that receive material revenues from international sources. Revenue constant currency has been adjusted to exclude the effect of year-over-year changes in foreign currency exchange rate fluctuations. We believe providing this information better enables investors to understand our operating performance irrespective of currency fluctuations.
We calculate constant currency information by translating current period results from entities with foreign functional currencies using the comparable foreign currency exchange rates from the prior fiscal year. To calculate the effect of foreign currency translation, we apply the same weighted monthly average exchange rate as the comparative period. Our definition of constant currency may differ from other companies reporting similarly named measures, and these constant currency performance measures should be viewed in addition to, and not as a substitute for, our operating performance measures calculated in accordance with GAAP.
Adjusted EBITDA is a supplemental performance measure that our management uses to assess our operating performance. We calculate adjusted EBITDA as net income/(loss) excluding interest expense, other income/(loss), net (provision for)/benefit from income taxes, depreciation and amortization, stock-based compensation expense and other items that we do not consider indicative of our ongoing operating performance.
Unlevered free cash flow is a supplemental liquidity measure that Squarespace’s management uses to evaluate its core operating business and its ability to meet its current and future financing and investing needs. Unlevered free cash flow is defined as cash flow from operating activities, including one-time expenses related to Squarespace’s direct listing, less cash paid for capital expenditures increased by cash paid for interest expense net of the associated tax benefit.
Adjusted EBITDA, unlevered free cash flow and revenue constant currency are not prepared in accordance with generally accepted accounting principles in the United States of America (“GAAP”) and have important limitations as an analytical tool. Non-GAAP financial measures are supplemental, should only be used in conjunction with results presented in accordance with GAAP and should not be considered in isolation or as a substitute for such GAAP results.
Further information on these non-GAAP items and reconciliation to their closest GAAP measure is provided below under, “Reconciliation of Non-GAAP Financial Measures.”
Definitions of Key Operating Metrics
On September 7, 2023, we closed an asset purchase agreement between us and Google LLC (“Google”) to acquire, among other things, Google’s domain assets (the “Google Domains Asset Acquisition “). Unique subscriptions and average revenue per unique subscription do not account for single domain subscriptions originally sold by Google as a part of the Google Domains Asset Acquisition (the “Acquired Domain Assets”).
Annual run rate revenue (“ARRR”). We calculate ARRR as the monthly revenue from subscription fees and revenue generated in conjunction with associated fees (fees taken or assessed in conjunction with commerce transactions) in the last month of the period multiplied by 12. We believe that ARRR is a key indicator of our future revenue potential. However, ARRR should be viewed independently of revenue, and does not represent our GAAP revenue on an annualized basis, as it is an operating metric that can be impacted by subscription start and end dates and renewal rates. ARRR is not intended to be a replacement or forecast of revenue.
Unique subscriptions represent the number of unique sites, standalone scheduling subscriptions, Unfold (social) and hospitality subscriptions, as of the end of a period. A unique site represents a single subscription and/or group of related subscriptions, including a website subscription and/or a domain subscription, and other subscriptions related to a single website or domain. Every unique site contains at least one domain subscription or one website subscription. For instance, an active website subscription, a custom domain subscription and a Google Workspace subscription that represent services for a single website would count as one unique site, as all of these subscriptions work together and are in service of a single entity’s online presence. Unique subscriptions do not account for one-time purchases in Unfold or for hospitality services nor do they account for our Acquired Domain Assets. The total number of unique subscriptions is a key indicator of the scale of our business and is a critical factor in our ability to increase our revenue base.
Average revenue per unique subscription (“ARPUS”). We calculate ARPUS as the total revenue during the preceding 12-month period divided by the average of the number of total unique subscriptions at the beginning and end of the period. ARPUS does not account for Acquired Domain Assets or the revenue from Acquired Domain Assets. We believe ARPUS is a useful metric in evaluating our ability to sell higher-value plans and add-on subscriptions.
Total bookings represents cash receipts for all subscriptions purchased, as well as payments due under the terms of contractual agreements for obligations to be fulfilled.
Gross merchandise value (“GMV”) represents the value of physical goods, content and time sold, including hospitality services, net of refunds, on our platform over a given period of time.
Forward-Looking Statements
This press release contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. All statements other than statements of historical fact are forward-looking statements. These statements include, but are not limited to, statements regarding Squarespace’s future operating results and financial position, including for its first fiscal quarter ending March 31, 2024 and its fiscal year ending December 31, 2024. The words “believe,” “may,” “will,” “estimate,” “potential,” “continue,” “anticipate,” “intend,” “expect,” “could,” “would,” “project,” “plan,” “target,” and similar expressions are intended to identify forward-looking statements. Forward-looking statements are based on management’s expectations, assumptions, and projections based on information available at the time the statements were made. These forward-looking statements are subject to a number of risks, uncertainties, and assumptions, including risks and uncertainties related to: Squarespace’s ability to attract and retain customers and expand their use of its platform; Squarespace’s ability to anticipate market needs and develop new solutions to meet those needs; Squarespace’s ability to improve and enhance the functionality, performance, reliability, design, security and scalability of its existing solutions; Squarespace’s ability to compete successfully in its industry against current and future competitors; Squarespace’s ability to manage growth and maintain demand for its solutions; Squarespace’s ability to protect and promote its brand; Squarespace’s ability to generate new customers through its marketing and selling activities; Squarespace’s ability to successfully identify, manage and integrate any existing and potential acquisitions or achieve the expected benefits of such acquisitions; Squarespace’s ability to hire, integrate and retain highly skilled personnel; Squarespace’s ability to adapt to and comply with existing and emerging regulatory developments, technological changes and cybersecurity needs; Squarespace’s compliance with privacy and data protection laws and regulations as well as contractual privacy and data protection obligations; Squarespace’s ability to establish and maintain intellectual property rights; Squarespace’s ability to manage expansion into international markets; and the expected timing, amount, and effect of Squarespace’s share repurchases. It is not possible for Squarespace’s management to predict all risks, nor can it assess the impact of all factors on its business or the extent to which any factor, or combination of factors, may cause actual results to differ materially from those contained in any forward-looking statements Squarespace may make. In light of these risks, uncertainties, and assumptions, Squarespace’s actual results could differ materially and adversely from those anticipated or implied in the forward-looking statements. Further information on risks that could cause actual results to differ materially from forecasted results are included in Squarespace’s filings with the Securities and Exchange Commission. Except as required by law, Squarespace assumes no obligation to update these forward-looking statements, or to update the reasons if actual results differ materially from those anticipated in the forward-looking statements.
About Squarespace
Squarespace (NYSE: SQSP) is a design-driven platform helping entrepreneurs build brands and businesses online. We empower millions in more than 200 countries and territories with all the tools they need to create an online presence, build an audience, monetize, and scale their business. Our suite of products range from websites, domains, ecommerce, and marketing tools, as well as tools for scheduling with Acuity, creating and managing social media presence with Bio Sites and Unfold, and hospitality business management via Tock. For more information, visit www.squarespace.com.
Contacts
Investors
investors@squarespace.com
CONSOLIDATED STATEMENTS OF OPERATIONS
(in thousands, except share and per share data)
(unaudited)
Three Months Ended December 31,
Years Ended December 31,
2023
2022
2023
2022
Revenue
$ 270,718
$ 228,812
$ 1,012,336
$ 866,972
Cost of revenue(1)
69,650
40,106
207,520
152,655
Gross profit
201,068
188,706
804,816
714,317
Operating expenses:
Research and product development(1)
61,715
56,828
242,188
227,297
Marketing and sales(1)
91,513
66,154
349,574
322,051
General and administrative(1)
29,922
37,942
129,326
151,620
Impairment charge
—
225,163
—
225,163
Total operating expenses
183,150
386,087
721,088
926,131
Operating income/(loss)
17,918
(197,381)
83,728
(211,814)
Interest expense
(10,718)
(7,230)
(36,768)
(18,207)
Other (loss)/income, net
(4,163)
(9,567)
3,362
5,030
Income/(loss) before benefit from/(provision for) income
taxes
3,037
(214,178)
50,322
(224,991)
Benefit from/(provision for) income taxes
2,219
(19,784)
(57,403)
(27,230)
Net income/(loss)
$ 5,256
$ (233,962)
$ (7,081)
$ (252,221)
Net income/(loss) per share, basic and dilutive
$ 0.04
$ (1.72)
$ (0.05)
$ (1.82)
Weighted-average shares used in computing net income/
(loss) per share, basic
136,153,002
136,340,283
135,531,363
138,409,491
Weighted-average shares used in computing net income/
(loss) per share, dilutive
139,387,350
136,340,283
135,531,363
138,409,491
(1) Includes stock-based compensation as follows:
Three Months Ended December 31,
Years Ended December 31,
2023
2022
2023
2022
Cost of revenue
$ 1,451
$ 944
$ 5,536
$ 3,414
Research and product development
13,868
11,099
54,806
42,237
Marketing and sales
2,921
2,450
10,856
8,696
General and administrative
9,587
12,989
36,551
48,186
Total stock-based compensation
$ 27,827
$ 27,482
$ 107,749
$ 102,533
CONSOLIDATED BALANCE SHEETS
(in thousands, except share and per share data)
(unaudited)
December 31, 2023
December 31, 2022
Assets
Current assets:
Cash and cash equivalents
$ 257,702
$ 197,037
Restricted cash
36,583
35,583
Investment in marketable securities
—
31,757
Accounts receivable
24,894
10,748
Due from vendors
6,089
4,442
Prepaid expenses and other current assets
48,947
48,326
Total current assets
374,215
327,893
Property and equipment, net
58,211
51,633
Operating lease right-of-use assets
77,764
86,824
Goodwill
210,438
210,438
Intangible assets, net
190,103
42,808
Other assets
11,028
10,921
Total assets
$ 921,759
$ 730,517
Liabilities, Redeemable Convertible Preferred Stock and Stockholders’ Deficit
Current liabilities:
Accounts payable
$ 12,863
$ 12,987
Accrued liabilities
99,435
64,360
Deferred revenue
333,191
269,689
Funds payable to customers
42,672
38,845
Debt, current portion
48,977
40,758
Operating lease liabilities, current portion
12,640
11,514
Total current liabilities
549,778
438,153
Deferred income taxes, non-current portion
1,039
788
Debt, non-current portion
519,816
473,167
Operating lease liabilities, non-current portion
97,714
110,169
Other liabilities
13,764
11,231
Total liabilities
1,182,111
1,033,508
Commitments and contingencies
Redeemable convertible preferred stock, par value of $0.0001; zero shares authorized as of December 31,
2023 and 2022, respectively; zero shares issued and outstanding as of December 31, 2023 and 2022,
respectively
—
—
Preferred stock, par value of $0.0001; 100,000,000 shares authorized as of December 31, 2023 and 2022,
respectively; zero shares issued and outstanding as of December 31, 2023 and 2022, respectively
—
—
Stockholders’ deficit:
Class A common stock, par value of $0.0001; 1,000,000,000 shares authorized as of December 31, 2023
and 2022, respectively; 88,545,012 and 87,754,534 shares issued and outstanding as of December 31, 2023
and 2022, respectively
9
8
Class B common stock, par value of $0.0001; 100,000,000 shares authorized as of December 31, 2023 and
2022, respectively; 47,844,755 shares issued and outstanding as of December 31, 2023 and 2022,
respectively
5
5
Class C common stock (authorized March 15, 2021), par value of $0.0001; zero shares authorized as of
December 31, 2023 and 2022, respectively; zero shares issued and outstanding as of December 31, 2023
and 2022, respectively
—
—
Class C common stock (authorized May 10, 2021), par value of $0.0001; 1,000,000,000 shares authorized
as of December 31, 2023 and 2022, respectively; zero shares issued and outstanding as of December 31,
2023 and 2022, respectively
—
—
Additional paid in capital
924,634
875,737
Accumulated other comprehensive loss
(843)
(1,665)
Accumulated deficit
(1,184,157)
(1,177,076)
Total stockholders’ deficit
(260,352)
(302,991)
Total liabilities, redeemable convertible preferred stock and stockholders’ deficit
$ 921,759
$ 730,517
CONSOLIDATED STATEMENTS OF CASH FLOWS
(in thousands)
(unaudited)
Years Ended December 31,
2023
2022
OPERATING ACTIVITIES:
Net loss
$ (7,081)
$ (252,221)
Adjustments to reconcile net loss to net cash provided by operating activities:
Depreciation and amortization
43,927
31,617
Stock-based compensation
107,749
102,533
Impairment charge
—
225,163
Deferred income taxes
251
788
Non-cash lease (income)/expense
(2,286)
2,227
Other
831
832
Changes in operating assets and liabilities:
Accounts receivable and due from vendors
(15,678)
(5,461)
Prepaid expenses and other current assets
(458)
3,699
Accounts payable and accrued liabilities
33,519
(2,215)
Deferred revenue
61,364
39,464
Funds payable to customers
3,827
8,707
Other operating assets and liabilities
5,152
9,086
Net cash provided by operating activities
231,117
164,219
INVESTING ACTIVITIES:
Proceeds from the sale and maturities of marketable securities
39,664
27,193
Purchases of marketable securities
(7,824)
(27,681)
Cash paid for acquisitions, net of acquired cash
(176,721)
—
Purchase of property and equipment
(16,998)
(11,543)
Net cash used in operating activities
(161,879)
(12,031)
FINANCING ACTIVITIES:
Borrowings on Term Loan
99,444
—
Payments of debt issuance costs
(637)
—
Principal payments on debt
(44,867)
(13,586)
Payments for repurchase and retirement of Class A common stock
(25,989)
(120,193)
Taxes paid related to net share settlement of equity awards
(36,366)
(21,268)
Proceeds from exercise of stock options
228
2,211
Net cash used in financing activities
(8,187)
(152,836)
Effect of exchange rate changes on cash, cash equivalents and restricted cash
614
(412)
Net increase/(decrease) in cash, cash equivalents and restricted cash
61,665
(1,060)
Cash, cash equivalents and restricted cash at the beginning of the period
232,620
233,680
Cash, cash equivalents and restricted cash at the end of the period
$ 294,285
$ 232,620
Reconciliation of cash, cash equivalents and restricted cash:
Cash and cash equivalents
$ 257,702
$ 197,037
Restricted cash
36,583
35,583
Cash, cash equivalents and restricted cash at the end of the period
$ 294,285
$ 232,620
SUPPLEMENTAL DISCLOSURE OF CASH FLOW
Cash paid during the year for interest
$ 35,668
$ 17,088
Cash paid during the year for income taxes, net of refunds
$ 41,747
$ 10,664
SUPPLEMENTAL DISCLOSURE OF NON-CASH INVESTING AND FINANCING ACTIVITIES
Purchases of property and equipment included in accounts payable and accrued liabilities
$ 129
$ 1,784
Accrued taxes related to net share settlement of equity awards
$ 377
$ 176
Non-cash leasehold improvements
$ —
$ (5,864)
Capitalized stock-based compensation
$ 3,940
$ 980
RECONCILIATIONS OF NON-GAAP FINANCIAL MEASURES
(in thousands)
(unaudited)
The following tables reconcile each non-GAAP financial measure to its most directly comparable GAAP financial
measure:
Three Months Ended December 31,
Years Ended December 31,
2023
2022
2023
2022
Net income/(loss)
$ 5,256
$ (233,962)
$ (7,081)
$ (252,221)
Interest expense
10,718
7,230
36,768
18,207
(Benefit from)/provision for income taxes
(2,219)
19,784
57,403
27,230
Depreciation and amortization
18,952
7,844
43,927
31,617
Stock-based compensation expense
27,827
27,482
107,749
102,533
Other loss/(income), net
4,163
9,567
(3,362)
(5,030)
Impairment charge
—
225,163
—
225,163
Adjusted EBITDA
$ 64,697
$ 63,108
$ 235,404
$ 147,499
Three Months Ended December 31,
Years Ended December 31,
2023
2022
2023
2022
Cash flows from operating activities
$ 61,090
$ 39,102
$ 231,117
$ 164,219
Cash paid for capital expenditures
(3,857)
(2,691)
(16,998)
(11,543)
Free cash flow
$ 57,233
$ 36,411
$ 214,119
$ 152,676
Cash paid for interest, net of the associated tax
benefit
7,788
5,105
26,894
12,874
Unlevered free cash flow
$ 65,021
$ 41,516
$ 241,013
$ 165,550
December 31, 2023
December 31, 2022
Total debt outstanding
$ 568,793
$ 513,925
Less: total cash and cash equivalents and marketable securities
257,702
228,794
Total net debt
$ 311,091
$ 285,131
Three Months Ended December 31,
Years Ended December 31,
2023
2022
2023
2022
Revenue, as reported
$ 270,718
$ 228,812
$ 1,012,336
$ 866,972
Revenue year-over-year growth rate, as reported
18.3 %
10.3 %
16.8 %
10.6 %
Effect of foreign currency translation ($)(1)
$ 4,664
$ (8,252)
$ 7,010
$ (28,318)
Effect of foreign currency translation (%)(1)
2.0 %
(4.0) %
0.8 %
(3.6) %
Revenue constant currency growth rate
16.3 %
14.3 %
16.0 %
14.2 %
Three Months Ended December 31,
Years Ended December 31,
2023
2022
2023
2022
Commerce revenue, as reported
$ 82,285
$ 71,983
$ 307,987
$ 269,672
Revenue year-over-year growth rate, as reported
14.3 %
12.1 %
14.2 %
17.5 %
Effect of foreign currency translation ($)(1)
$ 796
$ (1,451)
$ 1,204
$ (4,960)
Effect of foreign currency translation (%)(1)
1.1 %
(2.3) %
0.4 %
(2.2) %
Commerce constant currency growth rate
13.2 %
14.4 %
13.8 %
19.7 %
Three Months Ended December 31,
Years Ended December 31,
2023
2022
2023
2022
Presence revenue, as reported
$ 188,433
$ 156,829
$ 704,349
$ 597,300
Revenue year-over-year growth rate, as reported
20.2 %
9.5 %
17.9 %
7.7 %
Effect of foreign currency translation ($)(1)
$ 3,867
$ (6,801)
$ 5,806
$ (23,358)
Effect of foreign currency translation (%)(1)
2.5 %
(4.7) %
1.0 %
(4.2) %
Presence constant currency growth rate
17.7 %
14.2 %
16.9 %
11.9 %
(1) To calculate the effect of foreign currency translation, we apply the same weighted monthly average exchange
rate as the comparative period.
Amounts may not sum due to rounding.
SUMMARY OF SHARES OUTSTANDING
(unaudited)
Years Ended December 31,
2023
2022
Shares outstanding:
Class A common stock
88,545,012
87,754,534
Class B common stock
47,844,755
47,844,755
Class C common stock
0
0
Total shares outstanding
136,389,767
135,599,289
KEY PERFORMANCE INDICATORS AND NON-GAAP FINANCIAL MEASURES
(unaudited)
Three Months Ended December 31,
Years Ended December 31,
2023
2022
2023
2022
Unique subscriptions (in thousands)
4,631
4,204
4,631
4,204
Total bookings (in thousands)
$ 286,123
$ 232,145
$ 1,075,096
$ 906,056
ARRR (in thousands)
$ 1,105,743
$ 931,708
$ 1,105,743
$ 931,708
ARPUS
$ 228.02
$ 209.16
$ 228.02
$ 209.16
Adjusted EBITDA (in thousands)
$ 64,697
$ 63,108
$ 235,404
$ 147,499
Unlevered free cash flow (in thousands)
$ 65,021
$ 41,516
$ 241,013
$ 165,550
GMV (in thousands)
$ 1,654,126
$ 1,556,004
$ 6,211,823
$ 6,058,832
Unique subscriptions and average revenue per unique subscription (“ARPUS”) do not account for single domain
subscriptions originally sold by Google as a part of the Google Domains Asset Acquisition.
View original content to download multimedia:https://www.prnewswire.com/news-releases/squarespace-announces-fourth-quarter-and-full-year-2023-financial-results-and-500-million-share-repurchase-authorization-302073481.html
SOURCE Squarespace, Inc.

You may like
Technology
Axon Announces Body 5: Next-Generation Camera Built for the AI Era
Published
3 minutes agoon
October 24, 2026By
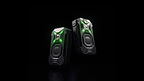
Axon Body 5 delivers 25x the AI processing power of earlier-generation cameras, with upgraded connectivity, audio and battery life to support real-time situational awareness in the field
SCOTTSDALE, Ariz., Oct. 24, 2026 /PRNewswire/ — Axon (Nasdaq: AXON), the global leader in public safety technology, today announced Axon Body 5, its newest body-worn camera designed to bring more powerful intelligence, connectivity and real-time support directly to officers in the field.
For years, Axon body cameras have helped agencies capture critical evidence and create greater transparency. Body 5 is built to help officers during the call, with information, assistance and backup on the spot.
“Officers shouldn’t have to choose between getting information and watching the scene. With Axon Body 5, they don’t,” said Rick Smith, Axon Founder and CEO. “They capture a license or document with the camera, keep their hands free and eyes up, and get information faster than writing it down and calling it in by radio. An officer fully engaged with the person in front of them, not down at a notepad, is a safer officer and a better-served community.”
Axon Body 5: Built for the AI Era
Built from the ground up for the AI era, Axon Body 5 delivers 25x the AI processing power than earlier generation Axon body cameras, alongside advancements in connectivity, audio, video and battery life. Together, these upgrades give the camera the physical power to run smarter AI features — both today and as new AI tools are developed in the future — while also making it more dependable for officers to use every day.
For the first time, Axon is also introducing two versions of its latest flagship camera: Axon Body 5 and Axon Body 5 Pro.
Both models feature several key advancements, including:
25x more processing power for AI: A powerful new computing architecture creates the capacity to support current and future AI features directly on the body camera.Enhanced video: Improved video captures clearer evidence across challenging environments, including better low-light performance.Improved connectivity: Seamless connectivity in urban and remote environments – and more precise location capability – helps officers, cameras and remote support teams stay connected when timely information matters most.Longer battery life: 20% more battery life than the previous generation helps keep the camera ready and connected throughout an officer’s shift.
The Axon Body 5 Pro will continue to gain new AI capabilities as they become available, growing along with the AI Era Plan. Additionally, new hardware features include:
A near-focus camera: An additional dedicated camera lens lets officers scan driver’s licenses to check status and search for wants or warrants in seconds, without returning to the patrol vehicle, with relevant information sent to Axon Fusus to support real-time operations.Front-facing speakers: Four additional speakers project even more powerful audio toward the person an officer is speaking with, helping real-time translations from Axon Assistant carry more clearly over heavy traffic or crowd noise. Additional memory: Extra space lets the camera run several AI tools at once, helping officers stay better informed and work faster.
Bringing More of Axon’s AI Era Into the Field
Axon Body 5 helps officers get more out of the Axon AI Era Plan by bringing smart tools right to the scene. Axon’s portfolio already supports public safety professionals across a growing range of tasks. For example, Draft One helps officers turn body-camera audio into high-quality report drafts and Axon Assistant provides voice-based information access and real-time translation.
Increasingly, Axon is also bringing AI into real-time operations.
Axon Guardian is a new category of AI features within the AI Era Plan that was specifically created to work with an officer’s field-based devices – starting with body cameras and in-car cameras – to improve safety. Guardian is designed to flag potential risks as situations unfold and create alerts when additional attention may be needed. Two of the first features include:
Escalation Detection: When an Axon Body 4 or Axon Body 5 camera is activated and recording, Guardian has the ability to detect potential conflicts in real time and create an alert in Axon Fusus. A human reviews the livestream and decides if additional support or action is needed.Approach Alert: When active on Axon Fleet 3, Guardian can detect if the door of a stopped vehicle opens and alert the officer through the in-car display and their body-worn camera.
Combined, Axon Body 5 and the expanding AI Era portfolio demonstrate the importance of AI as a critical resource to assist public safety professionals before, during and after an incident — reducing administrative burden, improving situational awareness and helping protect more lives.
Innovating Responsibly
Axon’s Responsible Innovation framework guides the development of all of its products. Designed with this in mind, Axon Body 5 and Guardian prioritize human oversight and maintain agency control over data. As a key part of the responsible innovation process, Axon’s independent Ethics and Equity Advisory Council was created to help responsibly develop and deploy new technologies with transparency, while aligning with community expectations.
General availability dates for Axon Body 5 and Axon Guardian will be announced soon. Product features and capabilities vary by configuration. For more information on Axon’s current products and services: Axon Product Catalog – Axon.com.
About Axon
Axon (Nasdaq: AXON) is the global leader in public safety technology supporting state, local, federal and international public safety agencies with technology designed to Protect Life. Complementing its mission, Axon’s growing Enterprise market focuses on protecting critical infrastructure and frontline workers across multiple industries including corporate security, hospitality, retail and healthcare. Founder-led since 1993, Axon builds products with transparency and responsibility. From TASER energy devices to today’s connected network of hardware – including cameras, drones, and robotics – cloud software, sensors, and AI-tools, the Axon ecosystem helps seamlessly protect people and places when it matters most. To ensure these technologies align with community expectations, Axon’s independent Ethics & Equity Advisory Council guides the ethical, inclusive, and accountable design of its products and services. Learn more about the EEAC and Axon’s Responsible Innovation framework at Axon Responsibility.
Non-Axon trademarks are the property of their respective owners. Axon, TASER and the Delta Logo are trademarks of Axon Enterprise, Inc., some of which are registered in the US and other countries. For more information, visit www.axon.com/legal. All rights reserved.
Please visit https://investor.axon.com and https://www.axon.com/newsroom for more information.
Media Contact:
Kate MacKinnon
Vice President, Communications
press@axon.com
View original content to download multimedia:https://www.prnewswire.com/news-releases/axon-announces-body-5-next-generation-camera-built-for-the-ai-era-302918553.html
SOURCE Axon
Technology
In HelloNation, Custom Fabrication Expert Mark Coyle Explains a Common Mistake in Custom Aluminum Design
Published
1 hour agoon
October 24, 2026By
The article explains why smart geometry, not thicker walls, creates stronger, more efficient aluminum components.
ROCHESTER, N.Y., Oct. 24, 2026 /PRNewswire/ — What early design choice causes many custom aluminum projects to become heavier, costlier, or harder to manufacture? That question is addressed in a HelloNation article featuring insights from Custom Fabrication Expert Mark Coyle of American Custom Metals, Inc. in Rochester, New York, that outlines how misunderstanding aluminum behavior leads designers to rely on thick walls instead of stronger geometry.
The article begins by explaining that many people assume thicker walls automatically make aluminum parts stronger. It notes that aluminum does not respond to wall thickness the way steel does. Instead, its performance is shaped by how the metal flows through the extrusion die. The article states that custom aluminum design is more effective when profiles use ribs, chambers, and flanges to create stiffness without adding unnecessary weight. This guidance helps readers understand why adding material often increases cost without improving strength.
The article also highlights that thicker walls change how aluminum moves during extrusion. When heavy areas fill more slowly, the metal cools unevenly and can develop stress that only appears later. The HelloNation piece explains that well-balanced geometry keeps extrusion smooth and predictable. This consistency makes it easier to maintain dimensional accuracy across long production runs. By focusing on geometry, custom aluminum design avoids the problems that come with slow extrusion speeds and uneven cooling.
Another insight in the article centers on how ribs and internal supports influence stability. It describes how a thin wall supported by a properly placed rib often performs better than a thick wall with no reinforcement. This happens because the rib helps distribute load, improve stiffness, and guide the aluminum as it cools. The article explains that this structural approach makes custom aluminum design more efficient and gives designers more control over how the final part behaves under pressure.
The article also shows why early collaboration between designer and fabricator prevents costly changes. It states that a fabricator familiar with extrusion can catch potential issues before a die is built. Small adjustments to corners or transitions can remove weak points or improve metal flow. The article notes that this teamwork keeps the design aligned with real-world production. By working together early, both sides reduce the risk of redesigning the die after the first test run.
Machining is another area where the article explains how wall thickness affects performance. Features such as deep pockets or sharp internal angles may require slow feed rates or special tooling. When walls are thicker than needed, those areas can become difficult to machine cleanly. The article states that thoughtful custom aluminum design makes machining more predictable. Small changes, such as adding radiused edges or sizing features to match standard tools, help shorten cycle times and prevent tool wear.
Thermal behavior receives detailed attention as well. The article explains that aluminum retains heat differently depending on the mass of each section. Thicker walls hold heat longer, which increases the chance of distortion during extrusion, machining, or finishing. When a design uses geometry to create strength, the material cools more evenly. This reduces warping and helps long profiles stay aligned. The article notes that stable cooling is important for components that require a precise fit and consistent shape throughout an entire production run.
Cost is also a key topic in the article. It states that heavier profiles increase material use, extrusion time, and tooling needs. A custom aluminum design that relies on geometry instead of mass lowers material consumption and keeps the fabrication process efficient. The article explains that lighter parts are easier to handle, ship, and assemble. This saves money across multiple stages of production and supports long-term manufacturing efficiency.
The article also notes that smart custom aluminum design creates profiles that behave predictably during extrusion and machining. Smooth transitions, balanced wall dimensions, and structural features help reduce the chance of distortion or dimensional drift. These elements also lower scrap rates and support reliable performance. By using geometry instead of excess material, designers build parts that maintain strength without compromising manufacturability.
As the article concludes, it emphasizes that avoiding thick walls is one of the best ways to improve performance and lower cost. It states that the most dependable custom aluminum components come from designs that use structural features to strengthen the profile. When designers understand how aluminum behaves at each stage of extrusion and machining, they create parts that are strong, efficient, and consistent from batch to batch. This approach turns custom aluminum design into a predictable process rather than a series of uncertain adjustments.
A Common Mistake in Custom Aluminum Design features insights from Mark Coyle, Custom Fabrication Expert of Rochester, NY, in HelloNation.
About HelloNation
HelloNation is America’s Good News Network, a premier media platform built on the idea that good news travels faster when real people tell real stories. Through its community-focused publications and innovative “edvertising” approach, HelloNation delivers content that informs, inspires, and spotlights the leaders making a meaningful impact in their communities.
View original content to download multimedia:https://www.prnewswire.com/news-releases/in-hellonation-custom-fabrication-expert-mark-coyle-explains-a-common-mistake-in-custom-aluminum-design-302918282.html
SOURCE HelloNation
Technology
World Young Scientist Summit 2026 Opens in Wenzhou, Zhejiang
Published
2 hours agoon
October 24, 2026By
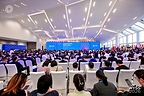
WENZHOU, China, Oct. 24, 2026 /PRNewswire/ — This is a report by China Daily:
On October 24, the World Young Scientist Summit 2026 opened in Wenzhou, Zhejiang. The event is hosted by the China Association for Science and Technology (CAST), the Zhejiang Provincial People’s Government, and the World Association of Young Scientists. Nearly 800 representatives, including scientists, educators, and entrepreneurs from more than 60 countries and regions, are attending the summit.
He Junke, Vice President of CAST in charge of daily work and First Secretary of its Secretariat; Lian Yimin, Chairman and Party Group Secretary of the Zhejiang Provincial Committee of the Chinese People’s Political Consultative Conference; Marcelo Knobel, Executive Director of The World Academy of Sciences; and Zhang Zhenfeng, Member of the Standing Committee of the CPC Zhejiang Provincial Committee and Secretary of the CPC Wenzhou Municipal Committee, attended the summit and delivered remarks. Yao Gaoyuan, Vice Governor of the Zhejiang Provincial People’s Government, presided over the first segment of the plenary session.
With the theme “Gathering Talents Worldwide to Create a Better Future,” the summit’s annual agenda is “Global Youth Action in the AI Era: Building a Sustainable Future.” It aims to draw on the insights of young people around the world, deepen international sci-tech cooperation, and jointly address questions about young people, science, the world and the future.
Efim Zelmanov, Fields Medalist and Foreign Member of the Chinese Academy of Sciences; Chen Yunji, Deputy Director of the Institute of Computing Technology, CAS, and Director of the National Key Laboratory of Processor Chips; Mary Garson, President of the International Union of Pure and Applied Chemistry; and Lu Chaoyang, Member of the Standing Committee of CAST, Executive Dean of the Shanghai Institute of Advanced Study, University of Science and Technology of China, and Chairman of the Council of the World Association of Young Scientists, delivered keynote speeches respectively on education reform in the AI era, AI and processor chips, young women scientists’ participation in science, and quantum computing. They explored new opportunities for scientific research, talent cultivation, and international cooperation in the AI era.
This year’s summit placed greater emphasis on the growth needs of young scientists, with young talents under the age of 45 accounting for 88 percent of participants. It aimed to build a cluster of international journals, bring together young scientific talent, facilitate a batch of international collaborative projects and advance the application and commercialization of scientific and technological achievements. The summit released the Report on the Distribution and Mobility of Young Scientists in the Field of Embodied Intelligence, launched the World Young Scientist Summit Partner Journal Program and the 2026 World Young Scientist Innovation and Entrepreneurship Growth Support Program. It also published the “Young Scientist Pioneers 2035” list and announced the 2026 Sustainable Development Young Scientist Award. The awards were presented to four Chinese and foreign scientists.
Chen Tianrun, Founder of Hangzhou Moxin Technology Co., Ltd.; Yuan Yang, Assistant to the Dean of the Institute for Interdisciplinary Information Sciences at Tsinghua University; and two of the 2026 Sustainable Development Young Scientist Award winners, César de la Fuente and Nicola Segata, among other Chinese and foreign young scientist representatives, spoke at the flash-talk session to share their research practices and reflections.
In addition, the conference focused on fields such as future manufacturing, quantum information, embodied intelligence, brain-computer intelligence, environmental science, deep-sea resources, and life and health, and held 12 parallel forums. It also included the “Gravitation π” Future Technology and Concept Products Exhibition and Exchange, local thematic side events, and sci-tech and humanities study visits, further building an interdisciplinary, cross-regional and cross-sector platform for youth sci-tech exchange and cooperation.
View original content to download multimedia:https://www.prnewswire.com/news-releases/world-young-scientist-summit-2026-opens-in-wenzhou-zhejiang-302918664.html
SOURCE China Daily


Axon Announces Body 5: Next-Generation Camera Built for the AI Era

In HelloNation, Custom Fabrication Expert Mark Coyle Explains a Common Mistake in Custom Aluminum Design

World Young Scientist Summit 2026 Opens in Wenzhou, Zhejiang

Send Rakhi to UK swiftly with UK Gifts Portal

Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

Nullmax and Renesas Forge Strategic Partnership to Deliver Competitive ADAS Solutions for the Global Market

Why You Should Build on #NEAR – Co-founder Illia Polosukhin at CV Labs
Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

NEAR End of Year Town Hall 2021: The Open Web World, MetaBUILD 2 Hackathon and 2021 recap
Trending
-
 Technology4 days ago
Sophont Launches Holon-S1 to Reveal Tumor Biology from Routine Pathology Slides
-
 Technology4 days ago
NC AI Officially Releases VARCO Sound, the Generative AI Sound Production Service
-
 Technology5 days ago
OppFi Announces its Third Quarter 2026 Earnings Conference Call
-
 Technology4 days ago
Trinity Acquires Verix, Adding AI-Powered Next-Best-Action and Omnichannel Orchestration to the TrinityEDGE Platform
-
 Coin Market4 days ago
Stablecoin transfers quadruple to $891B as US banks expand adoption: Report
-
 Technology4 days ago
Workato Launches Self-Serve Platform in Singapore, Opening Enterprise AI to a Broader Community of Builders
-
 Technology1 day ago
Miami Startup BOB Raises $5.5M To Build An AI-Powered Banking Platform
-
 Technology4 days ago
Findem Takes on Candidate Fraud With Authenticity Suite Pro