
Technology
Charter Announces Second Quarter 2024 Results

Published
2 years agoon
By
STAMFORD, Conn., July 26, 2024 /PRNewswire/ — Charter Communications, Inc. (along with its subsidiaries, the “Company” or “Charter”) today reported financial and operating results for the three and six months ended June 30, 2024.
Second quarter total residential and small and medium business (“SMB”) Internet customers decreased by 149,000. As of June 30, 2024, Charter served a total of 30.4 million residential and SMB Internet customers.Second quarter total residential and SMB mobile lines increased by 557,000. As of June 30, 2024, Charter served a total of 8.8 million mobile lines.As of June 30, 2024, Charter had a total of 31.8 million residential and SMB customer relationships, excluding mobile-only relationships.Second quarter revenue of $13.7 billion grew by 0.2% year-over-year, driven by residential mobile service revenue growth of 36.9% and residential Internet revenue growth of 1.3%.Net income attributable to Charter shareholders totaled $1.2 billion in the second quarter.Second quarter Adjusted EBITDA1 of $5.7 billion grew by 2.6% year-over-year.Second quarter capital expenditures totaled $2.9 billion and included $1.1 billion of line extensions.Second quarter net cash flows from operating activities totaled $3.9 billion, compared to $3.3 billion in the prior year.Second quarter free cash flow1 of $1.3 billion increased from $668 million in the prior year, primarily due to higher Adjusted EBITDA, a more favorable change in working capital and lower cash taxes due to timing.During the second quarter, Charter purchased 1.5 million shares of Charter Class A common stock and Charter Communications Holdings, LLC (“Charter Holdings”) common units for $404 million.
“We are executing well on several transformational initiatives, growing EBITDA through efficiencies, and improving our service and sales capabilities,” said Chris Winfrey, President and CEO of Charter. “We remain fully focused on driving customer growth, with a unique, high quality product set that continues to evolve, creating long term value for shareholders.”
1.
Adjusted EBITDA and free cash flow are non-GAAP measures defined in the “Use of Adjusted EBITDA and Free Cash Flow Information” section and are reconciled to net income attributable to Charter shareholders and net cash flows from operating activities, respectively, in the addendum of this news release.
Key Operating Results
Approximate as of
June 30, 2024 (c)
June 30, 2023 (c)
Y/Y Change
Footprint
Estimated Passings (d)
57,774
56,209
2.8 %
Customer Relationships (e)
Residential
29,615
30,009
(1.3) %
SMB
2,222
2,219
0.2 %
Total Customer Relationships
31,837
32,228
(1.2) %
Residential
(182)
13
(195)
SMB
3
4
(1)
Total Customer Relationships Quarterly Net Additions
(179)
17
(196)
Total Customer Relationship Penetration of Estimated Passings (f)
55.1 %
57.3 %
(2.2) ppts
Monthly Residential Revenue per Residential Customer (g)
$ 120.77
$ 120.25
0.4 %
Monthly SMB Revenue per SMB Customer (h)
$ 165.28
$ 164.56
0.4 %
Residential Customer Relationships Penetration
One Product Penetration (i)
47.7 %
46.0 %
1.7 ppts
Two Product Penetration (i)
33.2 %
33.0 %
0.2 ppts
Three or More Product Penetration (i)
19.2 %
20.9 %
(1.7) ppts
% Residential Non-Video Customer Relationships
57.1 %
53.1 %
4.0 ppts
Internet
Residential
28,318
28,549
(0.8) %
SMB
2,049
2,037
0.6 %
Total Internet Customers
30,367
30,586
(0.7) %
Residential
(154)
70
(224)
SMB
5
7
(2)
Total Internet Quarterly Net Additions
(149)
77
(226)
Video
Residential
12,718
14,071
(9.6) %
SMB
591
635
(6.9) %
Total Video Customers
13,309
14,706
(9.5) %
Residential
(393)
(189)
(204)
SMB
(15)
(11)
(4)
Total Video Quarterly Net Additions
(408)
(200)
(208)
Voice
Residential
6,170
7,248
(14.9) %
SMB
1,276
1,294
(1.4) %
Total Voice Customers
7,446
8,542
(12.8) %
Residential
(268)
(225)
(43)
SMB
(12)
4
(16)
Total Voice Quarterly Net Additions
(280)
(221)
(59)
Mobile Lines (j)
Residential
8,531
6,410
33.1 %
SMB
278
216
28.7 %
Total Mobile Lines
8,809
6,626
32.9 %
Residential
539
628
(89)
SMB
18
20
(2)
Total Mobile Lines Quarterly Net Additions
557
648
(91)
Enterprise (k)
Enterprise Primary Service Units (“PSUs”)
312
294
6.1 %
Enterprise Quarterly Net Additions
4
6
(2)
In thousands, except per customer and penetration data. See footnotes to unaudited summary of operating statistics on page 7 of the addendum of this news release. The footnotes contain important disclosures regarding the definitions used for these operating statistics. All percentages are calculated using whole numbers. Minor differences may exist due to rounding.
As of June 30, 2024, Charter had 29.6 million residential customer relationships, excluding mobile-only relationships.
Second quarter residential Internet customers decreased by 154,000, largely driven by the end of the FCC’s Affordable Connectivity Program (“ACP”) subsidies in the second quarter, compared to an increase of 70,000 during the second quarter of 2023. Spectrum Internet® delivers the fastest Internet speeds1 in the nation. Charter is evolving its connectivity network at a lower cost than its competitors to offer symmetrical and multi-gigabit Internet speeds across its entire footprint. Charter’s Advanced WiFi, a managed WiFi service that provides customers an optimized home network while providing greater control of connected devices with enhanced security and privacy is available to all Spectrum Internet customers.
Residential video customers decreased by 393,000 in the second quarter of 2024, compared to a decline of 189,000 in the second quarter of 2023. As of June 30, 2024, Charter had 12.7 million residential video customers.
During the second quarter of 2024, residential wireline voice customers declined by 268,000, compared to a decline of 225,000 in the second quarter of 2023. As of June 30, 2024, Charter had 6.2 million residential wireline voice customers.
During the second quarter of 2024, Charter added 539,000 residential mobile lines, compared to growth of 628,000 during the second quarter of 2023. Spectrum MobileTM is available to all new and existing Spectrum Internet customers and offers the fastest overall speeds,2 with plans that include 5G access, do not require contracts and include taxes and fees in the price. Spectrum Mobile is central to Charter’s converged network strategy to provide consumers a differentiated connectivity experience with highly competitive, simple data plans and pricing.
In April, Charter launched Anytime Upgrade, which is now included in the Spectrum Mobile Unlimited Plus data plan at no extra cost, and allows new and existing customers to upgrade their phones whenever they want, as many times as they want, eliminating the traditional wait times and condition requirements associated with phone upgrades. In May, Charter launched a phone balance buyout program, making it easier for customers to switch and save money. When a customer switches to Spectrum Mobile from another provider and purchases at least three lines with at least one ported line, Charter will pay off their existing phone balance on ported lines up to $2,500 while also enabling potential savings of hundreds of dollars annually on their mobile bills.
Second quarter 2024 monthly residential revenue per residential customer totaled $120.77, and increased by 0.4% compared to the prior year period, given promotional rate step-ups, rate adjustments and the growth of Spectrum Mobile, partly offset by a lower mix of video customer relationships, a higher mix of lower priced video packages within Charter’s video customer base and retention offers extended to customers that previously received an ACP subsidy.
SMB customer relationships increased by 3,000 in the second quarter of 2024, while second quarter 2023 SMB customer relationships grew by 4,000. Enterprise PSUs grew by 4,000 in the second quarter of 2024 versus 6,000 added in the second quarter of 2023.
Charter continues to work with federal, state and local governments to bring Spectrum Internet to unserved and underserved communities. During the second quarter of 2024, Charter activated 89,000 subsidized rural passings. Within Charter’s subsidized rural footprint, total residential and SMB customer relationships increased by 36,000 in the second quarter of 2024.
1.
Based on Broadband Download Speed nationally in Opensignal USA: Fixed Broadband Experience Report – National View, May 2024. Based on Opensignal independent analysis of mean download speed. © 2024 Opensignal Limited.
2.
Based on Charter’s analysis of Ookla® Speedtest Intelligence® data for overall mobile WiFi and Cellular performance for 1Q24 in Charter’s footprint.
Second Quarter Financial Results
(in millions)
Three Months Ended June 30,
2024
2023
% Change
Revenues:
Internet
$ 5,806
$ 5,733
1.3 %
Video
3,867
4,188
(7.7) %
Voice
350
365
(4.2) %
Mobile service
737
539
36.9 %
Residential revenue
10,760
10,825
(0.6) %
Small and medium business
1,101
1,094
0.6 %
Enterprise
721
690
4.5 %
Commercial revenue
1,822
1,784
2.1 %
Advertising sales
397
384
3.3 %
Other
706
666
6.0 %
Total Revenues
$ 13,685
$ 13,659
0.2 %
Net income attributable to Charter shareholders
$ 1,231
$ 1,223
0.5 %
Net income attributable to Charter shareholders margin
9.0 %
9.0 %
Adjusted EBITDA1
$ 5,665
$ 5,522
2.6 %
Adjusted EBITDA margin
41.4 %
40.4 %
Capital Expenditures
$ 2,853
$ 2,834
0.7 %
Net cash flows from operating activities
$ 3,853
$ 3,311
16.4 %
Free cash flow1
$ 1,296
$ 668
94.0 %
All percentages are calculated using whole numbers. Minor differences may exist due to rounding.
1.
Adjusted EBITDA and free cash flow are non-GAAP measures defined in the “Use of Adjusted EBITDA and Free Cash Flow Information” section and are reconciled to net income attributable to Charter shareholders and net cash flows from operating activities, respectively, in the addendum of this news release.
Revenues
Second quarter revenue increased by 0.2% year-over-year to $13.7 billion, driven by growth in residential mobile service, residential Internet, enterprise and other revenues, partly offset by lower residential video revenue.
Residential revenue totaled $10.8 billion in the second quarter, a decrease of 0.6% year-over-year.
Internet revenue grew by 1.3% year-over-year to $5.8 billion, driven by promotional rate step-ups and rate adjustments, partly offset by lower bundled revenue allocation and retention offers extended to customers that previously received an ACP subsidy.
Video revenue totaled $3.9 billion in the second quarter, a decrease of 7.7% compared to the prior year period, driven by a decline in video customers during the last year and a higher mix of lower priced video packages within Charter’s video customer base, partly offset by promotional rate step-ups and video rate adjustments that pass through programmer rate increases.
Voice revenue decreased by 4.2% year-over-year to $350 million, driven by a decline in wireline voice customers over the last twelve months, partly offset by voice rate adjustments.
Second quarter mobile service revenue totaled $737 million, an increase of 36.9% year-over-year, driven by mobile line growth and higher bundled revenue allocation.
Commercial revenue increased by 2.1% year-over-year to $1.8 billion, driven by enterprise and SMB revenue growth of 4.5% and 0.6% year-over-year, respectively. The year-over-year increase in second quarter 2024 SMB revenue was driven by higher monthly SMB revenue per SMB customer, primarily due to rate adjustments, and customer relationship growth. Enterprise revenue excluding wholesale increased by 5.9% year-over-year, mostly reflecting PSU growth.
Second quarter advertising sales revenue of $397 million increased by 3.3% compared to the year-ago quarter, primarily driven by higher political revenue. Excluding political revenue in both periods, advertising sales revenue decreased by 2.2% year-over-year due to a more challenged advertising market, partly offset by higher advanced advertising revenue.
Other revenue totaled $706 million in the second quarter, an increase of 6.0% compared to the second quarter of 2023, primarily driven by higher mobile device sales.
Operating Costs and Expenses
Second quarter programming costs decreased by $268 million, or 9.8% as compared to the second quarter of 2023, reflecting fewer video customers and a higher mix of lower cost packages within Charter’s video customer base, partly offset by contractual programming rate increases and renewals.
Other costs of revenue increased by $171 million, or 12.6% year-over-year, primarily driven by higher mobile service direct costs and mobile device sales.
Costs to service customers decreased by $88 million, or 4.2% year-over-year, primarily due to lower labor costs and lower bad debt expense.
Sales and marketing expenses increased by $17 million, or 1.9% year-over-year, primarily due to higher marketing costs.
Other expenses increased by $51 million, or 4.7% as compared to the second quarter of 2023, mostly driven by an insurance expense benefit in the year-ago quarter.
Net Income Attributable to Charter Shareholders
Net income attributable to Charter shareholders totaled $1.2 billion in the second quarter of 2024, compared to $1.2 billion in the second quarter of 2023, with higher Adjusted EBITDA mostly offset by higher other operating expense primarily due to restructuring and severance costs and net amounts of litigation settlements.
Net income per basic common share attributable to Charter shareholders totaled $8.58 in the second quarter of 2024 compared to $8.15 during the same period last year. The increase was primarily the result of the factors described above in addition to a 4.5% decrease in basic weighted average common shares outstanding versus the prior year period.
Adjusted EBITDA
Second quarter Adjusted EBITDA of $5.7 billion grew by 2.6% year-over-year, reflecting growth in revenue of 0.2% and a decrease in operating expenses of 1.4%.
Capital Expenditures
Capital expenditures totaled $2.9 billion in the second quarter of 2024, an increase of $19 million compared to the second quarter of 2023. Line extensions capital expenditures totaled $1.1 billion in the second quarter of 2024, driven by Charter’s subsidized rural construction initiative and continued network expansion across residential and commercial greenfield and market fill-in opportunities. Second quarter capital expenditures excluding line extensions totaled $1.7 billion, a decrease of $18 million compared to the second quarter of 2023.
Charter now expects full year 2024 capital expenditures to total approximately $12.0 billion, a decrease from Charter’s previously expected range of between $12.2 billion and $12.4 billion. The decrease reflects lower Internet and video customer net additions, including the impact of the end of the ACP, which drives lower CPE and capitalized installation costs. Charter continues to expect line extensions capital expenditures of approximately $4.5 billion and network evolution spend of approximately $1.6 billion, compared to $4.0 billion and $0.9 billion, respectively, in 2023. The actual amount of capital expenditures in 2024 will depend on a number of factors including, but not limited to, the pace of Charter’s network evolution and expansion initiatives, supply chain timing and growth rates in Charter’s residential and commercial businesses.
Cash Flow and Free Cash Flow
During the second quarter of 2024, net cash flows from operating activities totaled $3.9 billion, compared to $3.3 billion in the prior year quarter. The year-over-year increase in net cash flows from operating activities was primarily due to higher Adjusted EBITDA, lower cash taxes due to timing and a more favorable change in working capital.
Free cash flow in the second quarter of 2024 totaled $1.3 billion, an increase of $628 million compared to the second quarter of 2023. The year-over-year increase in free cash flow was primarily driven by an increase in net cash flows from operating activities and a more favorable change in accrued expenses related to capital expenditures.
Liquidity & Financing
As of June 30, 2024, total principal amount of debt was $96.5 billion and Charter’s credit facilities provided approximately $4.1 billion of additional liquidity in excess of Charter’s $602 million cash position.
In May 2024, Charter Communications Operating, LLC (“Charter Operating”) and Charter Communications Operating Capital Corp. jointly issued $1.5 billion of 6.100% senior secured notes due June 2029 at a price of 99.944% of the aggregate principal amount and $1.5 billion of 6.550% senior secured notes due June 2034 at a price of 99.755% of the aggregate principal amount. The net proceeds were used to fund a concurrent tender offer to repurchase $2.7 billion in aggregate principal amount of Charter Operating’s 4.908% senior secured notes due July 2025, to prepay Charter Operating’s outstanding Term B-1 Loan and to pay related fees and expenses.
In June 2024, a bankruptcy remote special purpose vehicle and consolidated subsidiary of the Company, CCO EIP Financing, LLC, (the “SPV Borrower”) entered into a senior secured revolving credit facility to finance the purchase of equipment installment plan receivables (“EIP Receivables”) with a number of financial institutions (the “EIP Financing Facility”). Borrowings under the EIP Financing Facility are secured by the EIP Receivables transferred to the SPV Borrower, future collections on such EIP Receivables, and related assets consisting primarily of restricted cash.
The revolving credit facility under the EIP Financing Facility bears interest on the outstanding borrowings based on lenders’ cost of funds plus an applicable margin and was 6.46% as of June 30, 2024. The EIP Financing Facility has a final maturity date of June 20, 2028, comprised of a one-year revolving loan period, subject to annual renewal, and if not renewed, cash flows on EIP Receivables are applied to amortize the loan which may occur over a period of up to three years. SPV Borrower may borrow up to $1.25 billion under the EIP Financing Facility. As of June 30, 2024, the carrying value of the EIP Financing Facility was $873 million and is included in the Company’s consolidated balance sheets.
Share Repurchases
During the three months ended June 30, 2024, Charter purchased 1.5 million shares of Charter Class A common stock and Charter Holdings common units for $404 million.
Webcast
Charter will host a webcast on Friday, July 26, 2024 at 8:30 a.m. Eastern Time (ET) related to the contents of this release.
The webcast can be accessed live via the Company’s investor relations website at ir.charter.com. Participants should go to the webcast link no later than 10 minutes prior to the start time to register. The webcast will be archived at ir.charter.com two hours after completion of the webcast.
Additional Information Available on Website
The information in this press release should be read in conjunction with the financial statements and footnotes contained in the Company’s Quarterly Report on Form 10-Q for the three and six months ended June 30, 2024, which will be posted on the “Results & SEC Filings” section of the Company’s investor relations website at ir.charter.com, when it is filed with the Securities and Exchange Commission (the “SEC”). A slide presentation to accompany the conference call and a trending schedule containing historical customer and financial data will also be available in the “Results & SEC Filings” section.
Use of Adjusted EBITDA and Free Cash Flow Information
The Company uses certain measures that are not defined by U.S. generally accepted accounting principles (“GAAP”) to evaluate various aspects of its business. Adjusted EBITDA and free cash flow are non-GAAP financial measures and should be considered in addition to, not as a substitute for, net income attributable to Charter shareholders and net cash flows from operating activities reported in accordance with GAAP. These terms, as defined by Charter, may not be comparable to similarly titled measures used by other companies. Adjusted EBITDA and free cash flow are reconciled to net income attributable to Charter shareholders and net cash flows from operating activities, respectively, in the Addendum to this release.
Adjusted EBITDA is defined as net income attributable to Charter shareholders plus net income attributable to noncontrolling interest, net interest expense, income taxes, depreciation and amortization, stock compensation expense, other income (expenses), net and other operating (income) expenses, net, such as special charges and (gain) loss on sale or retirement of assets. As such, it eliminates the significant non-cash depreciation and amortization expense that results from the capital-intensive nature of the Company’s businesses as well as other non-cash or special items, and is unaffected by the Company’s capital structure or investment activities. However, this measure is limited in that it does not reflect the periodic costs of certain capitalized tangible and intangible assets used in generating revenues and the cash cost of financing. These costs are evaluated through other financial measures.
Free cash flow is defined as net cash flows from operating activities, less capital expenditures and changes in accrued expenses related to capital expenditures.
Management and Charter’s board of directors use Adjusted EBITDA and free cash flow to assess Charter’s performance and its ability to service its debt, fund operations and make additional investments with internally generated funds. In addition, Adjusted EBITDA generally correlates to the leverage ratio calculation under the Company’s credit facilities or outstanding notes to determine compliance with the covenants contained in the facilities and notes (all such documents have been previously filed with the SEC). For the purpose of calculating compliance with leverage covenants, the Company uses Adjusted EBITDA, as presented, excluding certain expenses paid by its operating subsidiaries to other Charter entities. The Company’s debt covenants refer to these expenses as management fees, which were $366 million and $335 million for the three months ended June 30, 2024 and 2023, respectively, and $737 million and $709 million for the six months ended June 30, 2024 and 2023, respectively.
About Charter
Charter Communications, Inc. (NASDAQ:CHTR) is a leading broadband connectivity company and cable operator with services available to more than 57 million homes and businesses in 41 states through its Spectrum brand. Over an advanced communications network, the Company offers a full range of state-of-the-art residential and business services including Spectrum Internet®, TV, Mobile and Voice.
For small and medium-sized companies, Spectrum Business® delivers the same suite of broadband products and services coupled with special features and applications to enhance productivity, while for larger businesses and government entities, Spectrum Enterprise® provides highly customized, fiber-based solutions. Spectrum Reach® delivers tailored advertising and production for the modern media landscape. The Company also distributes award-winning news coverage and sports programming to its customers through Spectrum Networks. More information about Charter can be found at corporate.charter.com.
CAUTIONARY STATEMENT REGARDING FORWARD-LOOKING STATEMENTS
This communication includes forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended, regarding, among other things, our plans, strategies and prospects, both business and financial. Although we believe that our plans, intentions and expectations as reflected in or suggested by these forward-looking statements are reasonable, we cannot assure you that we will achieve or realize these plans, intentions or expectations. Forward-looking statements are inherently subject to risks, uncertainties and assumptions including, without limitation, the factors described under “Risk Factors” from time to time in our filings with the SEC. Many of the forward-looking statements contained in this communication may be identified by the use of forward-looking words such as “believe,” “expect,” “anticipate,” “should,” “planned,” “will,” “may,” “intend,” “estimated,” “aim,” “on track,” “target,” “opportunity,” “tentative,” “positioning,” “designed,” “create,” “predict,” “project,” “initiatives,” “seek,” “would,” “could,” “continue,” “ongoing,” “upside,” “increases,” “grow,” “focused on” and “potential,” among others. Important factors that could cause actual results to differ materially from the forward-looking statements we make in this communication are set forth in our annual report on Form 10-K, and in other reports or documents that we file from time to time with the SEC, and include, but are not limited to:
our ability to sustain and grow revenues and cash flow from operations by offering Internet, video, voice, mobile, advertising and other services to residential and commercial customers, to adequately meet the customer experience demands in our service areas and to maintain and grow our customer base, particularly in the face of increasingly aggressive competition, the need for innovation and the related capital expenditures;the impact of competition from other market participants, including but not limited to incumbent telephone companies, direct broadcast satellite (“DBS”) operators, wireless broadband and telephone providers, digital subscriber line (“DSL”) providers, fiber to the home providers and providers of video content over broadband Internet connections;general business conditions, unemployment levels and the level of activity in the housing sector and economic uncertainty or downturn;our ability to obtain programming at reasonable prices or to raise prices to offset, in whole or in part, the effects of higher programming costs (including retransmission consents and distribution requirements);our ability to develop and deploy new products and technologies including consumer services and service platforms;any events that disrupt our networks, information systems or properties and impair our operating activities or our reputation;the effects of governmental regulation on our business including subsidies to consumers, subsidies and incentives for competitors, costs, disruptions and possible limitations on operating flexibility related to, and our ability to comply with, regulatory conditions applicable to us;the ability to hire and retain key personnel;our ability to procure necessary services and equipment from our vendors in a timely manner and at reasonable costs including in connection with our network evolution and rural construction initiatives;the availability and access, in general, of funds to meet our debt obligations prior to or when they become due and to fund our operations and necessary capital expenditures, either through (i) cash on hand, (ii) free cash flow, or (iii) access to the capital or credit markets; andour ability to comply with all covenants in our indentures and credit facilities, any violation of which, if not cured in a timely manner, could trigger a default of our other obligations under cross-default provisions.
All forward-looking statements attributable to us or any person acting on our behalf are expressly qualified in their entirety by this cautionary statement. We are under no duty or obligation to update any of the forward-looking statements after the date of this communication.
CHARTER COMMUNICATIONS, INC. AND SUBSIDIARIES
UNAUDITED RECONCILIATION OF NON-GAAP MEASURES TO GAAP MEASURES
(dollars in millions)
Three Months Ended June 30,
Six Months Ended June 30,
2024
2023
2024
2023
Net income attributable to Charter shareholders
$ 1,231
$ 1,223
$ 2,337
$ 2,244
Plus: Net income attributable to noncontrolling interest
192
190
366
352
Interest expense, net
1,328
1,298
2,644
2,563
Income tax expense
427
444
873
818
Depreciation and amortization
2,170
2,172
4,360
4,378
Stock compensation expense
153
168
367
376
Other, net
164
27
215
141
Adjusted EBITDA (a)
$ 5,665
$ 5,522
$ 11,162
$ 10,872
Net cash flows from operating activities
$ 3,853
$ 3,311
$ 7,065
$ 6,634
Less: Purchases of property, plant and equipment
(2,853)
(2,834)
(5,644)
(5,298)
Change in accrued expenses related to capital expenditures
296
191
233
(4)
Free cash flow (a)
$ 1,296
$ 668
$ 1,654
$ 1,332
The above schedule is presented in order to reconcile Adjusted EBITDA and free cash flow, non-GAAP measures, to the most directly comparable GAAP measures in accordance with Section 401(b) of the Sarbanes-Oxley Act.
UNAUDITED ALTERNATIVE PRESENTATION OF ADJUSTED EBITDA
(dollars in millions)
Three Months Ended June 30,
Six Months Ended June 30,
2024
2023
% Change
2024
2023
% Change
REVENUES:
Internet
$ 5,806
$ 5,733
1.3 %
$ 11,632
$ 11,451
1.6 %
Video
3,867
4,188
(7.7) %
7,775
8,442
(7.9) %
Voice
350
365
(4.2) %
724
738
(1.9) %
Mobile service
737
539
36.9 %
1,422
1,036
37.4 %
Residential revenue
10,760
10,825
(0.6) %
21,553
21,667
(0.5) %
Small and medium business
1,101
1,094
0.6 %
2,189
2,185
0.2 %
Enterprise
721
690
4.5 %
1,429
1,372
4.2 %
Commercial revenue
1,822
1,784
2.1 %
3,618
3,557
1.7 %
Advertising sales
397
384
3.3 %
788
739
6.5 %
Other
706
666
6.0 %
1,405
1,349
4.2 %
Total Revenues
13,685
13,659
0.2 %
27,364
27,312
0.2 %
COSTS AND EXPENSES:
Programming
2,472
2,740
(9.8) %
5,042
5,539
(9.0) %
Other costs of revenue
1,538
1,367
12.6 %
2,996
2,695
11.2 %
Costs to service customers
1,981
2,069
(4.2) %
4,075
4,164
(2.1) %
Sales and marketing
912
895
1.9 %
1,832
1,841
(0.5) %
Other expense (b)
1,117
1,066
4.7 %
2,257
2,201
2.5 %
Total operating costs and expenses (b)
8,020
8,137
(1.4) %
16,202
16,440
(1.4) %
Adjusted EBITDA (a)
$ 5,665
$ 5,522
2.6 %
$ 11,162
$ 10,872
2.7 %
All percentages are calculated using whole numbers. Minor differences may exist due to rounding.
See footnotes on page 7.
CHARTER COMMUNICATIONS, INC. AND SUBSIDIARIES
UNAUDITED CONSOLIDATED STATEMENTS OF OPERATIONS
(dollars in millions, except per share data)
Three Months Ended June 30,
Six Months Ended June 30,
2024
2023
2024
2023
REVENUES
$ 13,685
$ 13,659
$ 27,364
$ 27,312
COSTS AND EXPENSES:
Operating costs and expenses (exclusive of items shown separately below)
8,173
8,305
16,569
16,816
Depreciation and amortization
2,170
2,172
4,360
4,378
Other operating (income) expenses, net
79
(58)
41
(48)
10,422
10,419
20,970
21,146
Income from operations
3,263
3,240
6,394
6,166
OTHER INCOME (EXPENSES):
Interest expense, net
(1,328)
(1,298)
(2,644)
(2,563)
Other expenses, net
(85)
(85)
(174)
(189)
(1,413)
(1,383)
(2,818)
(2,752)
Income before income taxes
1,850
1,857
3,576
3,414
Income tax expense
(427)
(444)
(873)
(818)
Consolidated net income
1,423
1,413
2,703
2,596
Less: Net income attributable to noncontrolling interests
(192)
(190)
(366)
(352)
Net income attributable to Charter shareholders
$ 1,231
$ 1,223
$ 2,337
$ 2,244
EARNINGS PER COMMON SHARE ATTRIBUTABLE TO CHARTER
SHAREHOLDERS:
Basic
$ 8.58
$ 8.15
$ 16.24
$ 14.89
Diluted
$ 8.49
$ 8.05
$ 16.03
$ 14.69
Weighted average common shares outstanding, basic
143,329,828
150,091,880
143,920,073
150,761,406
Weighted average common shares outstanding, diluted
144,914,860
151,975,698
145,742,397
152,727,540
CHARTER COMMUNICATIONS, INC. AND SUBSIDIARIES
CONDENSED CONSOLIDATED BALANCE SHEETS
(dollars in millions)
June 30,
December 31,
2024
2023
ASSETS
(unaudited)
CURRENT ASSETS:
Cash and cash equivalents
$ 602
$ 709
Accounts receivable, net
3,000
2,965
Prepaid expenses and other current assets
531
458
Total current assets
4,133
4,132
INVESTMENT IN CABLE PROPERTIES:
Property, plant and equipment, net
41,256
39,520
Customer relationships, net
1,319
1,745
Franchises
67,444
67,396
Goodwill
29,668
29,668
Total investment in cable properties, net
139,687
138,329
OTHER NONCURRENT ASSETS
4,791
4,732
Total assets
$ 148,611
$ 147,193
LIABILITIES AND SHAREHOLDERS’ EQUITY
CURRENT LIABILITIES:
Accounts payable, accrued and other current liabilities
$ 10,726
$ 11,214
Current portion of long-term debt
—
2,000
Total current liabilities
10,726
13,214
LONG-TERM DEBT
96,692
95,777
EQUIPMENT INSTALLMENT PLAN FINANCING FACILITY
873
—
DEFERRED INCOME TAXES
18,927
18,954
OTHER LONG-TERM LIABILITIES
4,679
4,530
SHAREHOLDERS’ EQUITY:
Controlling interest
12,879
11,086
Noncontrolling interests
3,835
3,632
Total shareholders’ equity
16,714
14,718
Total liabilities and shareholders’ equity
$ 148,611
$ 147,193
CHARTER COMMUNICATIONS, INC. AND SUBSIDIARIES
UNAUDITED CONSOLIDATED STATEMENTS OF CASH FLOWS
(dollars in millions)
Three Months Ended June 30,
Six Months Ended June 30,
2024
2023
2024
2023
CASH FLOWS FROM OPERATING ACTIVITIES:
Consolidated net income
$ 1,423
$ 1,413
$ 2,703
$ 2,596
Adjustments to reconcile consolidated net income to net cash flows from
operating activities:
Depreciation and amortization
2,170
2,172
4,360
4,378
Stock compensation expense
153
168
367
376
Noncash interest, net
8
7
16
4
Deferred income taxes
(34)
(40)
(13)
(63)
Other, net
90
83
105
187
Changes in operating assets and liabilities, net of effects from acquisitions
and dispositions:
Accounts receivable
6
(13)
(33)
57
Prepaid expenses and other assets
101
(25)
(265)
(361)
Accounts payable, accrued liabilities and other
(64)
(454)
(175)
(540)
Net cash flows from operating activities
3,853
3,311
7,065
6,634
CASH FLOWS FROM INVESTING ACTIVITIES:
Purchases of property, plant and equipment
(2,853)
(2,834)
(5,644)
(5,298)
Change in accrued expenses related to capital expenditures
296
191
233
(4)
Other, net
(172)
(207)
(225)
(287)
Net cash flows from investing activities
(2,729)
(2,850)
(5,636)
(5,589)
CASH FLOWS FROM FINANCING ACTIVITIES:
Borrowings of long-term debt
8,822
3,944
14,743
11,048
Borrowings of equipment installment plan financing facility
876
—
876
—
Repayments of long-term debt
(10,068)
(3,995)
(15,784)
(10,735)
Payments for debt issuance costs
(25)
—
(27)
(18)
Purchase of treasury stock
(361)
(326)
(877)
(1,238)
Proceeds from exercise of stock options
—
3
2
5
Purchase of noncontrolling interest
(46)
(54)
(141)
(176)
Distributions to noncontrolling interest
(61)
(80)
(64)
(83)
Other, net
(280)
(9)
(224)
(15)
Net cash flows from financing activities
(1,143)
(517)
(1,496)
(1,212)
NET DECREASE IN CASH, CASH EQUIVALENTS AND RESTRICTED CASH
(19)
(56)
(67)
(167)
CASH, CASH EQUIVALENTS AND RESTRICTED CASH, beginning of period
661
534
709
645
CASH, CASH EQUIVALENTS AND RESTRICTED CASH, end of period
$ 642
$ 478
$ 642
$ 478
CASH PAID FOR INTEREST
$ 1,362
$ 1,243
$ 2,598
$ 2,432
CASH PAID FOR TAXES
$ 569
$ 845
$ 647
$ 906
As of June 30, 2024, cash, cash equivalents and restricted cash includes $40 million of restricted cash included in prepaid expenses and other current assets in the consolidated balance sheets.
CHARTER COMMUNICATIONS, INC. AND SUBSIDIARIES
UNAUDITED SUMMARY OF OPERATING STATISTICS
(in thousands, except per customer and penetration data)
Approximate as of
June 30,
2024(c)
March 31,
2024(c)
December 31,
2023 (c)
June 30,
2023(c)
Footprint
Estimated Passings (d)
57,774
57,351
56,986
56,209
Customer Relationships (e)
Residential
29,615
29,797
29,904
30,009
SMB
2,222
2,219
2,222
2,219
Total Customer Relationships
31,837
32,016
32,126
32,228
Residential
(182)
(107)
(108)
13
SMB
3
(3)
(2)
4
Total Customer Relationships Quarterly Net Additions
(179)
(110)
(110)
17
Total Customer Relationship Penetration of Estimated Passings (f)
55.1 %
55.8 %
56.4 %
57.3 %
Monthly Residential Revenue per Residential Customer (g)
$ 120.77
$ 120.48
$ 119.41
$ 120.25
Monthly SMB Revenue per SMB Customer (h)
$ 165.28
$ 163.44
$ 162.38
$ 164.56
Residential Customer Relationships Penetration
One Product Penetration (i)
47.7 %
47.3 %
46.7 %
46.0 %
Two Product Penetration (i)
33.2 %
33.0 %
33.1 %
33.0 %
Three or More Product Penetration (i)
19.2 %
19.7 %
20.2 %
20.9 %
% Residential Non-Video Customer Relationships
57.1 %
56.0 %
54.8 %
53.1 %
Internet
Residential
28,318
28,472
28,544
28,549
SMB
2,049
2,044
2,044
2,037
Total Internet Customers
30,367
30,516
30,588
30,586
Residential
(154)
(72)
(62)
70
SMB
5
—
1
7
Total Internet Quarterly Net Additions
(149)
(72)
(61)
77
Video
Residential
12,718
13,111
13,503
14,071
SMB
591
606
619
635
Total Video Customers
13,309
13,717
14,122
14,706
Residential
(393)
(392)
(248)
(189)
SMB
(15)
(13)
(9)
(11)
Total Video Quarterly Net Additions
(408)
(405)
(257)
(200)
Voice
Residential
6,170
6,438
6,712
7,248
SMB
1,276
1,288
1,293
1,294
Total Voice Customers
7,446
7,726
8,005
8,542
Residential
(268)
(274)
(248)
(225)
SMB
(12)
(5)
(3)
4
Total Voice Quarterly Net Additions
(280)
(279)
(251)
(221)
Mobile Lines (j)
Residential
8,531
7,992
7,519
6,410
SMB
278
260
247
216
Total Mobile Lines
8,809
8,252
7,766
6,626
Residential
539
473
532
628
SMB
18
13
14
20
Total Mobile Lines Quarterly Net Additions
557
486
546
648
Enterprise (k)
Enterprise Primary Service Units (“PSUs”)
312
308
303
294
Enterprise Quarterly Net Additions
4
5
5
6
See footnotes on page 7.
CHARTER COMMUNICATIONS, INC. AND SUBSIDIARIES
UNAUDITED CAPITAL EXPENDITURES
(dollars in millions)
Three Months Ended June 30,
Six Months Ended June 30,
2024
2023
2024
2023
Customer premise equipment (l)
$ 562
$ 576
$ 1,197
$ 1,113
Scalable infrastructure (m)
362
353
690
707
Upgrade/rebuild (n)
389
392
870
681
Support capital (o)
421
431
809
825
Capital expenditures, excluding line extensions
1,734
1,752
3,566
3,326
Subsidized rural construction line extensions
565
529
992
900
Other line extensions
554
553
1,086
1,072
Total line extensions (p)
1,119
1,082
2,078
1,972
Total capital expenditures
$ 2,853
$ 2,834
$ 5,644
$ 5,298
Capital expenditures included in total related to:
Commercial services
$ 382
$ 409
$ 757
$ 776
Subsidized rural construction initiative (q)
$ 567
$ 541
$ 994
$ 932
Mobile
$ 64
$ 82
$ 123
$ 159
See footnotes on page 7.
CHARTER COMMUNICATIONS, INC. AND SUBSIDIARIES
FOOTNOTES
(a)
Adjusted EBITDA is defined as net income attributable to Charter shareholders plus net income attributable to noncontrolling interest, net interest expense, income taxes, depreciation and amortization, stock compensation expense, other (income) expenses, net and other operating (income) expenses, net such as special charges and (gain) loss on sale or retirement of assets. As such, it eliminates the significant non-cash depreciation and amortization expense that results from the capital-intensive nature of our businesses as well as other non-cash or special items, and is unaffected by our capital structure or investment activities. Free cash flow is defined as net cash flows from operating activities, less capital expenditures and changes in accrued expenses related to capital expenditures.
(b)
Other expense excludes stock compensation expense. Total operating costs and expenses excludes stock compensation expense, depreciation and amortization and other operating (income) expenses, net.
(c)
We calculate the aging of customer accounts based on the monthly billing cycle for each account in accordance with our collection policies. On that basis, at June 30, 2024, March 31, 2024, December 31, 2023 and June 30, 3023, customers included approximately 79,400, 110,000, 135,800 and 128,600 customers, respectively, whose accounts were over 60 days past due, approximately 10,000, 42,600, 54,700 and 47,000 customers, respectively, whose accounts were over 90 days past due and approximately 13,500, 283,100, 286,000 and 229,200 customers, respectively, whose accounts were over 120 days past due. The decrease in accounts past due is predominately due to revisions to customer account balances associated with the end of the Affordable Connectivity Program, including balance write-offs and conversion to payment plans. Bad debt expense associated with these past due accounts was predominantly reflected in our consolidated statements of operations in prior periods.
(d)
Passings represent our estimate of the number of units, such as single family homes, apartment and condominium units and SMB and enterprise sites passed by our cable distribution network in the areas where we offer the service indicated. These estimates are based upon the information available at this time and are updated for all periods presented when new information becomes available.
(e)
Customer relationships include the number of customers that receive one or more levels of service, encompassing Internet, video, voice and mobile services, without regard to which service(s) such customers receive. Customers who reside in residential multiple dwelling units (“MDUs”) and that are billed under bulk contracts are counted based on the number of billed units within each bulk MDU. Total customer relationships exclude enterprise and mobile-only customer relationships.
(f)
Penetration represents residential and SMB customers as a percentage of estimated passings. Penetration excludes mobile-only customers.
(g)
Monthly residential revenue per residential customer is calculated as total residential quarterly revenue divided by three divided by average residential customer relationships during the respective quarter and excludes mobile-only customer relationships.
(h)
Monthly SMB revenue per SMB customer is calculated as total SMB quarterly revenue divided by three divided by average SMB customer relationships during the respective quarter and excludes mobile-only customer relationships.
(i)
One product, two product and three or more product penetration represents the number of residential customers that subscribe to one product, two products or three or more products, respectively, as a percentage of residential customer relationships, excluding mobile-only customers.
(j)
Mobile lines include phones and tablets which require one of our standard rate plans (e.g., “Unlimited” or “By the Gig”). Mobile lines exclude wearables and other devices that do not require standard phone rate plans.
(k)
Enterprise PSUs represents the aggregate number of fiber service offerings counting each separate service offering at each customer location as an individual PSU.
(l)
Customer premise equipment includes equipment and devices located at the customer’s premise used to deliver our Internet, video and voice services (e.g., modems, routers and set-top boxes), as well as installation costs.
(m)
Scalable infrastructure includes costs, not related to customer premise equipment or our network, to secure growth of new customers or provide service enhancements (e.g., headend equipment).
(n)
Upgrade/rebuild includes costs to modify or replace existing fiber/coaxial cable networks, including our network evolution initiative.
(o)
Support capital includes costs associated with the replacement or enhancement of non-network assets (e.g., back-office systems, non-network equipment, land and buildings, vehicles, tools and test equipment).
(p)
Line extensions include network costs associated with entering new service areas (e.g., fiber/coaxial cable, amplifiers, electronic equipment, make-ready and design engineering).
(q)
The subsidized rural construction initiative subcategory includes projects for which we are receiving subsidies from federal, state and local governments, excluding customer premise equipment and installation.
View original content to download multimedia:https://www.prnewswire.com/news-releases/charter-announces-second-quarter-2024-results-302207276.html
SOURCE Charter Communications, Inc.

You may like
Technology
Axon Announces Body 5: Next-Generation Camera Built for the AI Era
Published
20 minutes agoon
October 24, 2026By
Axon Body 5 delivers 25x the AI processing power of earlier-generation cameras, with upgraded connectivity, audio and battery life to support real-time situational awareness in the field
SCOTTSDALE, Ariz., Oct. 24, 2026 /PRNewswire/ — Axon (Nasdaq: AXON), the global leader in public safety technology, today announced Axon Body 5, its newest body-worn camera designed to bring more powerful intelligence, connectivity and real-time support directly to officers in the field.
For years, Axon body cameras have helped agencies capture critical evidence and create greater transparency. Body 5 is built to help officers during the call, with information, assistance and backup on the spot.
“Officers shouldn’t have to choose between getting information and watching the scene. With Axon Body 5, they don’t,” said Rick Smith, Axon Founder and CEO. “They capture a license or document with the camera, keep their hands free and eyes up, and get information faster than writing it down and calling it in by radio. An officer fully engaged with the person in front of them, not down at a notepad, is a safer officer and a better-served community.”
Axon Body 5: Built for the AI Era
Built from the ground up for the AI era, Axon Body 5 delivers 25x the AI processing power than earlier generation Axon body cameras, alongside advancements in connectivity, audio, video and battery life. Together, these upgrades give the camera the physical power to run smarter AI features — both today and as new AI tools are developed in the future — while also making it more dependable for officers to use every day.
For the first time, Axon is also introducing two versions of its latest flagship camera: Axon Body 5 and Axon Body 5 Pro.
Both models feature several key advancements, including:
25x more processing power for AI: A powerful new computing architecture creates the capacity to support current and future AI features directly on the body camera.Enhanced video: Improved video captures clearer evidence across challenging environments, including better low-light performance.Improved connectivity: Seamless connectivity in urban and remote environments – and more precise location capability – helps officers, cameras and remote support teams stay connected when timely information matters most.Longer battery life: 20% more battery life than the previous generation helps keep the camera ready and connected throughout an officer’s shift.
The Axon Body 5 Pro will continue to gain new AI capabilities as they become available, growing along with the AI Era Plan. Additionally, new hardware features include:
A near-focus camera: An additional dedicated camera lens lets officers scan driver’s licenses to check status and search for wants or warrants in seconds, without returning to the patrol vehicle, with relevant information sent to Axon Fusus to support real-time operations.Front-facing speakers: Four additional speakers project even more powerful audio toward the person an officer is speaking with, helping real-time translations from Axon Assistant carry more clearly over heavy traffic or crowd noise. Additional memory: Extra space lets the camera run several AI tools at once, helping officers stay better informed and work faster.
Bringing More of Axon’s AI Era Into the Field
Axon Body 5 helps officers get more out of the Axon AI Era Plan by bringing smart tools right to the scene. Axon’s portfolio already supports public safety professionals across a growing range of tasks. For example, Draft One helps officers turn body-camera audio into high-quality report drafts and Axon Assistant provides voice-based information access and real-time translation.
Increasingly, Axon is also bringing AI into real-time operations.
Axon Guardian is a new category of AI features within the AI Era Plan that was specifically created to work with an officer’s field-based devices – starting with body cameras and in-car cameras – to improve safety. Guardian is designed to flag potential risks as situations unfold and create alerts when additional attention may be needed. Two of the first features include:
Escalation Detection: When an Axon Body 4 or Axon Body 5 camera is activated and recording, Guardian has the ability to detect potential conflicts in real time and create an alert in Axon Fusus. A human reviews the livestream and decides if additional support or action is needed.Approach Alert: When active on Axon Fleet 3, Guardian can detect if the door of a stopped vehicle opens and alert the officer through the in-car display and their body-worn camera.
Combined, Axon Body 5 and the expanding AI Era portfolio demonstrate the importance of AI as a critical resource to assist public safety professionals before, during and after an incident — reducing administrative burden, improving situational awareness and helping protect more lives.
Innovating Responsibly
Axon’s Responsible Innovation framework guides the development of all of its products. Designed with this in mind, Axon Body 5 and Guardian prioritize human oversight and maintain agency control over data. As a key part of the responsible innovation process, Axon’s independent Ethics and Equity Advisory Council was created to help responsibly develop and deploy new technologies with transparency, while aligning with community expectations.
General availability dates for Axon Body 5 and Axon Guardian will be announced soon. Product features and capabilities vary by configuration. For more information on Axon’s current products and services: Axon Product Catalog – Axon.com.
About Axon
Axon (Nasdaq: AXON) is the global leader in public safety technology supporting state, local, federal and international public safety agencies with technology designed to Protect Life. Complementing its mission, Axon’s growing Enterprise market focuses on protecting critical infrastructure and frontline workers across multiple industries including corporate security, hospitality, retail and healthcare. Founder-led since 1993, Axon builds products with transparency and responsibility. From TASER energy devices to today’s connected network of hardware – including cameras, drones, and robotics – cloud software, sensors, and AI-tools, the Axon ecosystem helps seamlessly protect people and places when it matters most. To ensure these technologies align with community expectations, Axon’s independent Ethics & Equity Advisory Council guides the ethical, inclusive, and accountable design of its products and services. Learn more about the EEAC and Axon’s Responsible Innovation framework at Axon Responsibility.
Non-Axon trademarks are the property of their respective owners. Axon, TASER and the Delta Logo are trademarks of Axon Enterprise, Inc., some of which are registered in the US and other countries. For more information, visit www.axon.com/legal. All rights reserved.
Please visit https://investor.axon.com and https://www.axon.com/newsroom for more information.
Media Contact:
Kate MacKinnon
Vice President, Communications
press@axon.com
View original content to download multimedia:https://www.prnewswire.com/news-releases/axon-announces-body-5-next-generation-camera-built-for-the-ai-era-302918553.html
SOURCE Axon
Technology
In HelloNation, Custom Fabrication Expert Mark Coyle Explains a Common Mistake in Custom Aluminum Design
Published
1 hour agoon
October 24, 2026By
The article explains why smart geometry, not thicker walls, creates stronger, more efficient aluminum components.
ROCHESTER, N.Y., Oct. 24, 2026 /PRNewswire/ — What early design choice causes many custom aluminum projects to become heavier, costlier, or harder to manufacture? That question is addressed in a HelloNation article featuring insights from Custom Fabrication Expert Mark Coyle of American Custom Metals, Inc. in Rochester, New York, that outlines how misunderstanding aluminum behavior leads designers to rely on thick walls instead of stronger geometry.
The article begins by explaining that many people assume thicker walls automatically make aluminum parts stronger. It notes that aluminum does not respond to wall thickness the way steel does. Instead, its performance is shaped by how the metal flows through the extrusion die. The article states that custom aluminum design is more effective when profiles use ribs, chambers, and flanges to create stiffness without adding unnecessary weight. This guidance helps readers understand why adding material often increases cost without improving strength.
The article also highlights that thicker walls change how aluminum moves during extrusion. When heavy areas fill more slowly, the metal cools unevenly and can develop stress that only appears later. The HelloNation piece explains that well-balanced geometry keeps extrusion smooth and predictable. This consistency makes it easier to maintain dimensional accuracy across long production runs. By focusing on geometry, custom aluminum design avoids the problems that come with slow extrusion speeds and uneven cooling.
Another insight in the article centers on how ribs and internal supports influence stability. It describes how a thin wall supported by a properly placed rib often performs better than a thick wall with no reinforcement. This happens because the rib helps distribute load, improve stiffness, and guide the aluminum as it cools. The article explains that this structural approach makes custom aluminum design more efficient and gives designers more control over how the final part behaves under pressure.
The article also shows why early collaboration between designer and fabricator prevents costly changes. It states that a fabricator familiar with extrusion can catch potential issues before a die is built. Small adjustments to corners or transitions can remove weak points or improve metal flow. The article notes that this teamwork keeps the design aligned with real-world production. By working together early, both sides reduce the risk of redesigning the die after the first test run.
Machining is another area where the article explains how wall thickness affects performance. Features such as deep pockets or sharp internal angles may require slow feed rates or special tooling. When walls are thicker than needed, those areas can become difficult to machine cleanly. The article states that thoughtful custom aluminum design makes machining more predictable. Small changes, such as adding radiused edges or sizing features to match standard tools, help shorten cycle times and prevent tool wear.
Thermal behavior receives detailed attention as well. The article explains that aluminum retains heat differently depending on the mass of each section. Thicker walls hold heat longer, which increases the chance of distortion during extrusion, machining, or finishing. When a design uses geometry to create strength, the material cools more evenly. This reduces warping and helps long profiles stay aligned. The article notes that stable cooling is important for components that require a precise fit and consistent shape throughout an entire production run.
Cost is also a key topic in the article. It states that heavier profiles increase material use, extrusion time, and tooling needs. A custom aluminum design that relies on geometry instead of mass lowers material consumption and keeps the fabrication process efficient. The article explains that lighter parts are easier to handle, ship, and assemble. This saves money across multiple stages of production and supports long-term manufacturing efficiency.
The article also notes that smart custom aluminum design creates profiles that behave predictably during extrusion and machining. Smooth transitions, balanced wall dimensions, and structural features help reduce the chance of distortion or dimensional drift. These elements also lower scrap rates and support reliable performance. By using geometry instead of excess material, designers build parts that maintain strength without compromising manufacturability.
As the article concludes, it emphasizes that avoiding thick walls is one of the best ways to improve performance and lower cost. It states that the most dependable custom aluminum components come from designs that use structural features to strengthen the profile. When designers understand how aluminum behaves at each stage of extrusion and machining, they create parts that are strong, efficient, and consistent from batch to batch. This approach turns custom aluminum design into a predictable process rather than a series of uncertain adjustments.
A Common Mistake in Custom Aluminum Design features insights from Mark Coyle, Custom Fabrication Expert of Rochester, NY, in HelloNation.
About HelloNation
HelloNation is America’s Good News Network, a premier media platform built on the idea that good news travels faster when real people tell real stories. Through its community-focused publications and innovative “edvertising” approach, HelloNation delivers content that informs, inspires, and spotlights the leaders making a meaningful impact in their communities.
View original content to download multimedia:https://www.prnewswire.com/news-releases/in-hellonation-custom-fabrication-expert-mark-coyle-explains-a-common-mistake-in-custom-aluminum-design-302918282.html
SOURCE HelloNation
Technology
World Young Scientist Summit 2026 Opens in Wenzhou, Zhejiang
Published
2 hours agoon
October 24, 2026By
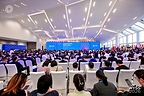
WENZHOU, China, Oct. 24, 2026 /PRNewswire/ — This is a report by China Daily:
On October 24, the World Young Scientist Summit 2026 opened in Wenzhou, Zhejiang. The event is hosted by the China Association for Science and Technology (CAST), the Zhejiang Provincial People’s Government, and the World Association of Young Scientists. Nearly 800 representatives, including scientists, educators, and entrepreneurs from more than 60 countries and regions, are attending the summit.
He Junke, Vice President of CAST in charge of daily work and First Secretary of its Secretariat; Lian Yimin, Chairman and Party Group Secretary of the Zhejiang Provincial Committee of the Chinese People’s Political Consultative Conference; Marcelo Knobel, Executive Director of The World Academy of Sciences; and Zhang Zhenfeng, Member of the Standing Committee of the CPC Zhejiang Provincial Committee and Secretary of the CPC Wenzhou Municipal Committee, attended the summit and delivered remarks. Yao Gaoyuan, Vice Governor of the Zhejiang Provincial People’s Government, presided over the first segment of the plenary session.
With the theme “Gathering Talents Worldwide to Create a Better Future,” the summit’s annual agenda is “Global Youth Action in the AI Era: Building a Sustainable Future.” It aims to draw on the insights of young people around the world, deepen international sci-tech cooperation, and jointly address questions about young people, science, the world and the future.
Efim Zelmanov, Fields Medalist and Foreign Member of the Chinese Academy of Sciences; Chen Yunji, Deputy Director of the Institute of Computing Technology, CAS, and Director of the National Key Laboratory of Processor Chips; Mary Garson, President of the International Union of Pure and Applied Chemistry; and Lu Chaoyang, Member of the Standing Committee of CAST, Executive Dean of the Shanghai Institute of Advanced Study, University of Science and Technology of China, and Chairman of the Council of the World Association of Young Scientists, delivered keynote speeches respectively on education reform in the AI era, AI and processor chips, young women scientists’ participation in science, and quantum computing. They explored new opportunities for scientific research, talent cultivation, and international cooperation in the AI era.
This year’s summit placed greater emphasis on the growth needs of young scientists, with young talents under the age of 45 accounting for 88 percent of participants. It aimed to build a cluster of international journals, bring together young scientific talent, facilitate a batch of international collaborative projects and advance the application and commercialization of scientific and technological achievements. The summit released the Report on the Distribution and Mobility of Young Scientists in the Field of Embodied Intelligence, launched the World Young Scientist Summit Partner Journal Program and the 2026 World Young Scientist Innovation and Entrepreneurship Growth Support Program. It also published the “Young Scientist Pioneers 2035” list and announced the 2026 Sustainable Development Young Scientist Award. The awards were presented to four Chinese and foreign scientists.
Chen Tianrun, Founder of Hangzhou Moxin Technology Co., Ltd.; Yuan Yang, Assistant to the Dean of the Institute for Interdisciplinary Information Sciences at Tsinghua University; and two of the 2026 Sustainable Development Young Scientist Award winners, César de la Fuente and Nicola Segata, among other Chinese and foreign young scientist representatives, spoke at the flash-talk session to share their research practices and reflections.
In addition, the conference focused on fields such as future manufacturing, quantum information, embodied intelligence, brain-computer intelligence, environmental science, deep-sea resources, and life and health, and held 12 parallel forums. It also included the “Gravitation π” Future Technology and Concept Products Exhibition and Exchange, local thematic side events, and sci-tech and humanities study visits, further building an interdisciplinary, cross-regional and cross-sector platform for youth sci-tech exchange and cooperation.
View original content to download multimedia:https://www.prnewswire.com/news-releases/world-young-scientist-summit-2026-opens-in-wenzhou-zhejiang-302918664.html
SOURCE China Daily


Axon Announces Body 5: Next-Generation Camera Built for the AI Era

In HelloNation, Custom Fabrication Expert Mark Coyle Explains a Common Mistake in Custom Aluminum Design

World Young Scientist Summit 2026 Opens in Wenzhou, Zhejiang

Send Rakhi to UK swiftly with UK Gifts Portal

Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

Nullmax and Renesas Forge Strategic Partnership to Deliver Competitive ADAS Solutions for the Global Market

Why You Should Build on #NEAR – Co-founder Illia Polosukhin at CV Labs
Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

NEAR End of Year Town Hall 2021: The Open Web World, MetaBUILD 2 Hackathon and 2021 recap
Trending
-
 Technology4 days ago
Sophont Launches Holon-S1 to Reveal Tumor Biology from Routine Pathology Slides
-
 Technology4 days ago
NC AI Officially Releases VARCO Sound, the Generative AI Sound Production Service
-
 Technology5 days ago
OppFi Announces its Third Quarter 2026 Earnings Conference Call
-
 Technology4 days ago
Trinity Acquires Verix, Adding AI-Powered Next-Best-Action and Omnichannel Orchestration to the TrinityEDGE Platform
-
 Coin Market4 days ago
Stablecoin transfers quadruple to $891B as US banks expand adoption: Report
-
 Technology4 days ago
Workato Launches Self-Serve Platform in Singapore, Opening Enterprise AI to a Broader Community of Builders
-
 Technology1 day ago
Miami Startup BOB Raises $5.5M To Build An AI-Powered Banking Platform
-
 Technology4 days ago
Findem Takes on Candidate Fraud With Authenticity Suite Pro