
Technology
Blackbaud Announces 2024 Second Quarter Results

Published
2 years agoon
By
Revenue Growth More than Doubles Year over Year with Significantly Improved Profitability; Blackbaud Board of Directors Approve Expanded $800 Million Stock Repurchase Authorization
CHARLESTON, S.C., July 30, 2024 /PRNewswire/ — Blackbaud (NASDAQ: BLKB), the leading provider of software for powering social impact, today announced financial results for its second quarter ended June 30, 2024.
“We continue to execute on our strategic initiatives, and I am optimistic about the opportunities ahead in the near, mid and long-term,” said Mike Gianoni, president, CEO and vice chairman of the board of directors, Blackbaud. “Blackbaud is a clear market leader with a path to penetrate even further into a rich market opportunity. The leverage of our financial model allows us to aggressively invest in innovation, which provides great value to our existing customers and increases our ability to attract new prospects. And our strong cash flow enables us to execute on a purposeful and prudent stock repurchase program to improve shareholder value.”
Second Quarter 2024 Results Compared to Second Quarter 2023 Results:
GAAP total revenue was $287.3 million, up 6.0% and non-GAAP organic revenue increased 6.7%.GAAP recurring revenue was $281.4 million, up 7.2% and represented 98% of total revenue. Non-GAAP organic recurring revenue increased 7.2%.GAAP income from operations was $42.1 million, with GAAP operating margin of 14.7%, an increase of 1,460 basis points.Non-GAAP income from operations was $86.1 million, with non-GAAP operating margin of 30.0%, an increase of 260 basis points.GAAP net income was $21.8 million, with GAAP diluted earnings per share of $0.42, up $0.38 per share.Non-GAAP net income was $55.7 million, with non-GAAP diluted earnings per share of $1.08, up $0.10 per share.Non-GAAP adjusted EBITDA was $102.5 million, up $13.7 million, with non-GAAP adjusted EBITDA margin of 35.7%, an increase of 290 basis points.GAAP net cash provided by operating activities was $53.8 million, an increase of $0.6 million, with GAAP operating cash flow margin of 18.7%, a decrease of 90 basis points.Non-GAAP free cash flow was $32.6 million, a decrease of $4.4 million, with non-GAAP free cash flow margin of 11.4%, a decrease of 220 basis points.Non-GAAP adjusted free cash flow was $36.4 million, a decrease of $7.2 million, with non-GAAP adjusted free cash flow margin of 12.7%, a decrease of 340 basis points.
“I’m pleased with our financial performance in the second quarter as our operating plan continues to deliver greatly improved profitable growth,” said Tony Boor, executive vice president and CFO, Blackbaud. “In the second quarter, total revenue grew 6.0%, while non-GAAP organic revenue growth was 6.7%. Our Social Sector, representing 88% of total revenue in the quarter, grew even faster at 8.5%. Non-GAAP adjusted EBITDA performance in the quarter was strong with a margin of 35.7%, a 290 basis points increase year over year. With our new $800 million repurchase authorization and ample debt capacity, we plan to be very purposeful about buying back our stock and believe there is no better use of capital than investing back into our business through product innovation and returning money to shareholders at this valuation.”
An explanation of all non-GAAP financial measures referenced in this press release, including the Rule of 40, is included below under the heading “Non-GAAP Financial Measures.” A reconciliation of the company’s non-GAAP financial measures to their most directly comparable GAAP measures has been provided in the financial statement tables included below in this press release.
Recent Company Highlights
Blackbaud’s board of directors reauthorized, expanded and replenished the company’s existing stock repurchase program, raising the total capacity from $500 million to $800 million available for repurchases of the company’s common stock.Blackbaud recently announced that Dale Strange has taken the reins of the Corporate Impact business and been appointed to the company’s executive leadership team as Tom Davidson, founder of EVERFI, moves to a strategic advisory role. Blackbaud was named one of America’s Best Mid-Size Companies 2024 by TIME, ranking 195 out of 500 companies based on employee satisfaction, revenue growth and sustainability transparency. At its recent spring Product Update Briefings, Blackbaud announced hundreds of product updates and rolled out new roadmaps, sharing how the company is more deeply connecting customers’ business offices, incorporating AI for greater impact, and delivering a unified view for Raiser’s Edge NXT®.Blackbaud made a strategic investment in UBIQ Education, innovators in school websites, to extend Blackbaud’s Total School Solution and offer a native integration with UBIQ’s AMAIS platform, giving customers direct access to a cutting-edge suite of marketing and admissions tools with seamless data integration across the platform.Six companies are participating in the July 2024 cohort of Blackbaud’s Social Good Startup Program, bringing innovative solutions to Blackbaud customers—from AI-powered fundraising and content tools to digital assistant chatbots. Blackbaud announced its bbcon 2024 tech conference, happening Sept. 24-26 in Seattle.
Visit www.blackbaud.com/newsroom for more information about Blackbaud’s recent highlights.
Financial Outlook
Blackbaud today reiterated its 2024 full year financial guidance:
GAAP revenue of $1.164 billion to $1.194 billionNon-GAAP adjusted EBITDA margin of 32.5% to 33.5%Non-GAAP earnings per share of $4.12 to $4.38Non-GAAP adjusted free cash flow of $254 million to $274 million
Included in its 2024 full year financial guidance are the following updated assumptions:
Non-GAAP annualized effective tax rate is expected to be approximately 24.5%Interest expense for the year is expected to be approximately $52 million to $56 millionFully diluted shares for the year are expected to be approximately 51.0 million to 52.0 millionCapital expenditures for the year are expected to be approximately $65 million to $75 million, including approximately $60 million to $70 million of capitalized software and content development costs
Blackbaud has not reconciled forward-looking full-year non-GAAP financial measures contained in this news release to their most directly comparable GAAP measures, as permitted by Item 10(e)(1)(i)(B) of Regulation S-K. Such reconciliations would require unreasonable efforts at this time to estimate and quantify with a reasonable degree of certainty various necessary GAAP components, including for example those related to compensation, acquisition transactions and integration, tax items or others that may arise during the year. These components and other factors could materially impact the amount of the future directly comparable GAAP measures, which may differ significantly from their non-GAAP counterparts.
In order to provide a meaningful basis for comparison, Blackbaud uses non-GAAP adjusted free cash flow in analyzing its operating performance. Non-GAAP adjusted free cash flow is defined as operating cash flow less capital expenditures, including costs required to be capitalized for software and content development, capital expenditures for property and equipment, plus cash outflows related to the previously disclosed Security Incident discovered in May 2020 (the “Security Incident”). Total costs related to the Security Incident exceeded the limit of our insurance coverage during the first quarter of 2022. For full year 2024, Blackbaud currently expects net cash outlays of $8 million to $13 million for ongoing legal fees related to the Security Incident. In line with the company’s policy, all associated costs due to third-party service providers and consultants, including legal fees, are expensed as incurred. Please refer to the section below titled “Non-GAAP Financial Measures” for more information on Blackbaud’s use of non-GAAP financial measures.
Stock Repurchase Program
As of July 16, 2024, Blackbaud had approximately $800.0 million remaining under its common stock repurchase program that was expanded, replenished and reauthorized in July 2024.
Conference Call Details
What: Blackbaud’s 2024 Second Quarter Conference Call
When: July 31, 2024
Time: 8:00 a.m. (Eastern Time)
Live Call: 1-877-407-3088 (US/Canada)
Webcast: Blackbaud’s Investor Relations Webpage
About Blackbaud
Blackbaud (NASDAQ: BLKB) is the leading software provider exclusively dedicated to powering social impact. Serving the nonprofit and education sectors, companies committed to social responsibility and individual change makers, Blackbaud’s essential software is built to accelerate impact in fundraising, nonprofit financial management, digital giving, grantmaking, corporate social responsibility and education management. With millions of users and over $100 billion raised, granted or managed through Blackbaud platforms every year, Blackbaud’s solutions are unleashing the potential of the people and organizations who change the world. Blackbaud has been named to Newsweek’s list of America’s Most Responsible Companies, Quartz’s list of Best Companies for Remote Workers and Forbes’ list of America’s Best Employers. A remote-first company, Blackbaud has operations in the United States, Australia, Canada, Costa Rica and the United Kingdom, supporting users in 100+ countries. Learn more at www.blackbaud.com, or follow us on X/Twitter, LinkedIn, Instagram, and Facebook.
Investor Contact
IR@blackbaud.com
Media Contact
media@blackbaud.com
Forward-Looking Statements
Except for historical information, all of the statements, expectations, and assumptions contained in this news release are forward-looking statements which are subject to the safe harbor provisions of the Private Securities Litigation Reform Act of 1995, including, but not limited to, statements regarding the predictability of our financial condition and results of operations. These statements involve a number of risks and uncertainties. Although Blackbaud attempts to be accurate in making these forward-looking statements, it is possible that future circumstances might differ from the assumptions on which such statements are based. In addition, other important factors that could cause results to differ materially include the following: management of integration of acquired companies; uncertainty regarding increased business and renewals from existing customers; a shifting revenue mix that may impact gross margin; continued success in sales growth; cybersecurity and data protection risks and related liabilities; potential litigation involving us; and the other risk factors set forth from time to time in the SEC filings for Blackbaud, copies of which are available free of charge at the SEC’s website at www.sec.gov or upon request from Blackbaud’s investor relations department. Blackbaud assumes no obligation and does not intend to update these forward-looking statements, except as required by law.
Trademarks
All Blackbaud product names appearing herein are trademarks or registered trademarks of Blackbaud, Inc.
Non-GAAP Financial Measures
Blackbaud has provided in this release financial information that has not been prepared in accordance with GAAP. Blackbaud uses non-GAAP financial measures internally in analyzing its operational performance. Accordingly, Blackbaud believes these non-GAAP measures are useful to investors, as a supplement to GAAP measures, in evaluating its ongoing operational performance and trends and in comparing its financial results from period-to-period with other companies in Blackbaud’s industry, many of which present similar non-GAAP financial measures to investors. However, these non-GAAP financial measures may not be completely comparable to similarly titled measures of other companies due to potential differences in the exact method of calculation between companies.
The non-GAAP financial measures discussed above exclude the impact of certain transactions that Blackbaud believes are not directly related to its operating performance in any particular period, but are for its long-term benefit over multiple periods. Blackbaud believes these non-GAAP financial measures reflect its ongoing business in a manner that allows for meaningful period-to-period comparisons and analysis of trends in its business.
While Blackbaud believes these non-GAAP measures provide useful supplemental information, non-GAAP financial measures should not be considered in isolation from, or as a substitute for, financial information prepared in accordance with GAAP. Investors are encouraged to review the reconciliations of these non-GAAP measures to their most directly comparable GAAP financial measures.
As previously disclosed, beginning in 2024, we apply a non-GAAP effective tax rate of 24.5% when calculating non-GAAP net income and non-GAAP diluted earnings per share. The non-GAAP tax rate utilized in future periods will be reviewed annually to determine whether it remains appropriate in consideration of our financial results including our periodic effective tax rate calculated in accordance with GAAP, our operating environment and related tax legislation in effect and other factors deemed necessary. All 2023 measures of non-GAAP net income and non-GAAP diluted earnings per share included in this news release are calculated under Blackbaud’s historical non-GAAP effective tax rate of 20.0%.
Non-GAAP free cash flow is defined as operating cash flow less capital expenditures, including costs required to be capitalized for software and content development, and capital expenditures for property and equipment. In addition, and in order to provide a meaningful basis for comparison, Blackbaud also uses non-GAAP adjusted free cash flow in analyzing its operating performance. Non-GAAP adjusted free cash flow is defined as operating cash flow less capital expenditures, including costs required to be capitalized for software and content development, and capital expenditures for property and equipment, plus cash outflows related to the Security Incident. Blackbaud believes non-GAAP free cash flow and non-GAAP adjusted free cash flow provide useful measures of the company’s operating performance. Non-GAAP free cash flow and Non-GAAP adjusted free cash flow are not intended to represent and should not be viewed as the amount of residual cash flow available for discretionary expenditures.
In addition, Blackbaud uses non-GAAP organic revenue growth, non-GAAP organic revenue growth on a constant currency basis, non-GAAP organic recurring revenue growth and non-GAAP organic recurring revenue growth on a constant currency basis, in analyzing its operating performance. Blackbaud believes that these non-GAAP measures are useful to investors, as a supplement to GAAP measures, for evaluating the periodic growth of its business on a consistent basis. Each of these measures excludes incremental acquisition-related revenue attributable to companies acquired in the current fiscal year. For companies acquired in the immediately preceding fiscal year, each of these measures reflects presentation of full-year incremental non-GAAP revenue derived from such companies as if they were combined throughout the prior period. In addition, each of these measures excludes prior period revenue associated with divested businesses. The exclusion of the prior period revenue is to present the results of the divested businesses within the results of the combined company for the same period of time in both the prior and current periods. Blackbaud believes this presentation provides a more comparable representation of its current business’ organic revenue growth and revenue run-rate.
Rule of 40 is defined as non-GAAP organic revenue growth plus non-GAAP adjusted EBITDA margin. Non-GAAP adjusted EBITDA is defined as GAAP net income plus interest, net; income tax provision (benefit); depreciation; amortization of intangible assets from business combinations; amortization of software and content development costs; stock-based compensation; employee severance; acquisition and disposition-related costs; restructuring and other real estate activities; Security Incident-related costs; and impairment of capitalized software development costs.
Blackbaud, Inc.
Consolidated Balance Sheets
(Unaudited)
(dollars in thousands, except per share amounts)
June 30,
2024
December 31,
2023
Assets
Current assets:
Cash and cash equivalents
$ 30,438
$ 31,251
Restricted cash
800,670
697,006
Accounts receivable, net of allowance of $6,006 and $6,907 at June 30, 2024 and
December 31, 2023, respectively
152,832
101,862
Customer funds receivable
2,943
353
Prepaid expenses and other current assets
92,290
99,285
Total current assets
1,079,173
929,757
Property and equipment, net
98,066
98,689
Operating lease right-of-use assets
28,489
36,927
Software and content development costs, net
165,465
160,194
Goodwill
1,053,249
1,053,738
Intangible assets, net
549,521
581,937
Other assets
68,785
51,037
Total assets
$ 3,042,748
$ 2,912,279
Liabilities and stockholders’ equity
Current liabilities:
Trade accounts payable
$ 44,038
$ 25,184
Accrued expenses and other current liabilities
51,682
64,322
Due to customers
802,372
695,842
Debt, current portion
23,786
19,259
Deferred revenue, current portion
427,098
392,530
Total current liabilities
1,348,976
1,197,137
Debt, net of current portion
998,071
760,405
Deferred tax liability
75,397
93,292
Deferred revenue, net of current portion
2,315
2,397
Operating lease liabilities, net of current portion
36,290
40,085
Other liabilities
4,362
10,258
Total liabilities
2,465,411
2,103,574
Commitments and contingencies
Stockholders’ equity:
Preferred stock; 20,000,000 shares authorized, none outstanding
—
—
Common stock, $0.001 par value; 180,000,000 shares authorized, 70,883,488 and
69,188,304 shares issued at June 30, 2024 and December 31, 2023, respectively;
51,623,951 and 53,625,440 shares outstanding at June 30, 2024 and December 31, 2023,
respectively
71
69
Additional paid-in capital
1,208,624
1,203,012
Treasury stock, at cost; 19,259,537 and 15,562,864 shares at June 30, 2024 and
December 31, 2023, respectively
(857,452)
(591,557)
Accumulated other comprehensive income (loss)
175
(1,688)
Retained earnings
225,919
198,869
Total stockholders’ equity
577,337
808,705
Total liabilities and stockholders’ equity
$ 3,042,748
$ 2,912,279
Blackbaud, Inc.
Consolidated Statements of Comprehensive Income (Loss)
(Unaudited)
(dollars in thousands, except per share amounts)
Three months ended
June 30,
Six months ended
June 30,
2024
2023
2024
2023
Revenue
Recurring
$ 281,376
$ 262,390
$ 552,894
$ 515,138
One-time services and other
5,910
8,652
13,642
17,657
Total revenue
287,286
271,042
566,536
532,795
Cost of revenue
Cost of recurring
119,810
113,926
238,998
228,426
Cost of one-time services and other
4,890
7,549
11,908
16,161
Total cost of revenue
124,700
121,475
250,906
244,587
Gross profit
162,586
149,567
315,630
288,208
Operating expenses
Sales, marketing and customer success
47,081
53,191
97,946
107,576
Research and development
39,068
36,146
81,870
76,737
General and administrative
33,443
59,148
81,197
111,986
Amortization
902
788
1,806
1,562
Total operating expenses
120,494
149,273
262,819
297,861
Income (loss) from operations
42,092
294
52,811
(9,653)
Interest expense
(15,715)
(11,167)
(25,991)
(21,829)
Other income, net
3,310
2,778
6,657
4,785
Income (loss) before provision (benefit) for income taxes
29,687
(8,095)
33,477
(26,697)
Income tax provision (benefit)
7,883
(10,200)
6,427
(14,101)
Net income (loss)
$ 21,804
$ 2,105
$ 27,050
$ (12,596)
Earnings (loss) per share
Basic
$ 0.43
$ 0.04
$ 0.53
$ (0.24)
Diluted
$ 0.42
$ 0.04
$ 0.52
$ (0.24)
Common shares and equivalents outstanding
Basic weighted average shares
50,747,337
52,642,411
51,399,853
52,389,112
Diluted weighted average shares
51,677,418
53,643,124
52,371,927
52,389,112
Other comprehensive (loss) income
Foreign currency translation adjustment
$ 339
$ 3,055
$ (846)
$ 5,213
Unrealized (loss) gain on derivative instruments, net of tax
(1,386)
5,383
2,709
(5,309)
Total other comprehensive (loss) income
(1,047)
8,438
1,863
(96)
Comprehensive income (loss)
$ 20,757
$ 10,543
$ 28,913
$ (12,692)
Blackbaud, Inc.
Consolidated Statements of Cash Flows
(Unaudited)
Six months ended
June 30,
(dollars in thousands)
2024
2023
Cash flows from operating activities
Net income (loss)
$ 27,050
$ (12,596)
Adjustments to reconcile net income (loss) to net cash provided by operating activities:
Depreciation and amortization
60,553
53,622
Provision for credit losses and sales returns
519
3,798
Stock-based compensation expense
57,856
63,289
Deferred taxes
(18,810)
(33,101)
Amortization of deferred financing costs and discount
984
963
Loss on disposition of business
1,561
—
Other non-cash adjustments
2,462
(1,569)
Changes in operating assets and liabilities, net of acquisition and disposal of businesses:
Accounts receivable
(53,062)
(69,624)
Prepaid expenses and other assets
(2,473)
9,470
Trade accounts payable
19,146
(3,431)
Accrued expenses and other liabilities
(13,579)
11,948
Deferred revenue
36,228
52,233
Net cash provided by operating activities
118,435
75,002
Cash flows from investing activities
Purchase of property and equipment
(6,118)
(2,779)
Capitalized software and content development costs
(28,392)
(28,756)
Net cash used in disposition of business
(1,179)
—
Other investing activities
(5,029)
—
Net cash used in investing activities
(40,718)
(31,535)
Cash flows from financing activities
Proceeds from issuance of debt
1,211,600
158,000
Payments on debt
(966,680)
(171,824)
Debt issuance costs
(6,458)
—
Employee taxes paid for withheld shares upon equity award settlement
(54,483)
(33,687)
Change in due to customers
106,851
61,313
Change in customer funds receivable
(2,577)
(3,359)
Purchase of treasury stock
(262,596)
—
Net cash provided by financing activities
25,657
10,443
Effect of exchange rate on cash, cash equivalents and restricted cash
(523)
2,489
Net increase in cash, cash equivalents and restricted cash
102,851
56,399
Cash, cash equivalents and restricted cash, beginning of period
728,257
733,931
Cash, cash equivalents and restricted cash, end of period
$ 831,108
$ 790,330
The following table provides a reconciliation of cash and cash equivalents and restricted cash reported within the consolidated balance sheets that sum to the total of the same such amounts shown above in the consolidated statements of cash flows:
(dollars in thousands)
June 30,
2024
December 31,
2023
Cash and cash equivalents
$ 30,438
$ 31,251
Restricted cash
800,670
697,006
Total cash, cash equivalents and restricted cash in the statement of cash flows
$ 831,108
$ 728,257
Blackbaud, Inc.
Reconciliation of GAAP to Non-GAAP Financial Measures
(Unaudited)
(dollars in thousands, except per share amounts)
Three months ended
June 30,
Six months ended
June 30,
2024
2023
2024
2023
GAAP Revenue
$ 287,286
$ 271,042
$ 566,536
$ 532,795
GAAP gross profit
$ 162,586
$ 149,567
$ 315,630
$ 288,208
GAAP gross margin
56.6 %
55.2 %
55.7 %
54.1 %
Non-GAAP adjustments:
Add: Stock-based compensation expense
3,377
4,143
7,151
8,097
Add: Amortization of intangibles from business combinations
14,639
13,136
29,302
26,247
Add: Employee severance
—
54
—
797
Subtotal
18,016
17,333
36,453
35,141
Non-GAAP gross profit
$ 180,602
$ 166,900
$ 352,083
$ 323,349
Non-GAAP gross margin
62.9 %
61.6 %
62.1 %
60.7 %
GAAP income (loss) from operations
$ 42,092
$ 294
$ 52,811
$ (9,653)
GAAP operating margin
14.7 %
0.1 %
9.3 %
(1.8) %
Non-GAAP adjustments:
Add: Stock-based compensation expense
24,286
33,364
57,856
63,289
Add: Amortization of intangibles from business combinations
15,541
13,924
31,108
27,809
Add: Employee severance
—
632
—
4,954
Add: Acquisition and disposition-related costs
2,398
(849)
4,653
(230)
Add: Security Incident-related costs(1)
1,822
26,777
12,145
44,560
Subtotal
44,047
73,848
105,762
140,382
Non-GAAP income from operations
$ 86,139
$ 74,142
$ 158,573
$ 130,729
Non-GAAP operating margin
30.0 %
27.4 %
28.0 %
24.5 %
GAAP income (loss) before provision (benefit) for income taxes
$ 29,687
$ (8,095)
$ 33,477
$ (26,697)
GAAP net income (loss)
$ 21,804
$ 2,105
$ 27,050
$ (12,596)
Shares used in computing GAAP diluted earnings (loss) per share
51,677,418
53,643,124
52,371,927
52,389,112
GAAP diluted earnings (loss) per share
$ 0.42
$ 0.04
$ 0.52
$ (0.24)
Non-GAAP adjustments:
Add: GAAP income tax provision (benefit)
7,883
(10,200)
6,427
(14,101)
Add: Total non-GAAP adjustments affecting income from operations
44,047
73,848
105,762
140,382
Non-GAAP income before provision for income taxes
73,734
65,753
139,239
113,685
Assumed non-GAAP income tax provision(2)
18,065
13,151
34,114
22,737
Non-GAAP net income
$ 55,669
$ 52,602
$ 105,125
$ 90,948
Shares used in computing non-GAAP diluted earnings per share
51,677,418
53,643,124
52,371,927
53,168,985
Non-GAAP diluted earnings per share
$ 1.08
$ 0.98
$ 2.01
$ 1.71
(1)
Includes Security Incident-related costs incurred during the three and six months ended June 30, 2024 of $1.8 million and $12.1 million, respectively, which includes approximately $0.0 million and $7.0 million, respectively, in recorded liabilities for loss contingencies, and during the three and six months ended June 30, 2023 of $26.8 million and $44.6 million, respectively, which included approximately $19.8 million and $30.0 million, respectively, in recorded aggregate liabilities for loss contingencies. Recorded expenses consisted primarily of payments to third-party service providers and consultants, including legal fees, as well as settlements of customer claims, negotiated settlements and accruals for certain loss contingencies. Not included in this adjustment were costs associated with enhancements to our cybersecurity program. For full year 2024, we currently expect pre-tax expenses of approximately $5 million to $10 million and cash outlays of approximately $8 million to $13 million for ongoing legal fees related to the Security Incident. Not included in these ranges are our previous settlements or current accruals for loss contingencies related to the matters discussed below. In line with our policy, legal fees are expensed as incurred. As of June 30, 2024, we have recorded approximately $8.5 million in aggregate liabilities for loss contingencies, which included $6.8 million for our settlement with the Attorney General of the State of California on June 13, 2024, and other accruals based primarily on recent negotiations with certain customers related to the Security Incident that we believe we can reasonably estimate. It is reasonably possible that our estimated or actual losses may change in the near term for those matters and be materially in excess of the amounts accrued, but we are unable at this time to reasonably estimate the possible additional loss. There are other Security Incident-related matters, including customer claims, customer constituent class actions and governmental investigations, for which we have not recorded a liability for a loss contingency as of June 30, 2024 because we are unable at this time to reasonably estimate the possible loss or range of loss. Each of these matters could, separately or in the aggregate, result in an adverse judgment, settlement, fine, penalty or other resolution, the amount, scope and timing of which we are currently unable to predict, but could have a material adverse impact on our results of operations, cash flows or financial condition.
(2)
Beginning in 2024, we now apply a non-GAAP effective tax rate of 24.5% when calculating non-GAAP net income and non-GAAP diluted earnings per share. For the three and six months ended June 30, 2023, the tax impact related to non-GAAP adjustments is calculated under our historical non-GAAP effective tax rate of 20.0%.
Blackbaud, Inc.
Reconciliation of GAAP to Non-GAAP Financial Measures (continued)
(Unaudited)
(dollars in thousands)
Three months ended
June 30,
Six months ended
June 30,
2024
2023
2024
2023
GAAP revenue(1)
$ 287,286
$ 271,042
$ 566,536
$ 532,795
GAAP revenue growth
6.0 %
6.3 %
Less: Non-GAAP revenue from divested businesses(2)
—
(1,851)
—
(2,497)
Non-GAAP organic revenue(2)
$ 287,286
$ 269,191
$ 566,536
$ 530,298
Non-GAAP organic revenue growth
6.7 %
6.8 %
Non-GAAP organic revenue(3)
$ 287,286
$ 269,191
$ 566,536
$ 530,298
Foreign currency impact on non-GAAP organic revenue(4)
(195)
—
(1,106)
—
Non-GAAP organic revenue on constant currency basis(4)
$ 287,091
$ 269,191
$ 565,430
$ 530,298
Non-GAAP organic revenue growth on constant currency basis
6.6 %
6.6 %
GAAP recurring revenue
$ 281,376
$ 262,390
$ 552,894
$ 515,138
GAAP recurring revenue growth
7.2 %
7.3 %
Less: Non-GAAP recurring revenue from divested businesses(2)
—
—
—
—
Non-GAAP organic recurring revenue(3)
$ 281,376
$ 262,390
$ 552,894
$ 515,138
Non-GAAP organic recurring revenue growth
7.2 %
7.3 %
Non-GAAP organic recurring revenue(2)
$ 281,376
$ 262,390
$ 552,894
$ 515,138
Foreign currency impact on non-GAAP organic recurring revenue(4)
(197)
—
(1,065)
—
Non-GAAP organic recurring revenue on constant currency basis(4)
$ 281,179
$ 262,390
$ 551,829
$ 515,138
Non-GAAP organic recurring revenue growth on constant
currency basis
7.2 %
7.1 %
(1)
Includes EVERFI revenue of $23.8 million and $27.3 million for the three months ended June 30, 2024 and 2023, respectively, and $47.3 million and $54.2 million for the six months ended June 30, 2024 and 2023, respectively.
(2)
Non-GAAP revenue from divested businesses excludes revenue associated with divested businesses. The exclusion of the prior period revenue is to present the results of the divested business with the results of the combined company for the same period of time in both the prior and current periods.
(3)
Non-GAAP organic revenue and non-GAAP organic recurring revenue for the prior year periods presented herein may not agree to non-GAAP organic revenue and non-GAAP organic recurring revenue presented in the respective prior period quarterly financial information solely due to the manner in which non-GAAP organic revenue growth and non-GAAP organic recurring revenue growth are calculated.
(4)
To determine non-GAAP organic revenue growth and non-GAAP organic recurring revenue growth on a constant currency basis, revenues from entities reporting in foreign currencies were translated to U.S. Dollars using the comparable prior period’s quarterly weighted average foreign currency exchange rates. The primary foreign currencies creating the impact are the Australian Dollar, British Pound, Canadian Dollar and Euro.
Blackbaud, Inc.
Reconciliation of GAAP to Non-GAAP Financial Measures (continued)
(Unaudited)
(dollars in thousands)
Three months ended
June 30,
Six months ended
June 30,
2024
2023
2024
2023
GAAP net income (loss)
$ 21,804
$ 2,105
$ 27,050
$ (12,596)
Non-GAAP adjustments:
Add: Interest, net
12,900
8,859
21,128
18,285
Add: GAAP income tax provision (benefit)
7,883
(10,200)
6,427
(14,101)
Add: Depreciation
3,253
3,272
6,328
6,608
Add: Amortization of intangibles from business combinations
15,541
13,924
31,108
27,809
Add: Amortization of software and content development costs(1)
12,639
10,934
24,729
21,540
Subtotal
52,216
26,789
89,720
60,141
Non-GAAP EBITDA
$ 74,020
$ 28,894
$ 116,770
$ 47,545
Non-GAAP EBITDA margin(2)
25.8 %
20.6 %
Non-GAAP adjustments:
Add: Stock-based compensation expense
24,286
33,364
57,856
63,289
Add: Employee severance
—
632
—
4,954
Add: Acquisition and disposition-related costs(3)
2,398
(849)
4,653
(230)
Add: Security Incident-related costs(3)
1,822
26,777
12,145
44,560
Subtotal
28,506
59,924
74,654
112,573
Non-GAAP adjusted EBITDA
$ 102,526
$ 88,818
$ 191,424
$ 160,118
Non-GAAP adjusted EBITDA margin(4)
35.7 %
33.8 %
Rule of 40(5)
42.4 %
40.6 %
Non-GAAP adjusted EBITDA
102,526
88,818
191,424
160,118
Foreign currency impact on Non-GAAP adjusted EBITDA(6)
(88)
574
(503)
1,871
Non-GAAP adjusted EBITDA on constant currency basis(6)
$ 102,438
$ 89,392
$ 190,921
$ 161,989
Non-GAAP adjusted EBITDA margin on constant currency basis
35.7 %
33.8 %
Rule of 40 on constant currency basis(7)
42.3 %
40.4 %
(1)
Includes amortization expense related to software and content development costs, and amortization expense from capitalized cloud computing implementation costs.
(2)
Measured by GAAP revenue divided by non-GAAP EBITDA.
(3)
See additional details in the reconciliation of GAAP to Non-GAAP operating income above.
(4)
Measured by non-GAAP organic revenue divided by non-GAAP adjusted EBITDA.
(5)
Measured by non-GAAP organic revenue growth plus non-GAAP adjusted EBITDA margin. See Non-GAAP organic revenue growth table above.
(6)
To determine non-GAAP adjusted EBITDA on a constant currency basis, non-GAAP adjusted EBITDA from entities reporting in foreign currencies were translated to U.S. Dollars using the comparable prior period’s quarterly weighted average foreign currency exchange rates. The primary foreign currencies creating the impact are the Australian Dollar, British Pound, Canadian Dollar and Euro.
(7)
Measured by non-GAAP organic revenue growth on constant currency basis plus non-GAAP adjusted EBITDA margin on constant currency basis.
(dollars in thousands)
Six months ended
June 30,
2024
2023
GAAP net cash provided by operating activities
$ 118,435
$ 75,002
GAAP operating cash flow margin
20.9 %
14.1 %
Non-GAAP adjustments:
Less: purchase of property and equipment
(6,118)
(2,779)
Less: capitalized software and content development costs
(28,392)
(28,756)
Non-GAAP free cash flow
$ 83,925
$ 43,467
Non-GAAP free cash flow margin
14.8 %
8.2 %
Non-GAAP adjustments:
Add: Security Incident-related cash flows
5,822
15,822
Non-GAAP adjusted free cash flow
$ 89,747
$ 59,289
Non-GAAP adjusted free cash flow margin
15.8 %
11.1 %
View original content to download multimedia:https://www.prnewswire.com/news-releases/blackbaud-announces-2024-second-quarter-results-302210142.html
SOURCE Blackbaud

You may like
Technology
Warhound Launches with $200 Million to Rebuild America’s Military Working Dog Supply, Using Advanced Genetics and Defense Technology
Published
42 minutes agoon
October 23, 2026By
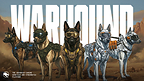
Company will produce genetically enhanced working dogs that leverage cybernetics technology to improve health and performance while ending reliance on foreign suppliers
DALLAS and COSTA MESA, Calif., Oct. 23, 2026 /PRNewswire/ — Warhound, a new defense technology company conceived by American technology entrepreneurs Ben Lamm and Palmer Luckey emerged from stealth with a $200 million seed round. Warhound will rebuild America’s domestic supply of elite working dogs for U.S. military forces, law-enforcement, emergency first response teams—a critical national security resource that the U.S. has long relied on foreign countries to provide. Led by CEO David Spirk, the company will reduce dependence on a shrinking European supply chain and strengthen America’s ability to protect its own people, infrastructure, and national security interests.
Warhound is modernizing America’s working-dog program by delivering a vertically integrated program, combining Colossal’s enhanced genetics platform and secure biobanking capabilities of America’s top-performing dog arsenal, controlled delivery through cloning with best-in-class training and animal care. Through a partnership, all dogs will be equipped by Anduril’s advanced cybernetic Augments, software, and battlefield situational awareness. The company is backed by In-Q-Tel, Sequoia Capital, ARK Invest, Franklin Templeton, 8VC, USIT, Bob Nelsen, Breyer Capital, CAZ Investments, Neogenesis, Builders VC, and Lux Capital among others. Based in Texas, Warhound will operate under the guidance of the American Humane Society which will certify its training programs and support the reunification of retired military working dogs with their former handlers and adoption protocols.
“Palmer, Ben and the Warhound team are exceptional. Sequoia is proud to back them,” said Shaun Maguire, Partner at Sequoia Capital.
Warhound is bringing together Colossal’s breakthroughs in genetics, cloning, and animal biology with Anduril’s advanced defense technology to fundamentally change how America produces, trains, and protects its military working dogs. Colossal’s science will help produce healthier dogs with characteristics suited to demanding missions, while Anduril’s technology will give dogs and their handlers greater awareness and protection in the field.
“Every day, we ask dogs to put their lives on the line to protect ours. They detect explosives, protect our troops, and run toward dangers that most people are trained to run away from. Yet we’re still relying on outdated approaches to breeding and training these extraordinary animals, with too many never making it through the process. We have an opportunity to fundamentally change that. Colossal has spent years pioneering breakthroughs in genetics, cloning, and animal biology, and now we’re applying that science to give these dogs the best possible chance at a long, healthy life and a successful mission. If we’re going to ask man’s best friend to protect America, we owe it to them to use every tool at our disposal to protect them, too,” said Ben Lamm.
Since the Army established the K-9 Corps in 1942, military working dogs have served alongside America’s armed forces for more than 84 years—detecting threats, protecting service members and supporting missions worldwide. That program has evolved in The United States Department of War’s (DOW) Military Working Dog Program, which currently includes 2,200+ working dog teams that are operationally critical for detection and patrol work, and a critical part of the defense infrastructure of the country. More than 80% of U.S. military working dogs are currently acquired from Europe, creating a critical interdependency on foreign nations for an asset the Pentagon itself calls irreplaceable. That dependency is compounding: after a rigorous, roughly three-year acquisition-and-training pipeline, less than half of the dogs procured are ultimately deemed fit for service, meaning the U.S. must source and train roughly 200 dogs today to field 100 working animals tomorrow.
“Man’s best friend deserves man’s best tech,” said Palmer Luckey.
David Spirk has been named the CEO of Warhound. As a veteran of the United States Marine Corps, he worked as an intelligence specialist with multiple deployments and ultimately served as the Deputy Associate Director of National Intelligence for Afghanistan and Pakistan at the Office of the Director of National Intelligence representing the Intelligence Community at the White House and on Capital Hill. He has an extensive background in the U.S. military, intelligence community, and federal data governance, specifically focused on scaling algorithmic warfare and creating data driven advantages. More recently, he was a Senior Counselor at Palantir Technologies where he focused on expanding the company’s software footprints across the U.S. government, allied international partners, and commercial sectors. Previously, he was appointed the First Chief Data Officer (CDO) for the Department of War, where he worked on accelerating the military’s data-driven capabilities and was the first CDO for the U.S. Special Operations Command (USSOCOM).
“Our long-term goal is simple: healthier dogs, better-prepared teams, and more service members and first responders coming home safely. Leading Warhound, and strengthening America’s working-dog capabilities, is an opportunity to apply my experience to a mission I care deeply about: protecting people and helping the animals who support them,” said David Spirk. “My focus is building a team that can turn scientific advances into capabilities that work in the field.”
Building Healthier, More Capable Working Dogs to Protect Both Dogs and People
The concept of Warhound was conceived years ago by Palmer and Ben after a discussion at Peter Diamandis’ Moonshots Summit. Military working-dog programs face a costly challenge: more than half of candidate dogs fail to complete training, while reliance on overseas breeders leaves the United States dependent on a constrained foreign supply chain. Warhound was created to improve that system—producing fewer dogs with a greater likelihood of remaining healthy, completing training, and succeeding in their missions.
Warhound dog-and-handler teams will also connect Anduril’s integrated capabilities—including eye and ear protection and Eagle Eye technology—will help safeguard working dogs, their handlers and the wider unit while supporting safer, more effective missions.
“For millennia, people have selectively bred dogs to be companions and helpmates. Modern biotechnology gives us a more precise way to shape some of their traits, thus improving both the work dogs do and their own health and well-being,” said Alta Charo, Warren P. Knowles Professor Emerita of Law and Bioethics at the University of Wisconsin–Madison. “The Warhound project offers the possibility of improving working dogs’ health and welfare while supporting the lifesaving work they do. But we still must look carefully at who benefits, what risks the animals bear, and how concern for animal welfare translates into practice through careful evaluation of the evidence, meaningful oversight, and responsibility for the dogs throughout their lives, including retirement. The American Humane Society brings valuable experience through its military working dog reunification efforts and Pups4Patriots program. That experience provides a foundation, but public trust has to be earned through the care we provide and the commitments we keep.”
Animal welfare is central to the program. By improving health, durability, and training success, Warhound will significantly reduce washouts, limit the number of dogs unnecessarily entering intensive training and enable safer, more effective missions. Technologies and therapeutics developed through the program will also be made available to all dogs and ultimately improve the health of all dogs, not only those serving alongside America’s service men and women. Together, these capabilities will establish a secure domestic supply of military working dogs while giving American service members healthier, more capable canine partners.
“Working dogs are extraordinary animals whose courage and loyalty save lives,” said Dr. Robin Ganzert, President and CEO of American Humane Society. “We owe these dogs a commitment to their well-being that matches their service to us. What excites me about Warhound is the opportunity to make health, welfare, and exceptional care fundamental to a working-dog program from the very beginning. Success means helping these dogs thrive throughout their lives—from training and active service to the loving, dignified retirement every canine hero deserves.”
Warhound is built to take today’s level of performance and make it better: using cutting edge engineering and technology, on American soil, from American companies, without the wait times, price volatility, or geopolitical exposure of a foreign supply chain.
About Warhound
Warhound is a Texas-based defense technology company building a secure domestic supply of healthier, more capable working dogs for the U.S. military, law enforcement and emergency responders. Conceived by Palmer Luckey and Ben Lamm, Warhound combines biotechnology licensed from Colossal Biosciences with advanced training and Anduril’s cybernetic augments and software. The company aims to reduce reliance on foreign suppliers, improve canine health and performance, and enhance safety for dogs and their handlers. Animal welfare is central to Warhound’s mission, with a commitment to lifelong care from birth through training, service and retirement. To follow along, please visit: warhound.com.
About Anduril
Anduril Industries is a defense technology company that builds autonomous systems and a common operating layer to give the United States and its allies a persistent advantage in sensing, decision-making, and force projection.
About the American Humane Society
The American Humane Society is the country’s first national humane organization and a global leader in animal welfare. Founded in 1877, American Humane has been at the forefront of protecting animals, rescuing them from cruelty, abuse, and natural disasters, and setting the gold standard in science-based welfare certifications. The organization oversees prominent programs including the iconic “No Animals Were Harmed®” film and television certification, the American Humane Certified™ farm and zoo standards, military working dog reunifications, and the Pups4Patriots™ service dog program. Learn more at americanhumane.org.
About Colossal Biosciences
Colossal was founded by emerging technology and software entrepreneur Ben Lamm and world-renowned geneticist and serial biotech entrepreneur George Church, Ph.D., and is the first to apply CRISPR technology for the purposes of species de-extinction. Colossal creates innovative technologies for species restoration, critically endangered species protection and the repopulation of critical ecosystems that support the continuation of life on Earth. Colossal is accepting humanity’s duty to restore Earth to a healthier state, while also solving for the future economies and biological necessities of the human condition through cutting-edge science and technologies. To follow along, please visit: www.colossal.com.
View original content to download multimedia:https://www.prnewswire.com/news-releases/warhound-launches-with-200-million-to-rebuild-americas-military-working-dog-supply-using-advanced-genetics-and-defense-technology-302918435.html
SOURCE Warhound
Technology
Best Version Media Names Chris Laurence Next CEO; Kevin O’Brien Transitions to CRO
Published
42 minutes agoon
October 23, 2026By
Leadership investment strengthens companywide execution and sharpens focus on Publisher success and revenue growth
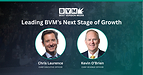
BROOKFIELD, Wis., Oct. 23, 2026 /PRNewswire/ — Best Version Media (BVM), a local media and marketing company serving more than 1,300 communities across the United States and Canada, today announced that Chris Laurence has joined the company as Chief Executive Officer. Kevin O’Brien, who previously served as CEO, will transition to Chief Revenue Officer, focusing on leading BVM’s sales field and accelerating revenue growth.
The appointments reflect BVM’s investment in leadership to support its next stage of growth. By establishing dedicated executive leadership for the broader organization and the sales field, BVM is strengthening its ability to execute across the business while supporting its independent Publishers and the local businesses they serve.
“Our growth has brought us to a point where leading the overall company and leading our sales field each deserve a dedicated focus,” said O’Brien. “This transition allows me to concentrate on working with our sales leaders and Publishers, strengthening the field, and helping more local businesses connect with their communities. I’m excited to partner with Chris as we build on BVM’s momentum.”
Laurence brings experience as CEO, CFO, and COO of public, private, and private equity-backed companies, where he has led growth, operational improvement, and technology transformation. Before moving into operating roles, he was a general partner at Brentwood Associates, a Los Angeles-based private equity firm.
“BVM has built a powerful combination of community storytelling, local relationships, and marketing solutions for small businesses,” said Laurence. “I look forward to working with Kevin and the entire team to build on that foundation, strengthen how we operate, and support the success of our Publishers and clients.”
As CEO, Laurence will lead BVM’s overall strategy and operations, working with the team to scale operations and support the success of our Publishers and the local businesses they serve. As CRO, O’Brien will focus on sales leadership, Publisher growth, and revenue generation. Together, they will help advance BVM’s print and digital offerings and position the company for continued growth.
About Best Version Media
Founded in 2007, Best Version Media (BVM) connects local businesses with customers through community magazines, targeted digital advertising, and online presence management tools. Serving more than 1,300 communities across the United States and Canada, BVM’s network of independent Publishers builds relationships with local businesses and brings community stories to life. BVM is a portfolio company of H.I.G. Capital. To learn more, visit www.bestversionmedia.com.
View original content to download multimedia:https://www.prnewswire.com/news-releases/best-version-media-names-chris-laurence-next-ceo-kevin-obrien-transitions-to-cro-302918458.html
SOURCE Best Version Media, LLC
Technology
Dow and Small Caps Climb Weekly While Nasdaq Slips on Megacap Earnings Charges
Published
42 minutes agoon
October 23, 2026By
VANCOUVER, BC, Oct. 23, 2026 /PRNewswire/ — Stock Preachers News Commentary – Stocks closed a volatile earnings week with a split verdict: the Dow gained 0.64% and the Russell 2000 jumped 2.07%, while the Nasdaq Composite fell 0.45% and the S&P 500 slipped 0.22%. The VIX rose to 19.40 and the VXN climbed to 28.13 as traders weighed a wave of third-quarter results. Gold dropped 3.47% and silver fell 4.90% on the week, while WTI crude rose 3.74% on Thursday alone. The 10-year Treasury yield eased 11 basis points to 4.99%. Active Companies from around the markets with current developments this week include: Meta Platforms, Inc. (Nasdaq: META), Texas Instruments Incorporated (Nasdaq: TXN), RTX (NYSE: RTX), IBM (NYSE: IBM), and First Citizens BancShares, Inc. (Nasdaq: FCNCA).
Large-cap benchmarks diverged sharply this week. The Dow closed at 52,337.54, up 0.64% for the week despite a 1% drop on Friday, while the S&P 500 ended at 7,642.22, down 0.22% weekly after touching a week high of 7,770.40. The Nasdaq Composite settled at 26,022.45, down 0.45% on the week, dragged by a rough stretch for megacap tech following a batch of earnings reports.
The Russell 2000 was the standout, closing at 2,777.63 for a 2.07% weekly gain, outperforming its large-cap peers as investors rotated toward smaller names. RSI readings show the Nasdaq at 38.9 and the S&P 500 at 43.5, both in cooler territory, while the Dow’s RSI of 54.1 reflects its relative strength this week.
Volatility ticked higher into the weekend, with the VIX up 0.96 points for the week to 19.40 and the VXN up a full point to 28.13. In commodities, natural gas spiked 8.66% on Thursday alone even as it remained down 0.65% for the week, while copper rose 2.44% daily. The dollar firmed slightly against the euro, with EUR/USD down 0.24% on the week to 1.12.
The full report also breaks down key support and resistance levels for each index, additional earnings movers, and sentiment heading into next week’s sessions.
CONTINUED… Read this and more news for Meta Platforms, Inc. (Nasdaq: META), Texas Instruments Incorporated (Nasdaq: TXN), RTX (NYSE: RTX), IBM (NYSE: IBM), and First Citizens BancShares, Inc. (Nasdaq: FCNCA) at: https://stockpreachers.com/articles/small-caps-lead-big-tech-lags-as-earnings-season-shakes-the-tape/
In other industry developments and happenings in the market this week include:
Meta Platforms, Inc. (Nasdaq: META) Meta reported third-quarter revenue of $64.60 billion, up 26% year over year, but net income of $9.86 billion reflected a $9.89 billion charge tied to an agreement with 52 state attorneys general over teen mental health and social media litigation. Diluted EPS was $3.83, up 265% year over year; excluding the litigation charge, EPS would have been $7.40.
Operating margin fell to 20% from 40% a year earlier, while costs and expenses rose 68% to $51.61 billion. Capital expenditures, including finance lease payments, totaled $34.91 billion, and free cash flow was negative $2.12 billion for the quarter.
“We hit major milestones this quarter toward delivering personal superintelligence for everyone – including launching Muse and Muse Wonder, our first frontier model,” said Mark Zuckerberg, Meta founder and CEO. “Our investments are paying off, the core business is strong, and we’re seeing velocity across the board.” The company guided fourth-quarter revenue to a range of $73-76 billion and raised full-year 2026 total expense guidance to $175-179 billion. Read the release.
Texas Instruments Incorporated (Nasdaq: TXN) Texas Instruments reported third-quarter revenue of $6.06 billion, up 28% from a year earlier, with net income of $2.43 billion and earnings per share of $2.62. Operating profit rose 73% to $2.87 billion, and revenue increased 11% sequentially.
“Revenue increased 11% sequentially and 28% from the same quarter a year ago with continued broad growth in industrial, automotive and data center,” said Haviv Ilan, TI’s chairman, president and CEO. Trailing 12-month cash flow from operations was $9.9 billion, with free cash flow of $8.4 billion.
The company returned $5.8 billion to shareholders over the trailing 12 months and guided fourth-quarter revenue to a range of $5.80 billion to $6.30 billion, with earnings per share expected between $2.45 and $2.79. Read the release.
RTX (NYSE: RTX) RTX reported third-quarter sales of $25.0 billion, up 11% versus the prior year and 12% organically, with adjusted EPS of $2.26, up 33% from a year earlier. GAAP EPS was $1.89. Operating cash flow was $2.9 billion and free cash flow was $2.1 billion, with results including $0.25 of IEEPA cost recovery per share.
The company’s backlog reached a record $340 billion, including $176 billion commercial and $164 billion defense, after over $81 billion of new awards including Tomahawk and AMRAAM multi-year production contracts.
“Our strong execution and operational focus in the third quarter enabled RTX to deliver double-digit organic sales growth across commercial aerospace and defense,” said RTX Chairman and CEO Chris Calio. The company raised its full-year adjusted EPS outlook to $7.65-$7.75 and adjusted sales guidance to $97.0-$97.5 billion. Read the release.
IBM (NYSE: IBM) IBM reported third-quarter revenue of $17.1 billion, up 5% as reported and 6% at constant currency, with Software revenue up 8% and Infrastructure revenue up 4%. GAAP diluted earnings per share were $2.31, up 26% year over year, while operating (non-GAAP) EPS was $2.95, up 11%.
The company generated $4.0 billion in net cash from operating activities in the quarter and $3.0 billion in free cash flow, up $0.7 billion year over year. Year to date, free cash flow reached $7.8 billion.
“Disciplined execution throughout the quarter drove accelerated revenue growth and strong free cash flow,” said Arvind Krishna, IBM chairman, president and chief executive officer. IBM now expects full-year free cash flow to increase by more than $1 billion year over year, while continuing to guide constant currency revenue growth of four to five percent. Read the release.
First Citizens BancShares, Inc. (Nasdaq: FCNCA) First Citizens BancShares reported third-quarter net income of $606 million, down from $672 million in the linked quarter. Net income available to common stockholders was $577 million, or $51.23 per common share, a $63 million decrease from the prior quarter’s $640 million.
Net interest income rose to $1.70 billion, up $43 million from the linked quarter, while net interest margin declined 3 basis points to 3.07%. The company completed its BMO Branch Acquisition on September 4, 2026, assuming approximately $4.9 billion in deposits and acquiring approximately $650 million in loans.
“We returned $600 million to our stockholders through share repurchases and further optimized our balance sheet by repaying another $8.0 billion of the Purchase Money Note,” said Chairman and CEO Frank B. Holding, Jr. The board approved a new repurchase plan authorizing up to $1.2 billion of Class A common shares through 2027. Read the release.
Contact Information:
Media Contact: info@stockpreachers.com
DISCLAIMER: Nothing in this article should be considered as personalized financial advice. We are not licensed under securities laws to address your particular financial situation. No communication by our employees to you should be deemed as personalized financial advice. Please consult a licensed financial advisor before making any investment decision. This is a market commentary and is not a paid advertisement. This article is being distributed by Stock Preachers, which is wholly owned and operated by Market Equities Limited (“MEL”), a company incorporated under the laws of Ireland. This is an independent market commentary published on a non-paid basis. MEL has not been paid any fee by any company mentioned in this article for its production or distribution, and MEL has no advertising or digital media agreement with any company mentioned in this article. The companies mentioned have not reviewed or approved this article. Market Equities and its owners, operators, directors, and affiliates may, from time to time, hold positions in securities mentioned in this article or in the broad-market index funds that track them, and reserve the right to buy, sell, or hold such securities at any time without further notice. Information in this article was obtained from sources believed to be reliable, including company news releases and public market data, but its accuracy cannot be guaranteed. Market data is as of the time stated and may be delayed. Portions of this commentary were produced with the assistance of automated tools from that data and reviewed against it. Investing in securities involves risk, including the possible loss of some or all of your investment. Technical analysis describes past price and volume behavior and does not predict future results; support and resistance levels can fail at any time. References to the companies named in this article are provided solely as market and sector context and as summaries of each company’s own public news releases. No partnership, affiliation, or endorsement is implied, and nothing in this article is a recommendation to buy, sell, or hold any security. Quotations attributed to company executives are reproduced from those companies’ own news releases. Forward-Looking Statements: This article may contain forward-looking statements within the meaning of Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934, including statements made by the companies mentioned in their own news releases. Such statements involve risks and uncertainties, and actual results may differ materially. Readers should review each company’s filings with the SEC and applicable Canadian securities regulators. Eagle Eye is an investor signal-intelligence platform affiliated with the publisher of this article. Eagle Eye is not a broker-dealer, and nothing it provides is investment advice. Data may be delayed. Always do your own research.
View original content to download multimedia:https://www.prnewswire.com/news-releases/dow-and-small-caps-climb-weekly-while-nasdaq-slips-on-megacap-earnings-charges-302918459.html
SOURCE Stock Preachers


Warhound Launches with $200 Million to Rebuild America’s Military Working Dog Supply, Using Advanced Genetics and Defense Technology

Best Version Media Names Chris Laurence Next CEO; Kevin O’Brien Transitions to CRO

Dow and Small Caps Climb Weekly While Nasdaq Slips on Megacap Earnings Charges

Send Rakhi to UK swiftly with UK Gifts Portal

Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

Nullmax and Renesas Forge Strategic Partnership to Deliver Competitive ADAS Solutions for the Global Market

Why You Should Build on #NEAR – Co-founder Illia Polosukhin at CV Labs
Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

NEAR End of Year Town Hall 2021: The Open Web World, MetaBUILD 2 Hackathon and 2021 recap
Trending
-

 Technology5 days ago
GMIF2026: AI Inference Powers the “Token Factory” and Drives System-Level Rethinking of Memory & Storage
-
 Technology5 days ago
HISTOINDEX AND A*STAR PARTNER TO ADVANCE EARLY-STAGE DEVELOPMENT OF PIPELINE THERAPIES FOR FIBROTIC DISEASES
-

 Technology4 days ago
InstaMall Launches Same-Day Fashion Delivery Experience, Bringing 80+ Brands to Shoppers’ Doors in Miami
-

 Coin Market4 days ago
World Liberty’s USD1 stablecoin sheds $400M in market cap in two weeks
-
 Technology5 days ago
Truecaller announces preliminary numbers for the third quarter 2026
-
 Technology5 days ago
Trend Micro Announces Up to ¥10 Billion toward Cyber Resilience Initiative to Strengthen Security for Japanese Organizations in the AI Era
-

 Technology5 days ago
SALMON SECURES $140 MILLION (PHP 8.8 BILLION) TO DOUBLE DOWN ON THE GROWTH OPPORTUNITY IN THE PHILIPPINES
-
 Technology4 days ago
Treasuries Rallied as Tech Slid, and the Crowded Bet Against Bonds Felt It