
Technology
Former U.S. Senator Martha McSally Joins Second Front Systems as Independent Board Director

Published
2 years agoon
By
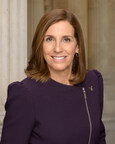
Her three decades in national security and public service further strengthens Second Front’s commitment to delivering cutting-edge technologies to U.S. and its Allies
WILMINGTON, Del., Aug. 12, 2024 /PRNewswire/ — Second Front Systems (2F), a public-benefit software company focused on facilitating the delivery of mission-critical software solutions, today announced that the Honorable Martha McSally has been appointed as a member of 2F’s board of directors, effective immediately.
In her role as an independent board director, Martha brings her extensive strategic leadership experience to support the company’s mission of enabling government access to commercially proven software as a service (SaaS) applications, in alignment with its national security mission. Her exceptional career in public service—first in the U.S. Air Force and then as a member of both houses of Congress—provides 2F with a unique perspective that blends strategic vision and a granular understanding of what it takes for warfighters and national security professionals to deliver on mission imperatives.
“Having Martha join our board is a testament to the vital role we play in the national security ecosystem,” said Tyler Sweatt, CEO of Second Front Systems. “I’m looking forward to working with and learning from her vast experience, from her time in uniform to her time as a U.S. Senator.”
Martha brings more than 30 years of experience in national security and public policy. As a public servant, she most recently represented Arizona as a U.S. Senator, where she was a member of the Senate Committee on Armed Services, among others. She was also elected to the U.S. House of Representatives and was a member of the Committees on Armed Services and Homeland Security, including chairing the Border and Maritime Security Subcommittee.
Prior to her tenure in Congress, Martha spent 22 years in the U.S. Air Force, rising to the rank of Colonel. During her groundbreaking military career, Martha became the first woman to fly an Air Force fighter jet in combat in U.S. history and the first woman to command a fighter squadron. Martha’s squadron’s success was recognized by winning the David C. Schilling Award, awarded by the Air Force Association for the most outstanding contribution to national defense in the field of flight. Martha currently serves as a board member at CAES, CRC Surface Technologies, and The Siegfried Group.
“I’m excited to join Second Front and roll up my sleeves as we work to ensure that our national security professionals have the cutting-edge software and emerging technologies they need for their missions and to keep America safe,” said McSally. “I know firsthand from my time in Congress and on the battlefield that the type of public-private partnership that Second Front fosters is a massive strategic advantage for the United States and its allies.”
Martha’s appointment follows the announcement of Lazarus AI’s partnership with 2F to leverage the company’s Game Warden DevSecOps platform in order to securely develop and deploy software across the Department of Defense, underscoring 2F’s dedication to national security innovation.
About Second Front Systems
Second Front Systems (2F) securely fast-tracks government access to software-as-a-service (SaaS) applications to help build a safer tomorrow. As a DOD-accredited solution for up to and including TOP SECRET and also FedRAMP® In Process, 2F’s Game Warden provides a secure cloud hosting environment to accelerate the delivery of innovative tools and programs. With roots in U.S. Government service, this public-benefit, venture-backed software company is trusted by Government agencies and leading software providers, to empower them to succeed in their contributions to global security. For more information, visit https://secondfront.com/.
View original content to download multimedia:https://www.prnewswire.com/news-releases/former-us-senator-martha-mcsally-joins-second-front-systems-as-independent-board-director-302218965.html
SOURCE Second Front Systems

You may like
Technology
Telecom Argentina S.A. announces consolidated results for the nine-month period (“9M26”) and third quarter of fiscal year 2026 (“3Q26”)(2)
Published
53 seconds agoon
November 13, 2026By
Market Cap: USD 4,557.2 million1
Note: 9M26 reported figures include the effects of the adoption of inflationary accounting in accordance with IAS 29. Therefore, comments regarding 9M26 results and changes vs. 9M25 results mentioned in this press release correspond to “restated for inflation” or “constant” figures.
BUENOS AIRES, Argentina, Nov. 12, 2026 /PRNewswire/ — Telecom Argentina S.A. (“Telecom Argentina”) – (NYSE: TEO; BYMA: TECO2) announced today a consolidated Net Loss of P$56,615 million for the third quarter ended September 30, 2026, and a consolidated Net Income of P$862,959 million for the nine-month period. The Net Loss attributable to the Controlling Company amounted to P$66,216 million in 3Q26, and the Net Income attributable to the Controlling Company amounted to P$837,345 million in 9M26.
Key considerations when reading the results:
Inflation-adjusted figures: For analysis purposes, it is important to highlight that the comparative results (September 2025) reflect the year-over-year effect of inflation through September 2026, which reached 33.4%.
National CPI and FX rate
As of September 30, 2025
As of December 31, 2025
As of September 30, 2026
Annual
31.8 %
31.5 %
33.4 %
Quarterly
6.0 %
N/A
5.8 %
9-month cumulative
22.0 %
N/A
23.6 %
BNA ask FX rate (P$/US$)
1,380
1,455
1,517
FX rate – y-o-y change
42.2 %
41.0 %
9.9 %
FX rate – quarterly change
14.5 %
N/A
2.4 %
FX rate – 9-month cumulative change
33.7 %
N/A
4.3 %
USD references: for informational purposes only; they do not imply bimonetary accounting. Translated at the BNA closing ask exchange rate of each period (see table); 2025 figures are first deflated by year-over-year inflation.Loss of control of Micro Sistemas (1Q26): its results ceased to be consolidated on a line-by-line basis, which reduces “Other service revenues” vs. the comparative periods, as well as the related advertising costs.TMA perimeter: 9M26 includes 9 months of TMA contribution vs. only 7 months in 9M25. It should be noted that Telecom does not determine TMA’s commercial or pricing policies.Impact of non-recurring itemsImpairment: impairment losses recorded in 3Q26 within D, A & I, mainly P$383,870 million corresponding to the assets to be divested within the framework of the approval process of the TMA acquisition (P$370,683 million for the measurement of the group of assets to be transferred and P$13,187 million for 3G/4G and PCS licenses to be returned) and P$10,785 million to real estate held for sale. This result does not affect EBITDA or cash flow for the period.Extraordinary discounts at TMA: in 3Q26, TMA granted discounts related to billing cycle changes for approximately P$39,930 million (Internet P$28,932 million, Cable TV P$5,577 million and Fixed Telephony and Data P$5,421 million). They affected its service revenues by approximately 4.3%. Excluding this effect, they would have grown 0.9% vs. 3Q25, compared to a reported decline of 3.3%.Sale of assets: in 3Q26, the sale of copper recovered from the dismantling of Telecom’s fixed network (excluding TMA) contributed approximately 0.2 p.p. to the consolidated EBITDA margin. In 3Q25, in contrast, the consolidated margin included a contribution of approximately 1 p.p. from a copper sale carried out by TMA, recorded as a reduction in operating costs, which was not repeated in the current quarter. Excluding both effects, the year-over-year improvement in the EBITDA margin would be greater than reported.
1 Market capitalization as of November 11, 2026.
2 Unaudited non-financial information
Highlights of the quarter
3Q26
vs. 3Q25
Real growth in ARS (vs. inflation)2
TOTAL REVENUE
1,778 USD MM
+18 %
-1 %
SERVICE REVENUE
1,714 USD MM
+19 %
-0 %
ADJ. EBITDA
642 USD MM
36.1% Margin
+37 %
+13 %
EFCF1
231 USD MM
36.0% of EBITDA
+96 %
Bonifications
CAPEX
354 USD MM
19.9% of Revenue
+44 %
CPI: 33.4%
NET DEBT
2,927 USD MM
4.5 Years Debt Average Life
-9 %
NET LEVERAGE
1.2x
-0.7x
1Equity FCF is calculated based on cash flows from operating and investing activities, adjusted for movements related to financial investments, dividends from associates, acquisitions or divestitures of subsidiaries and financial interest payments.
2Revenue real growth excludes the impact of the extraordinary commercial discounts granted by TMA in the quarter (dark segment).
Revenues: consolidated revenues for 3Q26 reached US$ 1,778 million (+18% vs. 3Q25) and service revenues US$ 1,714 million (+19% vs. 3Q25). In pesos, service revenues decreased 2% in real terms vs. 3Q25, affected by the extraordinary discounts granted by TMA. Excluding this effect, they would have remained practically stable vs. 3Q25.EBITDA: US$ 642 million (+37% vs. 3Q25), with a margin of 36.1%. In pesos, it grew 13% in real terms (above inflation). Equity FCF: reached US$ 231 million (+96% vs. 3Q25), equivalent to 36.0% of EBITDA.CAPEX: totaled US$ 354 million (+44% vs. 3Q25), equivalent to 19.9% of revenues.Net debt: US$ 2,927 million as of September 30, 2026 (-9% vs. 3Q25), with an average life of 4.5 years.Net leverage: 1.2x net debt / EBITDA (-0.7x vs. 3Q25)
Quarterly evolution:
Total revenues (USD MM)
3Q25
4Q25
1Q26
2Q26
3Q26
1,501
1,556
1,706
1,726
1,778
Service revenues (USD MM)
3Q25
4Q25
1Q26
2Q26
3Q26
1,437
1,482
1,646
1,660
1,714
EBITDA (USD MM) and
EBITDA margin (%)
3Q25
4Q25
1Q26
2Q26
3Q26
470
463
593
636
642
31.3 %
29.8 %
34.8 %
36.8 %
36.1 %
Equity FCF (USD MM) and conversion
over EBITDA (%)
3Q25
4Q25
1Q26
2Q26
3Q26
118
105
109
96
231
25.1 %
22.7 %
18.4 %
15.2 %
36.0 %
CAPEX (USD MM) and
% of revenues
3Q25
4Q25
1Q26
2Q26
3Q26
246
391
314
326
354
16.4 %
25.1 %
18.4 %
18.9 %
19.9 %
Net debt (USD MM) and net leverage (Net debt /
LTM EBITDA)
3Q25
4Q25
1Q26
2Q26
3Q26
3,213
3,196
3,109
3,135
2,927
1.9x
1.7x
1.4x
1.4x
1.2x
Note: figures in the quarterly evolution are expressed in U.S. dollars.
Each quarter is presented in constant currency of its own period and divided by the BNA ask end-of-period exchange rate.
Exchange rates used (P$/US$): 3Q25: 1,380; 4Q25: 1,455; 1Q26: 1,382; 2Q26: 1,482; 3Q26: 1,517.
Operating indicators:
Operating indicators at period end
09/30/2026
09/30/2025
Δ %
Personal
Fixed lines in service (in thousands of lines)
2,852
2,758
3.4 %
Mobile customers (in thousands)
20,576
23,038
-10.7 %
Personal (Argentina)
17,943
20,348
-11.8 %
Núcleo (Paraguay) -including Wimax customers-
2,633
2,689
-2.1 %
Broadband accesses in Argentina (in thousands)
4,249
4,146
2.5 %
Pay TV Subscribers (Includes subsidiaries – in thousands)
3,597
3,447
4.3 %
ARPU Mobile Services (in P$ – Restated by inflation)
12,940.8
10,890.4
18.8 %
ARPU Broadband (in P$ – Restated by inflation)
32,466.0
33,430.9
-2.9 %
ARPU Pay TV (in P$ – Restated by inflation)
23,692.4
23,035.5
2.9 %
Telefónica Móviles Argentina (TMA)
Fixed lines in service (in thousands of lines)
2,064
2,107
-2.0 %
Mobile customers (in thousands)
20,059
19,064
5.2 %
Prepaid + Postpaid (excluding M2M)
17,008
16,192
5.0 %
Machine-to-machine (M2M)
3,052
2,872
6.2 %
Broadband accesses (in thousands)
1,671
1,610
3.8 %
Pay TV Subscribers (in thousands)
447
409
9.3 %
ARPU Mobile Services (in P$ – Restated by inflation)
10,376.2
10,140.5
2.3 %
ARPU Broadband (in P$ – Restated by inflation)
27,440.3
29,786.9
-7.9 %
ARPU Pay TV (in P$ – Restated by inflation)
25,123.3
30,322.1
-17.1 %
Personal
Mobile: at the end of 3Q26, mobile accesses in Argentina totaled 17.9 million (-11.8% vs. 3Q25). The decline is mainly explained by the disconnection of prepaid lines with no top-ups for 180 days (period reduced from 240 days in June 2026), with no significant impact on revenues. The postpaid segment grew by 1.1% (+89 thousand) vs. 3Q25 and represents 45% of the base (vs. 39% in 3Q25). In 9M26, ARPU reached P$12,940.8 (+18.8% in real terms vs. 9M25) and average monthly churn decreased to 2.0% (vs. 2.1% in 9M25).
Paraguay (Núcleo): accesses totaled 2.6 million at the end of 3Q26 (-2.1% vs. 3Q25), with a postpaid share of 32% (vs. 29% in 3Q25).Internet: accesses reached 4.2 million at the end of 3Q26 (+103 thousand or +2.5% vs. 3Q25). In 9M26, ARPU was P$32,466.0 (-2.9% in real terms vs. 9M25) and monthly churn stood at 1.4% (vs. 1.2% in 9M25).TV: subscribers totaled 3.6 million at the end of 3Q26 (+4.3% vs. 3Q25), of which 3.4 million correspond to Argentina (+4.8%). Growth was driven by the FIFA World Cup 2026 and new Football Package subscriptions. In 9M26, ARPU was P$23,692.4 (+2.9% in real terms vs. 9M25) and monthly churn remained at 1.5%.Fixed telephony: lines in service totaled 2.9 million at the end of 3Q26 (+3.4% vs. 3Q25), of which 2.6 million correspond to IP telephony.
TMA
Mobile: accesses totaled 20.1 million at the end of 3Q26 (+995 thousand or +5.2% vs. 3Q25), driven by prepaid (+7.9%) and postpaid (mainly M2M). The postpaid segment grew by 2.5% and represents 48% of the base (vs. 50% in 3Q25). In 9M26, ARPU was P$10,376.2 (+2.3% in real terms vs. 9M25) and average monthly churn decreased to 1.2% (vs. 1.8% in 9M25).Internet: accesses reached 1.7 million at the end of 3Q26 (+61 thousand or +3.8% vs. 3Q25). In 9M26, ARPU was P$27,440.3 (-7.9% in real terms vs. 9M25) and monthly churn remained at 2.0%.TV: subscribers totaled 0.4 million (+9.3% vs. 3Q25). In 9M26, ARPU was P$25,123.3 (-17.1% in real terms vs. 9M25) and average monthly churn decreased to 4.2% (vs. 4.6% in 9M25).Fixed telephony: lines in service totaled 2.1 million at the end of 3Q26 (-2.0% vs. 3Q25), of which 1.6 million correspond to IP telephony.
Average monthly ARPU and churn. ARPU in constant currency as of September 30, 2026.
The evolution of Service Revenues relative to inflation was as follows:
Evolution of Service Revenues in relation to inflation
Service revenues – real % change
Consolidated
Telecom consolidated (excluding TMA)
TMA
9M26 vs. 9M25
9.4 %
1.0 %
-0.6 %
3Q26 vs. 3Q25
-1.7 %
-0.8 %
-3.3 %
Consolidated Operating Revenues
Normalizing the extraordinary discounts granted by TMA in the quarter (approximately P$39,930 million), consolidated service revenues for 3Q26 would have reached P$2,639,900 million (-0.2% vs. 3Q25, compared to -1.7% reported). In turn, the aggregate of Mobile Services, Internet and Cable TV, considered as if it constituted total service revenues, grew 2.0% vs. 3Q25 on a consolidated basis (+3.5% vs. 3Q25 normalizing the discounts).
3Q26 vs. 3Q25
9M26 vs. 9M25
Consolidated revenues (MMP$, constant currency)
3Q26
3Q25
Δ %
9M26
9M25
Δ %
Mobile Services
1,450,985
1,380,030
5.1 %
4,275,014
3,647,972
17.2 %
Internet Services
567,955
595,228
-4.6 %
1,733,507
1,647,389
5.2 %
Cable TV Services
297,262
295,621
0.6 %
870,352
842,081
3.4 %
Fixed Telephony and Data Services
269,188
345,973
-22.2 %
851,326
897,783
-5.2 %
Other service revenues
14,580
27,674
-47.3 %
42,983
70,325
-38.9 %
REVENUES FROM SERVICES
2,599,970
2,644,526
-1.7 %
7,773,182
7,105,550
9.4 %
REVENUES FROM EQUIPMENT SALES
97,373
117,036
-16.8 %
294,828
394,037
-25.2 %
REVENUES
2,697,343
2,761,562
-2.3 %
8,068,010
7,499,587
7.6 %
Mobile Services
In 3Q26, consolidated mobile service revenues reached P$1,450,985 million (+P$70,955 million or +5.1% vs. 3Q25), consolidating its position as the main business in terms of service revenues (56% of the total in 3Q26 vs. 52% in 3Q25).
In cumulative 9M26, mobile service revenues reached P$4,275,014 million (+17.2% vs. 9M25), a variation mainly explained by the consolidation of 9 months of TMA vs. 7 months in 9M25.
Mobile Services in Argentina
As of September 30, 2026, Telecom’s mobile subscribers (excluding TMA) in Argentina amounted to approximately 17.9 million (-2.4 million or -11.8% vs. 3Q25). This decrease is mainly related to prepaid lines that do not make any top-up within the 180-day period (reduced from 240 days in June 2026) of inactivity, leading to their disconnection and removal from the customer base. In turn, the postpaid customer base grew by 1.1%, or 89 thousand customers, vs. 3Q25. As of September 30, 2026, 55% of customers corresponded to the prepaid segment and 45% to the postpaid segment, while as of September 30, 2025, prepaid customers represented 61% and postpaid customers represented 39%.
As of September 30, 2026, TMA’s mobile subscribers amounted to approximately 20.1 million (+995 thousand or +5.2% vs. 3Q25) – including M2M accesses. The postpaid base increased by 2.5% vs. 3Q25, while the prepaid base grew by 7.9%. As of September 30, 2026, postpaid accesses represent 48% of total mobile accesses (vs. 50% in 3Q25).
Mobile Services in Paraguay (“Núcleo”).
During 3Q26, mobile service revenues in Paraguay reached P$66,324 million, increasing in real terms (+P$5,056 million or +8.3% vs. 3Q25). In 9M26, mobile service revenues totaled P$191,752 million, increasing in real terms (+P$27,510 million or +16.7% vs. 9M25).
Internet Services
Consolidated Internet service revenues reached P$567,955 million in 3Q26, decreasing in real terms (-P$27,273 million or -4.6% vs. 3Q25). Normalizing the extraordinary discounts granted by TMA (P$28,932 million), consolidated Internet service revenues would have remained stable (+0.3% vs. 3Q25). During 9M26, Internet service revenues reached P$1,733,507 million (+P$86,118 million or +5.2% vs. 9M25).
As of September 30, 2026, subscribers with broadband speeds of 100 Mbps or higher represented 99% of the total subscriber base (vs. 97% as of September 30, 2025).
Cable TV Services
Consolidated cable TV service revenues reached P$297,262 million in 3Q26 (+P$1,641 million or +0.6% vs. 3Q25). Normalizing the extraordinary discounts granted by TMA (P$5,577 million), they would have grown 2.4% vs. 3Q25. During 9M26, revenues reached P$870,352 million (+P$28,271 million or +3.4% vs. 9M25). The number of TV subscribers for Telecom (excluding TMA), including Uruguay and Paraguay, reached 3.6 million (+150 thousand or +4.3% vs. 3Q25).
This growth was driven by the increase in subscriptions during the FIFA World Cup 2026, which boosted demand for bundled cable TV and internet packages to access live match broadcasts and content related to the tournament, as well as by new subscriptions to the “Pack Fútbol”.
Fixed Telephony and Data Services
Consolidated fixed telephony and data service revenues reached P$269,188 million in 3Q26 (-P$76,785 million or -22.2% vs. 3Q25). Normalizing the extraordinary discounts granted by TMA (P$5,421 million), consolidated revenues for 3Q26 would have decreased 20.6% vs. 3Q25. During 9M26, such revenues reached P$851,326 million (-P$46,457 million or -5.2% vs. 9M25).
During 9M26, the Pacheco Datacenter, one of the Company’s most important technological hubs, obtained the international “Certified Energy Efficient Datacenter Award” (CEEDA), a recognition that validates efficient energy management and the sustainable operation of data centers under global standards.
Other Service Revenues
Consolidated other service revenues reached P$14,580 million in 3Q26 (-P$13,094 million or -47.3% vs. 3Q25). During 9M26, such revenues reached P$42,983 million (-P$27,342 million or -38.9% vs. 9M25).
The decline in other service revenues was mainly attributable to the loss of control of Micro Sistemas, which provided Fintech services in Argentina, during 1Q26; as of 9M26, it is recognized as a joint venture investment.
Revenues from equipment sales
During 3Q26, consolidated revenues from equipment sales totaled P$97,373 million (-P$19,663 million or -16.8% vs. 3Q25). During 9M26, such revenues reached P$294,828 million (-P$99,209 million or -25.2% vs. 9M25).
Consolidated Operating Costs
3Q26 vs. 3Q25
9M26 vs. 9M25
Operating costs (MMP$, constant currency)
3Q26
3Q25
Δ %
9M26
9M25
Δ %
Employee benefit expenses and severance payments
(590,130)
(676,554)
-12.8 %
(1,746,509)
(1,811,784)
-3.6 %
Interconnection and transmission costs
(37,854)
(75,600)
-49.9 %
(185,264)
(205,892)
-10.0 %
Fees for services, maintenance, materials and supplies
(369,486)
(413,664)
-10.7 %
(1,028,706)
(1,032,787)
-0.4 %
Taxes and fees with the regulatory authority
(238,212)
(240,221)
-0.8 %
(712,811)
(648,813)
9.9 %
Commissions and advertising
(119,468)
(140,380)
-14.9 %
(368,766)
(398,580)
-7.5 %
Cost of equipments and handsets
(75,691)
(85,151)
-11.1 %
(243,963)
(284,537)
-14.3 %
Programming and content costs
(127,384)
(133,730)
-4.7 %
(397,588)
(372,306)
6.8 %
Bad debt expenses
(53,479)
(36,171)
47.9 %
(151,730)
(129,753)
16.9 %
Other operating expenses
(111,381)
(94,447)
17.9 %
(335,944)
(326,243)
3.0 %
Subtotal Operating costs before D, A & I
(1,723,085)
(1,895,918)
-9.1 %
(5,171,281)
(5,210,695)
-0.8 %
Depreciation, amortization and impairment of fixed assets (“D, A & I”)
(1,013,262)
(644,556)
57.2 %
(2,222,325)
(1,819,053)
22.2 %
Consolidated Operating Costs
(2,736,347)
(2,540,474)
7.7 %
(7,393,606)
(7,029,748)
5.2 %
Operating income before D, A & I
974,258
865,644
12.5 %
2,896,729
2,288,892
26.6 %
As % of Revenues
36.1 %
31.3 %
+4.8 p.p.
35.9 %
30.5 %
+5.4 p.p.
Consolidated Operating Costs, including Depreciation, Amortization and Impairment of Fixed Assets, amounted to P$2,736,347 million in 3Q26 (+P$195,873 million or +7.7% vs. 3Q25). During 9M26, such costs reached P$7,393,606 million (+P$363,858 million or +5.2% vs. 9M25).
Excluding Depreciation, Amortization and Impairment of Fixed Assets, consolidated operating costs amounted to P$1,723,085 million in 3Q26 (P$5,171,281 million in 9M26) and decreased by P$172,833 million or -9.1% vs. 3Q25 (-P$39,414 million or -0.8% in 9M26 vs. 9M25).
The cost breakdown was as follows:
Labor costs and severance payments totaled P$590,130 million in 3Q26 (-P$86,424 million or -12.8% vs. 3Q25). Telecom’s headcount (excluding TMA) totaled 17,782 employees as of September 30, 2026.Interconnection and transmission costs, which also include roaming, correspondence services, and line and circuit rentals, amounted to P$37,854 million in 3Q26 (-P$37,746 million or -49.9% vs. 3Q25).Fees for services, maintenance and materials: P$369,486 million in 3Q26 (-P$44,178 million or -10.7% vs. 3Q25).Taxes, fees and regulatory charges: P$238,212 million (-P$2,009 million or -0.8% vs. 3Q25).Commissions and advertising (agents, collection commissions and other commissions): These charges totaled P$119,468 million in 3Q26 (-P$20,912 million or -14.9% vs. 3Q25). The decrease was mainly attributable to lower advertising expenses related to Personal Pay campaigns following the loss of control of Micro Sistemas, whose results ceased to be consolidated on a line-by-line basis.Cost of equipment sold totaled P$75,691 million in 3Q26 (-P$9,460 million or -11.1% vs. 3Q25). This variation is mainly due to a decrease in the number of units sold compared to 3Q25.Programming and content costs: P$127,384 million (-P$6,346 million or -4.7% vs. 3Q25).Other costs totaled P$164,860 million (+P$34,242 million or +26.2% vs. 3Q25), including bad debt expense, which totaled P$53,479 million (+P$17,308 million or +47.9% vs. 3Q25):Bad debt expense represented 2.0% of revenues in 3Q26.Other operating costs, which include provisions for litigation and other contingencies, energy and other utilities, insurance, leases and Internet capacity, among others, amounted to P$111,381 million (+P$16,934 million or +17.9% vs. 3Q25).Depreciation, amortization and impairment of fixed assets: totaled P$1,013,262 million (+P$368,706 million or +57.2% vs. 3Q25). The increase is mainly explained by the recognition of an impairment loss of P$383,870 million related to the assets to be divested (P$370,683 million for the group of assets to be transferred and P$13,187 million for 3G/4G and PCS licenses to be returned) within the framework of the approval process of the TMA acquisition, and of P$10,785 million on real estate held for sale. Excluding these effects, the decrease is attributable to the effect of assets that reached the end of their useful lives after September 30, 2025, and to disposals of fixed assets since that date, partially offset by the impact of depreciation and amortization associated with additions made subsequent to such date.
Net Financial Results
Consolidated net financial results (including debt-related financial costs and other net financial results) recorded a gain of P$78,848 million in 3Q26 (vs. a loss of P$609,414 million in 3Q25). During the nine-month period of 2026, they recorded a gain of P$729,368 million (vs. a loss of P$913,752 million in 9M25).
3Q26 vs. 3Q25
9M26 vs. 9M25
Financial results, net (MMP$, constant currency)
3Q26
3Q25
Δ %
9M26
9M25
Δ %
Exchange differences
166,108
(429,293)
–
943,301
(530,737)
–
RECPAM
80,277
39,221
104.7 %
283,822
125,058
127.0 %
Fair value gains on financial assets at fair value through profit or loss
(18,132)
(18,644)
-2.7 %
13,844
(7,723)
–
Remeasurement in borrowings*
(361)
1,428
–
(2,789)
3,594
–
Net interest
(87,415)
(128,736)
-32.1 %
(338,408)
(320,595)
5.6 %
Others
(61,629)
(73,390)
-16.0 %
(170,402)
(183,349)
-7.1 %
Total Financial results, net
78,848
(609,414)
–
729,368
(913,752)
–
* Related to UVA-linked Notes. (Unidades de Valor Adquisitivo)
The variation in the quarter was mainly attributable to a higher foreign exchange gain, measured in real terms, of P$595,401 million: the U.S. dollar increased by 2.4% against the Argentine peso in 3Q26 (vs. 14.5% in 3Q25), while inflation remained at similar levels (5.8% vs. 6.0%). Additionally, there was a higher RECPAM gain of P$41,056 million, lower net interest of P$41,321 million and lower other negative results of P$11,761 million (mainly lower taxes and bank expenses).
In 9M26, financial results recorded a gain of P$729,368 million (vs. a loss of P$913,752 million in 9M25), mainly explained by a higher foreign exchange gain of P$1,474,038 million: the U.S. dollar increased by only 4.3% against the Argentine peso (vs. 33.7% in 9M25), while inflation remained at similar levels (23.6% vs. 22.0%). Additionally, there was a higher RECPAM gain of P$158,764 million and a higher gain from changes in the fair value of financial assets of P$21,567 million, partially offset by higher net interest of P$17,813 million.
Income Tax
Income tax resulted in a loss of P$89,522 million in 3Q26 (vs. a gain of P$134,610 million in 3Q25). During 9M26, income tax resulted in a loss of P$568,609 million (vs. a gain of P$85,894 million in 9M25).
Cash Flow
3Q26 vs. 3Q25
9M26 vs. 9M25
Cash flow (MMP$, constant currency)
3Q26
3Q25
9M26
9M25
Total cash flows provided by operating activities
761,861
758,289
2,573,534
1,728,787
Total cash flows used in investing activities
(543,534)
(621,880)
(1,970,276)
(2,754,385)
less Dividends received
(0)
–
(539)
–
less Net payments of investments not considered cash and DFI settlements
272,055
260,905
474,958
152,609
less Payments for acquisition of subsidiaries, net of cash acquired
–
224
–
1,612,319
less Cash flows from change of control in subsidiaries
7
–
46,321
–
Subtotal investing cash flows
(271,473)
(360,751)
(1,449,536)
(989,457)
Free Cash Flow (FCF)
490,388
397,538
1,123,998
739,330
Payments of DFI, interest and related expenses
(139,368)
(180,358)
(451,171)
(409,474)
Equity FCF (EFCF)
351,020
217,180
672,827
329,856
Equity FCF (operating cash flow plus investing cash flow, adjusted for net payments of investments not considered cash and DFI settlements, dividends received, acquisitions of companies and changes of control in subsidiaries, less DFI payments, interest and related expenses) totaled P$351,020 million in 3Q26 (+P$133,840 million or +61.6% vs. 3Q25), mainly explained by higher EBITDA and lower interest payments (P$139,368 million vs. P$180,358 million in 3Q25). In 9M26, Equity FCF reached P$672,827 million (vs. P$329,856 million in 9M25).
Net Financial Debt
As of September 30, 2026, our consolidated net financial position (cash and cash equivalents – net of client funds – plus financial investments and DFI* minus loans) was a net liability and totaled P$4,440,298 million, representing a decrease of P$1,327,280 million compared to Net Financial Debt as of December 31, 2025, adjusted for inflation.
* Contemplates rate swaps and NDF (non-delivery forwards) agreements.
Investments in PP&E, intangible assets and rights of use assets
3Q26 vs. 3Q25
9M26 vs. 9M25
Investments (MMP$, constant currency)
3Q26
3Q25
Δ %
9M26
9M25
Δ %
Consolidated CAPEX (additions of PP&E and intangible assets)
536,680
452,692
18.6 %
1,538,190
1,132,679
35.8 %
Telecom (excluding TMA)
331,205
283,271
16.9 %
1,041,400
791,063
31.6 %
TMA
205,475
169,421
21.3 %
496,790
341,616
45.4 %
Right-of-use asset additions
64,202
57,133
12.4 %
210,868
187,217
12.6 %
Total investments (including right-of-use assets)
600,882
509,825
17.9 %
1,749,058
1,319,896
32.5 %
CAPEX as % of consolidated revenues
19.9 %
16.4 %
+3.5 p.p.
19.1 %
15.1 %
+4.0 p.p.
CAPEX = Total investments – Right-of-use additions. TMA = Consolidated CAPEX – Telecom (excluding TMA).
In 3Q26, consolidated CAPEX (additions to PP&E and intangible assets) totaled P$536,680 million (+18.6% vs. 3Q25). In cumulative 9M26, consolidated CAPEX totaled P$1,538,190 million (+35.8% vs. 9M25).
The investments were focused on:
Expansion of both fixed and mobile data services to improve transmission and access speed offered to customers, the deployment of 4G coverage and capacity, and continued expansion of 5G to support mobile internet growth and enhance service quality.Deployment and modernization of 4G mobile access sites to improve coverage and increase mobile network capacity. The 4G/LTE rollout reached 97% urban population coverage. Our mobile network customers with access to our network experienced improved service quality, reaching average speeds of 94 Mbps.During 9M26, we continued expanding our 5G network with the addition of 887 sites.With regard to the fixed access infrastructure, during the first nine months of 2026 we continued to strengthen our broadband capabilities through the deployment of new fiber optic networks and the modernization of existing infrastructure.
Relevant financial events after September 30, 2026
Agreement with Metrotel – Divestiture of assets related to the TMA acquisition
On October 14, 2026, the Board of Directors of Telecom Argentina resolved to accept the offer made by Metrotel to Telecom Argentina and TMA and to proceed with the completion of the acts necessary to carry out the transaction, including the execution of the definitive agreements and the transfer of the contemplated assets.
In this context, Telecom Argentina and TMA entered into an asset transfer agreement under which they agreed to transfer to Metrotel a base of 6,005,425 mobile service customers and 211,566 residential internet service customers, rights of use of their radio spectrum and over the use of certain physical infrastructure (assets associated with the access network and the fiber-to-the-home network deployed in the Autonomous City of Buenos Aires). Additionally, they entered into the Framework Sharing Agreement with Metrotel, which contemplates, among others, the provision of RAN sharing, national and international roaming, co-location and fixed network port rental services. Furthermore, Telecom Argentina agreed to assign to Metrotel certain rights of use of its radio spectrum.
The consideration contemplated in the transaction amounts to US$ 450 million and comprises: (i) the consideration for the sale, assignment and transfer of the assets included in the divestiture, which will be paid in installments; and (ii) the guaranteed minimum commitment for the services to be provided over a five-year period under the Framework Sharing Agreement. A transitional services agreement in favor of Metrotel and a license agreement for the use of the “Tuenti” brand in the Argentine Republic were also executed, the amounts of which are not included in such consideration.
After October 14, 2026, Telecom Argentina and TMA began the process of transferring the identified assets to Metrotel. Final approval of the TMA acquisition is subject to verification by the Argentine Antitrust Tribunal (TDC) of the completion of the divestitures and compliance with the behavioral obligations.
Telecom Argentina is a leading telecommunications company in Argentina, offering services combining mobile telephony services, cable television services, internet services and fixed telephony services. We also provide Fintech Services, other telephone related services, such as international long-distance and wholesale services, data transmission and IT solutions outsourcing and we install, operate and develop cable television and data transmission services.
We provide our services in Argentina (mobile, cable television, internet, fixed and data, fintech services, among others), Paraguay (mobile, internet, satellite TV, fintech services, among others), Uruguay (cable television services, internet and cybersecurity services and products), the United States (fixed wholesale services) and Chile (cybersecurity services and products).
These consolidate an ecosystem of platforms and new businesses, providing a comprehensive and convergent experience for our customers.
As of September 30, 2026, Telecom Argentina has 2,153,688,011 issued and outstanding shares.
For more information, please contact Investor Relations:
Luis Fernando Rial Ubago
lfrialubago@personal.com.ar
Tomás Pellicori
tlpellicori@personal.com.ar
Eugenio Ivan
eivan@personal.com.ar
For information about Telecom Argentina’s services, visit:
www.personal.com.ar
www.personal.com.py
Disclaimer:
This document may contain statements that could constitute forward-looking statements, including, but not limited to (i) the Company’s expectations for its future performance, revenues, income, earnings per share, capital expenditures, dividends, liquidity and capital structure; (ii) the continued synergies expected from the merger between the Company and Cablevisión S.A. (or the “Merger”) and/or the acquisition of Telefónica Móviles Argentina S.A. (or the “Acquisition”); (iii) the implementation of the Company’s business strategy; (iv) the changing dynamics and growth in the telecommunications and cable markets in Argentina, Paraguay, Uruguay and the United States; (v) the Company’s outlook for new and enhanced technologies; (vi) the effects of operating in a competitive environment; (vii) the industry conditions; (viii) the outcome of certain legal proceedings; and (ix) regulatory and legal developments. Forward-looking statements may be identified by words such as “anticipate,” “believe,” “estimate,” “expect,” “intend,” “plan,” “project,” “will,” “may” and “should” or other similar expressions. Forward-looking statements are not guarantees of future performance and involve certain risks and uncertainties that are difficult to predict. In addition, certain forward-looking statements are based upon assumptions as to future events that may not prove to be accurate. Many factors could cause actual results, performance or achievements of the Company to be materially different from any future results, performance or achievements that may be expressed or implied by forward-looking statements. These factors include, among others: (i) the Company’s ability to successfully implement our business strategy and to achieve synergies resulting from the Merger and/or the Acquisition; (ii) the Company’s ability to introduce new products and services that enable business growth; (iii) uncertainties relating to political and economic conditions in Argentina, Paraguay, Uruguay and the United States, including the policies of the government in Argentina; (iv) the impact of political developments, including the policies of the government in Argentina, on the demand for securities of Argentine companies; (v) inflation, the devaluation of the peso, the Guaraní and the Uruguayan peso and exchange rate risks in Argentina, Paraguay and Uruguay; (vi) restrictions on the ability to exchange Argentine or Uruguayan pesos or Paraguayan guaraníes into foreign currencies and transfer funds abroad; (vii) the impact of currency and exchange measures or restrictions on our ability to access the international markets and our ability to repay our dollar-denominated indebtedness; (viii) the creditworthiness of our actual or potential customers; (ix) the nationalization, expropriation and/or increased government intervention in companies; (x) technological changes; (xi) the impact of legal or regulatory matters, changes in the interpretation of current or future regulations or reform and changes in the legal or regulatory environment in which the Company operates, including regulatory developments such as sanctions regimes in other jurisdictions (e.g., the United States) which impact the Company’s suppliers; (xii) the effects of increased competition; (xiii) reliance on content produced by third parties; (xiv) increasing cost of the Company’s supplies; (xv) inability to finance on reasonable terms capital expenditures required to remain competitive; (xvi) fluctuations, whether seasonal or in response to adverse macro-economic developments, in the demand for advertising; (xvii) the Company’s ability to compete and develop our business in the future; (xviii) the impact of increased national or international restrictions on the transfer or use of telecommunications technology; and (xix) the impact of the outbreak of COVID-19 on the global economy and specifically on the economies of the countries in which we operate, as well as on our operations and financial performance. Many of these factors are macroeconomic and regulatory in nature and therefore beyond the control of the Company’s management. Should one or more of these risks or uncertainties materialize, or underlying assumptions prove incorrect, actual results may vary materially from those described herein as anticipated, believed, estimated, expected, intended, planned or projected. The Company does not intend and does not assume any obligation to update the forward-looking statements contained in this document. These forward-looking statements are based upon a number of assumptions and other important factors that could cause our actual results, performance or achievements to differ materially from our future results, performance or achievements expressed or implied by such forward-looking statements. Readers are encouraged to consult the Company’s Annual Report on Form 20-F and the periodic filings made on Form 6-K, which are periodically filed with or furnished to the United States Securities and Exchange Commission, as well as the presentations periodically filed before the Argentine Securities and Exchange Commission (Comisión Nacional de Valores) and the Buenos Aires Stock Exchange (Bolsas y Mercados Argentinos), for further information concerning risks and uncertainties faced by the Company.
View original content to download multimedia:https://www.prnewswire.com/news-releases/telecom-argentina-sa-announces-consolidated-results-for-the-nine-month-period-9m26-and-third-quarter-of-fiscal-year-2026-3q262-302938509.html
SOURCE Telecom Argentina
Technology
TERAGO Reports Third Quarter and Nine Months Ended 2026 Financial Results
Published
54 seconds agoon
November 13, 2026By
TORONTO, Nov. 12, 2026 /CNW/ — TERAGO Inc. (“TERAGO” or the “Company”) (TSX: TGO), (https://terago.ca/), Canada’s largest mmWave spectrum holder (91% of spectrum held) and a leading provider of Managed Fixed Wireless Internet, 5G Private Wireless Networks and SD-WAN solutions today reported financial and operating results for the third quarter and nine months ended September 30, 2026. All figures reported in this release are in thousands of Canadian dollars.
“Adjusted EBITDA1,2 grew in both the third quarter and the first nine months of the year, reflecting the cost discipline we have built into the business,” said Daniel Vucinic, CEO of TERAGO. “ARPA¹ also continued to climb as we move upmarket, where our high-touch service model stands out and where we are seeing larger opportunities in our pipeline. Our focus is on converting that pipeline into new bookings and bringing those customers into service quickly so they begin generating recurring revenue.
We look forward to ISED’s mmWave spectrum auction. The updated schedule is an administrative adjustment, and the spectrum available and the framework for licence transition remain unchanged. As Canada’s largest mmWave spectrum holder, we are well positioned for the process and see the auction as an important step toward realizing the long-term value of our spectrum, for our shareholders and for the customers, employees and partners who are part of our growth.”
Selected Financial Highlights and Key Developments
Total revenue decreased for quarter and nine months ended September 30, 2026 by 3.2% to $6,196 and by 3.0% to $18,578 respectively, compared to $6,398 and $19,156 for the same periods in 2025. The decrease was primarily driven by a combination of decreased bookings in 2025 and delays in installations associated with larger multi-site deployments. In addition, management continued its initiatives to optimize the customer base by discontinuing service to unprofitable accounts. The overall decrease was partially offset by revenue from new customers in the current period.Adjusted EBITDA1,2 for the quarter ended September 30, 2026 increased by 3.9% to $1,009 as compared to an Adjusted EBITDA1,2 of $971 for the same period in 2025. For the nine months ended September 30, 2026, Adjusted EBITDA1,2 increased by 3.1% to $2,995 as compared to an Adjusted EBITDA1,2 of $2,906 for the same period in 2025. The increases were primarily attributable to lower salaries and related expenses in 2026 compared to the same periods in 2025.Net loss for the quarter and nine months ended September 30, 2026, was $3,695 or $(0.09) per share (basic and diluted) and $10,655 or $(0.27) per share (basic and diluted) respectively, compared to a loss of $4,060 or $(0.20) per share (basic and diluted) and $11,852 or $(0.59) per share (basic and diluted), respectively for the same periods in 2025.ARPA1 for the quarter ended September 30, 2026 increased by 4.6% to $1,298 compared to $1,241 for the same period in 2025. For the nine months ended September 30, 2026, ARPA1 increased by 3.5% to $1,277 compared to $1,233 for the same period in 2025. The increase in ARPA1 was a result of the Company’s ongoing focus to attract mid-market and large-scale, predominantly multi-location customers, as well as increasing wallet share with existing customers through its high-touch telecom aggregator service model. Churn1 for the quarter and nine months ended September 30, 2026, marginally increased to 1.1% and remained flat for the nine months ended September 30, 2026 at 1.0%, compared to 1.0% for the same periods in 2025. The Company continues to review, modify and improve its customer experience practices with a focus on reducing customer churn. Backlog MRR1 in the connectivity business decreased to $71,131 as of September 30, 2026, compared to $95,832 as of September 30, 2025. The decrease was primarily attributable to higher installation volumes, partially offset by lower booking levels experienced during fiscal 2025.
Regulatory Development
On September 24, 2026, ISED revised the timetable for the 26 GHz and 38 GHz spectrum auction, rescheduling the start of the auction from October 2027 to January 25, 2028, with associated auction milestones adjusted to reflect the revised timeline. The revised timing does not change the spectrum available for auction or the framework for eligible incumbent licensees to transition existing spectrum holdings to flexible-use-licences.
_________________________________
(1) See ” Non-IFRS Measures”
(2) See “Adjusted EBITDA” for a reconciliation of net loss to Adjusted EBITDA.
RESULTS OF OPERATIONS
Comparison of the quarter and nine months ended September 30, 2026 and 2025
(In thousands of dollars, except with respect to gross profit margin1, earnings per share1, backlog MRR1, churn rate,1 and ARPA1)
(in thousands of dollars, unaudited)
Quarter ended September 30
Nine months ended September 30
2026
2025
% Chg
2026
2025
% Chg
Financial
Total Revenue
$
6,196
6,398
(3.2)
$
18,578
19,156
(3.0)
Cost of Services1
$
1,644
1,670
(1.6)
$
4,967
5,005
(0.8)
Gross Profit Margin1
73.5 %
73.9 %
(0.6)
73.3 %
73.9 %
(0.8)
Salaries and Related Costs1
$
2,294
2,494
(8.0)
$
7,039
7,726
(8.9)
Other Operating Expenses1
$
1,249
1,263
(1.1)
$
3,577
3,519
1.6
Adjusted EBITDA1,2
$
1,009
971
3.9
$
2,995
2,906
3.1
Net Loss
$
(3,695)
(4,060)
(9.0)
$
(10,655)
(11,852)
(10.1)
Basic & diluted loss per share
$
(0.09)
(0.20)
(52.7)
$
(0.27)
(0.59)
(53.7)
Quarter ended September 30
Nine months ended September 30
2026
2025
Chg
2026
2025
Chg
Operating
Backlog MRR1
Connectivity
$
71,131
95,832
(24,701)
$
71,131
95,832
(24,701)
Churn Rate1
Connectivity
1.1 %
1.0 %
0.1 %
1.0 %
1.0 %
0.0 %
ARPA1
Connectivity
$
1,298
1,241
4.6 %
$
1,277
1,233
3.5 %
Conference Call
Management will host a conference call on Friday, November 13, 2026, at 10:00 AM ET to discuss these results.
To access the conference call, please dial 888-506-0062 or 973-528-0011 and use conference ID 716685 if applicable. Please call the conference telephone number 15 minutes prior to the start time so that you are in the queue for an operator to assist in registering and patching you through.
An archived recording of the conference call will be available through Friday, November 27, 2026. To listen to the recording, call 877-481-4010 or 919-882-2331 and enter passcode 54732# if applicable.
A reconciliation of net loss to Adjusted EBITDA1 is found below and in the MD&A for the quarter and nine months ended September 30, 2026. Adjusted EBITDA1 does not have any standardized meaning under IFRS/GAAP. TERAGO’s method of calculating Adjusted EBITDA1 may differ from other issuers and accordingly, Adjusted EBITDA1 may not be comparable to similar measures presented by other issuers. The table below reconciles net loss to Adjusted EBITDA1 for the quarter and nine months ended September 30 2026 and 2025.
_______________________________________
(1) See ” Non-IFRS Measures”
(2) See “Adjusted EBITDA” for a reconciliation of net loss to Adjusted EBITDA.
(in thousands of dollars, unaudited)
Quarter ended
September 30
Nine months ended
September 30
2026
2025
2026
2025
Adjusted EBITDA1
$
1,009
971
$
2,995
2,906
Deduct:
Depreciation of network assets, property and equipment
and amortization of intangible assets
2,078
2,293
6,433
6,940
Stock-based compensation expense, net
479
159
810
638
Restructuring and other costs
–
–
196
332
Loss from operations
$
(1,548)
(1,481)
$
(4,444)
(5,004)
Add/deduct:
Loss from sale of assets
341
341
Foreign exchange loss (gain)
1
32
10
3
Finance costs
2,198
2,214
6,392
6,550
Finance income
(52)
(8)
(191)
(46)
Net loss for the period
$
(3,695)
(4,060)
$
(10,655)
(11,852)
(1) Non-IFRS Measures
This press release contains references to “Cost of Services”, “Gross Profit Margin”, Salaries and Related Costs”, “Other Operating Expenses”, “Adjusted EBITDA”, “Backlog MRR”, “Churn” and “ARPA” which are not measures prescribed by International Financial Reporting Standards (IFRS).
Cost of Services consists of expenses related to delivering service to customers and servicing the operations of our networks. These expenses include costs for the lease of intercity facilities to connect our cities, internet transit and peering costs paid to other carriers, network real estate lease expense, spectrum lease expenses, salaries and related costs of staff directly associated with the cost of services.
Gross Profit Margin % consists of gross profit margin divided by revenue where gross profit margin is revenue less cost of services.
Salaries and related costs includes regular payroll related expenses, commissions and consulting fees. All share based compensation, restructuring and other related costs are excluded from salaries and related costs.
Other operating expenses includes sales commission expense, advertising and marketing expenses, travel expenses and administrative expenses including insurance and professional fees, communication expenses, maintenance expenses and rent expenses for office facilities. All restructuring and other related costs are excluded from other operating expenses.
Adjusted EBITDA – The Company believes that Adjusted EBITDA is useful additional information to management, the Board and investors as it provides an indication of the operational results generated by its business activities prior to taking into consideration how those activities are financed and taxed and also prior to taking into consideration asset depreciation and amortization and it excludes items that could affect the comparability of our operational results and could potentially alter the trends analysis in business performance. Excluding these items does not necessarily imply they are non-recurring, infrequent or unusual. Adjusted EBITDA is also used by some investors and analysts for the purpose of valuing a company. The Company calculates Adjusted EBITDA as earnings before deducting interest, taxes, depreciation and amortization, foreign exchange gain or loss, finance costs, finance income, gain or loss on disposal of network assets, property and equipment, impairment of property, plant & equipment and intangible assets, stock-based compensation which includes equity settled deferred share unit expense and restructuring costs. Investors are cautioned that Adjusted EBITDA should not be construed as an alternative to operating earnings (losses), or net earnings (losses) determined in accordance with IFRS as an indicator of our financial performance or as a measure of our liquidity and cash flows. Adjusted EBITDA does not take into account the impact of working capital changes, capital expenditures, debt principal reductions and other sources and uses of cash, which are disclosed in the consolidated statements of cash flows.
Backlog MRR – The term “Backlog MRR” is a measure of contracted monthly recurring revenue (MRR) from customers that have not yet been provisioned. The Company believes backlog MRR is useful additional information as it provides an indication of future revenue. Backlog MRR is not a recognized measure under IFRS and may not translate into future revenue, and accordingly, investors are cautioned in using it. The Company calculates backlog MRR by summing the MRR of new customer contracts and upgrades that are signed but not yet provisioned, as at the end of the period. TERAGO’s method of calculating backlog MRR may differ from other issuers and, accordingly, backlog MRR may not be comparable to similar measures presented by other issuers.
___________________________________
(1) See ” Non-IFRS Measures”
(2) See “Adjusted EBITDA” for a reconciliation of net loss to Adjusted EBITDA.
ARPA – The term “ARPA” refers to the Company’s average revenue per account per month in the period. The Company believes that ARPA is useful supplemental information as it provides an indication of our revenue from an individual customer on a per month basis. ARPA is not a recognized measure under IFRS and, accordingly, investors are cautioned that ARPA should not be construed as an alternative to revenue determined in accordance with IFRS as an indicator of our financial performance. The Company calculates ARPA by dividing our total revenue before revenue from early terminations by the number of customers in service during the period and we express ARPA as a rate per month. TERAGO’s method of calculating ARPA has changed from the Company’s past disclosures to exclude revenue from early termination fees, where ARPA was previously calculated as revenue divided by the number of customers in service during the period. TERAGO’s method may differ from other issuers, and accordingly, ARPA may not be comparable to similar measures presented by other issuers.
Churn – The term “churn” or “churn rate” is a measure, expressed as a percentage, of customer cancellations in a particular month. The Company calculates churn by dividing the number of customer cancellations during a month by the total number of customers at the end of the month before cancellations. The information is presented as the average monthly churn rate during the period. The Company believes that the churn rate is useful supplemental information as it provides an indication of future revenue decline and is a measure of how well the business is able to renew and keep existing customers on their existing service offerings. Churn and churn rate are not recognized measures under IFRS and, accordingly, investors are cautioned in using it. TERAGO’s method of calculating churn and churn rate may differ from other issuers and, accordingly, churn may not be comparable to similar measures presented by other issuers.
About TERAGO
TERAGO provides managed network and security services to businesses across Canada ensuring highly secure, reliable, and redundant connectivity including private 5G wireless networks, Fixed Wireless access, fiber, and cable wireline network connectivity. As Canada’s biggest mmWave spectrum holders, the Company possesses spectrum licenses in the 24 GHz and 38 GHz spectrum bands, which it utilizes to provide secure, dedicated SLA guaranteed enterprise grade performance that is technology diverse from buried cables ensuring high availability connectivity services. TERAGO serves Canadian and Global businesses operating in major markets across Canada, including Toronto, Montreal, Calgary, Edmonton, Vancouver, Ottawa and Winnipeg, and has been providing wireless services since 1999. For more information about TERAGO and its suite of wireless internet and SD-WAN solutions, please visit www.terago.ca.
Forward-Looking Statements
This news release includes certain forward-looking statements. By their nature, forward-looking statements are subject to numerous risks and uncertainties, some of which are beyond TERAGO’s control. Forward-looking statements may include but are not limited to statements regarding, the increasing importance of the mmWave spectrum, the progress of the ISED mmWave consultation, and having sufficient capital to support its growth strategy, consistently executing across all fronts of the business, success in providing Canadian enterprises with managed services and the 5G fixed wireless trials being conducted by the Company. All such statements constitute “forward-looking information” as defined under, applicable Canadian securities laws. Any statements contained herein that are not statements of historical facts constitute forward-looking information. The forward-looking statements reflect the Company’s views with respect to future events and is subject to risks, uncertainties and assumptions, including those risks set forth in the “Risk Factors” section in the Annual Information Form for the year ended December 31, 2025 available on www.sedarplus.ca and under the Company’s corporate profile. Factors that could cause actual results or events to differ materially include the inability to consistently achieve sales growth across all lines of TERAGO’s business including managed services, inability to complete successful 5G technical trials, the results of the 5G trials not being satisfactory to TERAGO or any of its technology partners, regulatory requirements may delay or inhibit the trial, the economic viability of any potential services that may result from the trial, the ability for TERAGO to further finance and support any new market opportunities that may present itself, and industry competitors who may have superior technology or are quicker to take advantage of 5G technology. Accordingly, readers should not place undue reliance on forward-looking statements as several factors could cause actual future results, conditions, actions or events to differ materially from the targets, expectations, estimates or intentions expressed with the forward-looking statements. Except as may be required by applicable Canadian securities laws, TERAGO does not intend, and disclaims any obligation, to update or revise any forward-looking statements whether in words, oral or written as a result of new information, future events or otherwise
____________________________________________
(1) See ” Non-IFRS Measures”
SOURCE TeraGo Inc.
Technology
Paytient-Greenwald Study Finds 61% of Insured Workers Have Paid for Healthcare Entirely in Cash Without Filing a Claim
Published
56 seconds agoon
November 13, 2026By

In a new study of over 2,000 employer-insured workers, 68% said they would prefer predictably paying cash for a major healthcare expense through small paycheck deductions. These findings put payment experience alongside plan design as a cost and experience lever for employers and benefits advisors.
COLUMBIA, Mo., Nov. 12, 2026 /PRNewswire/ — Employers are projecting healthcare cost increases of 11% or more without plan changes. Against that backdrop, a new national study commissioned by Paytient and conducted by Greenwald Research points to a plan design tenet that can lower premiums year over year and improve the employee experience: payability, or a person’s ability to self-pay or cash-pay for care. The data shows that when employers build payability directly into plan design, they create patient-centered health plans. Those plans allow employers and employees to move to lower-cost plan designs with confidence, in a way that improves, rather than impairs, the employee experience.
Payability, Measured is the second in Paytient’s Payability Papers, a four-part series examining how the out-of-pocket payment experience shapes health plan performance and the employee experience. Surveying 2,024 full-time, employer-insured workers, the study finds that two-thirds of employees prefer a $2,000 cost spread over six months to a $1,000 copay paid in full upfront to receive care. Greenwald’s research is the first of its kind to reveal this behavioral preference in how consumers pay for healthcare, and it highlights real opportunities for employers and insurers to design health plans around how people prefer to pay for care.
These findings that have direct implications for employers stand out:
Employers who solve for payability gain on both sides of the ledger. When employees have a reliable way to pay out-of-pocket costs over time, more than 80% say they’d view their employer as more innovative and more attuned to their financial realities. The plan efficiency case is equally strong: employees who can pay for care seek it sooner, reducing the severity of deferred claims.
Employers have less visibility into benefits usage and employee experience than they realize. Sixty-one percent of employees have paid for healthcare or medication entirely in cash without filing a claim — a workaround almost completely invisible to employers. Only 29% believe their employer fully understands what paying for care out of pocket is like.
“Insurance was built to protect people from the financial risk of rare, catastrophically expensive care. Over time, we’ve stretched it to cover nearly everything, which drives up premiums and makes the system harder to navigate. This research shows that people want to pay for healthcare the way they pay for almost everything else in their lives: upfront, in-full with a clear cash price or predictably, over time to fit their household budget. A smarter plan design pairs lower-cost coverage for rare, high-cost care with the payment tools “Paytients” have told us they want for everything else. Employers already use payroll to collect premiums (and smooth the payment of taxes) over the life of employment. Using payroll to smooth out-of-pocket costs is the plan design opportunity hiding in plain sight, and it can help employers save substantially on plan costs,” says Joe Gabler, Chief Operating Officer of Paytient.
The findings support that when employees have a reliable, structured way to pay for out-of-pocket costs over time, plan design can become more efficient without becoming less supportive — and that changes the calculus on deductible architecture, total cost of care, and the actual value delivered by healthcare benefit.
“What stands out in this data is how universal the preference for payability in healthcare is. It holds across income levels, from workers earning under $50,000 to those earning over $100,000.
“This isn’t a low-income affordability story. It’s a structural preference that cuts across the entire workforce, and can be a universal strategic advantage for employers,” says Lisa Weber, Chief Research Officer and Head of Healthcare Insights at Greenwald Research.
Payability, Measured is available for download here. For more information, visit www.paytient.com. If you’re attending HLTH 2026, stop by Paytient’s booth (#2824).
About Paytient
Paytient is the leader in innovative healthcare payment solutions. Our Healthcare Payability Platform has put over $50 billion of purchasing power into the hands of 26 million individuals across employer, ACA and Medicare plans. In doing so, Paytient is helping shape more accessible, equitable, and lower-cost health plans across commercial, individual, and regulated healthcare markets. To learn more, visit www.paytient.com and join us on LinkedIn.
Media Contact
Kristin Laughlin
klaughlin@paytient.com
View original content:https://www.prnewswire.com/news-releases/paytient-greenwald-study-finds-61-of-insured-workers-have-paid-for-healthcare-entirely-in-cash-without-filing-a-claim-302938514.html
SOURCE Paytient Technologies


Telecom Argentina S.A. announces consolidated results for the nine-month period (“9M26”) and third quarter of fiscal year 2026 (“3Q26”)(2)
TERAGO Reports Third Quarter and Nine Months Ended 2026 Financial Results
Paytient-Greenwald Study Finds 61% of Insured Workers Have Paid for Healthcare Entirely in Cash Without Filing a Claim

Send Rakhi to UK swiftly with UK Gifts Portal

Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

Nullmax and Renesas Forge Strategic Partnership to Deliver Competitive ADAS Solutions for the Global Market

Why You Should Build on #NEAR – Co-founder Illia Polosukhin at CV Labs
Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

NEAR End of Year Town Hall 2021: The Open Web World, MetaBUILD 2 Hackathon and 2021 recap
Trending
-

 Technology4 days ago
Global Validation First: How CrossHub Is Building Trust to Scale Overseas
-

 Coin Market4 days ago
Vitalik ‘pivots’ ETH to store of value, crypto suffers after US midterms: Hodler’s Digest
-
 Coin Market4 days ago
tBTC bridge partially resumes as $120M Aave reserve remains frozen
-
 Technology3 days ago
InventHelp Inventor Develops New Finger Blood Pressure, Pulse, Oximetry Device (CLR-357)
-
 Technology3 days ago
EYKON launches Orkestra, a new software platform for modern utility operations
-
 Technology3 days ago
LG Innotek Shines Again in Vehicle Lighting with Third Consecutive CES Innovation Award
-
 Technology4 days ago
Talogy links leadership assessment to development, offering AI simulations for the first time
-
 Technology5 days ago
Club Offers for Travel Enthusiasts in Canada