
Technology
HONEYWELL REPORTS THIRD QUARTER RESULTS; UPDATES 2024 GUIDANCE

Published
2 years agoon
By
Sales of $9.7 Billion, Reported Sales Up 6%, Organic1 Sales Up 3%Operating Margin of 19.1% and Segment Margin1 of 23.6%, Above High End of Previous GuidanceEarnings Per Share of $2.16 and Adjusted Earnings Per Share1 of $2.58, Above High End of Previous GuidanceClosed $1.9 Billion Acquisition of CAES Systems and $1.8 Billion Acquisition of Air Products’ LNG BusinessAnnounced Intention to Spin Off Advanced Materials Business and Exit PPE Business
CHARLOTTE, N.C., Oct. 24, 2024 /PRNewswire/ — Honeywell (NASDAQ: HON) today announced results for the third quarter, including segment margin1 and adjusted earnings per share1 that exceeded the company’s guidance despite lower revenues in a challenging operating environment. The company also updated its full-year sales, segment margin2, adjusted earnings per share2,3, and cash flow guidance ranges.
The company reported third-quarter year-over-year sales growth of 6% and organic1 sales growth of 3%, highlighted by strength in defense and space, commercial aviation, and building solutions. Operating income decreased 4% and operating margin contracted 180 basis points to 19.1%, primarily as a result of an impairment related to classifying the personal protective equipment (PPE) business as assets held for sale. Segment profit1 increased 6% year over year led by strength in Aerospace Technologies and a full quarter from the Access Solutions acquisition, and segment margin1 held flat year over year at 23.6%, exceeding the high end of our guidance range by 30 basis points. Earnings per share for the third quarter was $2.16, down 5% year over year, and adjusted earnings per share1 was $2.58, up 8% year over year and above the high end of our guidance range. Operating cash flow was $2.0 billion and free cash flow1 was $1.7 billion, up 10% year over year.
In the past few months, Honeywell executed several additional actions to further simplify and improve its portfolio, including closing the acquisitions of Civitanavi, CAES Systems, and Air Products’ LNG business. Earlier this month, the company also announced its intention to spin off Advanced Materials into an independent company that will be a leading provider of sustainability-focused specialty chemicals and materials.
“Honeywell executed through a challenging environment in the third quarter, delivering segment margin1 and adjusted earnings per share1 above the high end of our guidance,” said Vimal Kapur, chairman and chief executive officer of Honeywell. “Our Accelerator operating system and culture of execution enabled us to grow segment profit1 by 6% in spite of transitory sales headwinds. We continue to see healthy order rates and sequential growth in our backlog, even excluding the impact of acquisitions closed in the quarter, giving us confidence in our ability to achieve our long-term targets. We also further advanced on our capital deployment strategy, deploying $3.1 billion to M&A, dividends, and high-return capex.”
Kapur continued, “We have made significant progress this year on the simplification and optimization of the Honeywell portfolio with the announcement of our plans to spin off Advanced Materials and exit our PPE business, as well as the closing of four strategic acquisitions. We are proud of the steps we have taken throughout 2024 to progress on our key priorities, but the work is not yet finished. I look forward to sharing more in the future as we further align our portfolio with the key megatrends of automation, the future of aviation, and energy transition.”
As a result of the company’s third-quarter performance and management’s outlook for the remainder of the year, including the impact of recently closed acquisitions, Honeywell updated its full-year sales, segment margin2, adjusted earnings per share2,3, and cash flow guidance1. Full-year sales are now expected to be $38.6 billion to $38.8 billion with organic1 sales growth of 3% to 4%. Segment margin2 is now expected to be in the range of 23.4% to 23.5% with segment margin2 flat to down 10 basis points year over year. Adjusted earnings per share2,3 is now expected to be in the range of $10.15 to $10.25, up 7% to 8% year over year. Operating cash flow is now expected to be in the range of $6.2 billion to $6.5 billion, with free cash flow1 of $5.1 billion to $5.4 billion. A summary of the company’s full-year guidance can be found in Table 1.
Third-Quarter Performance
Honeywell sales for the third quarter were up 6% year over year on a reported basis and 3% on an organic1 basis year over year. The third-quarter financial results can be found in Tables 2 and 3.
Aerospace Technologies sales for the third quarter increased 10% on an organic1 basis year over year, the ninth consecutive quarter of double-digit organic growth, led by continued strength in defense and space. Commercial original equipment grew double digits organically in the quarter on increased shipset deliveries, particularly in business and general aviation. Commercial aftermarket saw another quarter of strong growth as global flight activity rises. Defense and space sales increased 14% organically in the third quarter due to robust demand and supply chain improvements. Segment margin remained flat year over year at 27.7% as commercial excellence and productivity actions were offset by cost inflation and mix pressure within original equipment.
Industrial Automation sales for the third quarter decreased 5% on an organic1 basis year over year and were flat sequentially. Sales declines were led by volume softness in warehouse and workflow solutions and safety and sensing technologies. Process solutions delivered 2% organic growth in the third quarter and grew sequentially, as continued strength in aftermarket services and compressor controls was offset by softness in thermal solutions and smart energy. Productivity solutions and services delivered double-digit orders and organic sales1 growth when excluding the impact of a prior year license and settlement payment. Segment margin expanded 60 basis points to 20.3% as a result of productivity actions and commercial excellence, partially offset by cost inflation and volume deleverage.
Building Automation sales for the third quarter were up 3% on an organic1 basis year over year and up sequentially for the second consecutive quarter even excluding the first full quarter of access solutions ownership. Building solutions continues to lead the way, growing 8% organically on another quarter of double-digit growth in projects. Strength in solutions was partially offset by modest year over year declines in building products. Products delivered sequential growth in both sales and orders for the second consecutive quarter. Segment margin improved sequentially for the third consecutive quarter and expanded 30 basis points year over year to 25.9%, driven by the impact of access solutions and commercial excellence partially offset by cost inflation.
Energy and Sustainability Solutions grew 1% on an organic1 basis year over year in the third quarter. Advanced Materials increased 3% year over year due to further improvement in specialty chemicals and materials and continued growth in fluorine products. UOP sales declined 2% as growth in refining catalysts and aftermarket services was offset by softness in project timing. Orders were a bright spot in UOP, reaching a record $1 billion and up over 50% overall with strength in both core process technologies and sustainable technology solutions. Segment margin expanded 10 basis points to 24.5% as a result of commercial excellence net of inflation.
Conference Call Details
Honeywell will discuss its third-quarter results and full-year 2024 guidance during an investor conference call starting at 8:30 a.m. Eastern Time today. A live webcast of the investor call as well as related presentation materials will be available through the Investor Relations section of the company’s website (www.honeywell.com/investor). A replay of the webcast will be available for 30 days following the presentation.
TABLE 1: FULL-YEAR 2024 GUIDANCE2
Previous Guidance
Current Guidance
Sales
$39.1B – $39.7B
$38.6B – $38.8B
Organic1 Growth
5% – 6%
3% – 4%
Segment Margin
23.3% – 23.5%
23.4% – 23.5%
Expansion
Down 20 – Flat bps
Down 10 – Flat bps
Adjusted Earnings Per Share3
$10.05 – $10.25
$10.15 – $10.25
Adjusted Earnings Growth3
6% – 8%
7% – 8%
Operating Cash Flow
$6.6B – $7.0B
$6.2B – $6.5B
Free Cash Flow1
$5.5B – $5.9B
$5.1B – $5.4B
TABLE 2: SUMMARY OF HONEYWELL FINANCIAL RESULTS
3Q 2024
3Q 2023
Change
Sales
$9,728
$9,212
6 %
Organic1 Growth
3 %
Operating Income Margin
19.1 %
20.9 %
-180 bps
Segment Profit1
$2,296
$2,170
6 %
Segment Margin1
23.6 %
23.6 %
0 bps
Earnings Per Share
$2.16
$2.27
(5 %)
Adjusted Earnings Per Share1
$2.58
$2.38
8 %
Operating Cash Flow
$1,997
$1,809
10 %
Free Cash Flow1
$1,718
$1,560
10 %
TABLE 3: SUMMARY OF SEGMENT FINANCIAL RESULTS
AEROSPACE TECHNOLOGIES
3Q 2024
3Q 2023
Change
Sales
$3,912
$3,499
12 %
Organic1 Growth
10 %
Segment Profit
$1,082
$968
12 %
Segment Margin
27.7 %
27.7 %
0 bps
INDUSTRIAL AUTOMATION
Sales
$2,501
$2,630
(5 %)
Organic1 Growth
(5 %)
Segment Profit
$508
$519
(2 %)
Segment Margin
20.3 %
19.7 %
60 bps
BUILDING AUTOMATION
Sales
$1,745
$1,530
14 %
Organic1 Growth
3 %
Segment Profit
$452
$392
15 %
Segment Margin
25.9 %
25.6 %
30 bps
ENERGY AND SUSTAINABILITY SOLUTIONS
Sales
$1,563
$1,551
1 %
Organic1 Growth
1 %
Segment Profit
$383
$378
1 %
Segment Margin
24.5 %
24.4 %
10 bps
1
See additional information at the end of this release regarding non-GAAP financial measures.
2
Segment margin and adjusted EPS are non-GAAP financial measures. Management cannot reliably predict or estimate, without unreasonable effort, the impact and timing on future operating results arising from items excluded from segment margin or adjusted EPS. We therefore, do not present a guidance range, or a reconciliation to, the nearest GAAP financial measures of operating margin or EPS.
3
Adjusted EPS and adjusted EPS V% guidance excludes items identified in the non-GAAP reconciliation of adjusted EPS at the end of this release, and any potential future one-time items that we cannot reliably predict or estimate such as pension mark-to-market.
During the third quarter of 2024, Honeywell concluded the assets and liabilities of the personal protective equipment business (part of the Sensing and Safety Technologies business unit within the Industrial Automation segment) met the held for sale criteria as of September 30, 2024; therefore, the associated assets and liabilities of the business have been presented as held for sale in the Consolidated Balance Sheet as of September 30, 2024. The company recognized a valuation allowance of $125 million in the third quarter of 2024 to write down the disposal group to fair value, less costs to sell, as well as recorded an impairment charge of $37 million (after tax) on indefinite-lived intangible assets.
Honeywell is an integrated operating company serving a broad range of industries and geographies around the world. Our business is aligned with three powerful megatrends – automation, the future of aviation, and energy transition – underpinned by our Honeywell Accelerator operating system and Honeywell Connected Enterprise integrated software platform. As a trusted partner, we help organizations solve the world’s toughest, most complex challenges, providing actionable solutions and innovations that help make the world smarter, safer, and more sustainable. For more news and information on Honeywell, please visit www.honeywell.com/newsroom.
Honeywell uses our Investor Relations website, www.honeywell.com/investor, as a means of disclosing information which may be of interest or material to our investors and for complying with disclosure obligations under Regulation FD. Accordingly, investors should monitor our Investor Relations website, in addition to following our press releases, SEC filings, public conference calls, webcasts, and social media.
We describe many of the trends and other factors that drive our business and future results in this release. Such discussions contain forward-looking statements within the meaning of Section 21E of the Securities Exchange Act of 1934, as amended (the Exchange Act). Forward-looking statements are those that address activities, events, or developments that management intends, expects, projects, believes, or anticipates will or may occur in the future and include statements related to the proposed spin-off of the Company’s Advanced Materials business into a stand-alone, publicly traded company. They are based on management’s assumptions and assessments in light of past experience and trends, current economic and industry conditions, expected future developments, and other relevant factors, many of which are difficult to predict and outside of our control. They are not guarantees of future performance, and actual results, developments, and business decisions may differ significantly from those envisaged by our forward-looking statements. We do not undertake to update or revise any of our forward-looking statements, except as required by applicable securities law. Our forward-looking statements are also subject to material risks and uncertainties, including ongoing macroeconomic and geopolitical risks, such as lower GDP growth or recession, supply chain disruptions, capital markets volatility, inflation, and certain regional conflicts, that can affect our performance in both the near- and long-term. In addition, no assurance can be given that any plan, initiative, projection, goal, commitment, expectation, or prospect set forth in this release can or will be achieved. These forward-looking statements should be considered in light of the information included in this release, our Form 10-K, and our other filings with the Securities and Exchange Commission. Any forward-looking plans described herein are not final and may be modified or abandoned at any time.
This release contains financial measures presented on a non-GAAP basis. Honeywell’s non-GAAP financial measures used in this release are as follows:
Segment profit, on an overall Honeywell basis;Segment profit margin, on an overall Honeywell basis;Organic sales growth;Free cash flow; andAdjusted earnings per share.
Management believes that, when considered together with reported amounts, these measures are useful to investors and management in understanding our ongoing operations and in the analysis of ongoing operating trends. These measures should be considered in addition to, and not as replacements for, the most comparable GAAP measure. Certain measures presented on a non-GAAP basis represent the impact of adjusting items net of tax. The tax-effect for adjusting items is determined individually and on a case-by-case basis. Refer to the Appendix attached to this release for reconciliations of non-GAAP financial measures to the most directly comparable GAAP measures.
Honeywell International Inc.
Consolidated Statement of Operations (Unaudited)
(Dollars in millions, except per share amounts)
Three Months Ended
September 30,
Nine Months Ended
September 30,
2024
2023
2024
2023
Product sales
$ 6,590
$ 6,294
$ 19,330
$ 19,045
Service sales
3,138
2,918
9,080
8,177
Net sales
9,728
9,212
28,410
27,222
Costs, expenses and other
Cost of products sold1
4,166
4,090
12,448
12,291
Cost of services sold1
1,813
1,580
4,970
4,503
Total Cost of products and services sold
5,979
5,670
17,418
16,794
Research and development expenses
368
364
1,110
1,096
Selling, general and administrative expenses1
1,398
1,252
4,061
3,831
Impairment of assets held for sale
125
—
125
—
Other (income) expense
(263)
(247)
(740)
(715)
Interest and other financial charges
297
206
767
563
Total costs, expenses and other
7,904
7,245
22,741
21,569
Income before taxes
1,824
1,967
5,669
5,653
Tax expense
409
452
1,219
1,229
Net income
1,415
1,515
4,450
4,424
Less: Net income attributable to noncontrolling interest
2
1
30
29
Net income attributable to Honeywell
$ 1,413
$ 1,514
$ 4,420
$ 4,395
Earnings per share of common stock – basic
$ 2.17
$ 2.29
$ 6.79
$ 6.61
Earnings per share of common stock – assuming dilution
$ 2.16
$ 2.27
$ 6.75
$ 6.56
Weighted average number of shares outstanding – basic
650.4
662.4
651.0
665.2
Weighted average number of shares outstanding – assuming dilution
654.1
667.0
655.2
670.4
1
Cost of products and services sold and Selling, general and administrative expenses include amounts for repositioning and other charges, the service cost component of pension and other postretirement (income) expense, and stock compensation expense.
Honeywell International Inc.
Segment Data (Unaudited)
(Dollars in millions)
Three Months Ended
September 30,
Nine Months Ended
September 30,
Net Sales
2024
2023
2024
2023
Aerospace Technologies
$ 3,912
$ 3,499
$ 11,472
$ 9,951
Industrial Automation
2,501
2,630
7,485
8,160
Building Automation
1,745
1,530
4,742
4,527
Energy and Sustainability Solutions
1,563
1,551
4,692
4,579
Corporate and All Other
7
2
19
5
Total
$ 9,728
$ 9,212
$ 28,410
$ 27,222
Reconciliation of Segment Profit to Income Before Taxes
Three Months Ended
September 30,
Nine Months Ended
September 30,
Segment Profit
2024
2023
2024
2023
Aerospace Technologies
$ 1,082
$ 968
$ 3,177
$ 2,729
Industrial Automation
508
519
1,459
1,649
Building Automation
452
392
1,199
1,164
Energy and Sustainability Solutions
383
378
1,091
1,043
Corporate and All Other
(129)
(87)
(337)
(287)
Total segment profit
2,296
2,170
6,589
6,298
Interest and other financial charges
(297)
(206)
(767)
(563)
Interest income
110
89
325
241
Amortization of acquisition-related intangibles
(120)
(87)
(275)
(216)
Impairment of assets held for sale
(125)
—
(125)
—
Stock compensation expense1
(45)
(39)
(153)
(148)
Pension ongoing income2
145
131
430
391
Other postretirement income2
3
6
13
19
Repositioning and other charges3,4
(52)
(88)
(189)
(331)
Other expense5
(91)
(9)
(179)
(38)
Income before taxes
$ 1,824
$ 1,967
$ 5,669
$ 5,653
1
Amounts included in Selling, general and administrative expenses.
2
Amounts included in Cost of products and services sold (service cost component), Selling, general and administrative expenses (service cost component), Research and development expenses (service cost component), and Other (income) expense (non-service cost component).
3
Amounts included in Cost of products and services sold, Selling, general and administrative expenses, and Other (income) expense.
4
Includes repositioning, asbestos, and environmental expenses.
5
Amounts include the other components of Other (income) expense not included within other categories in this reconciliation. Equity income of affiliated companies is included in segment profit.
Honeywell International Inc.
Consolidated Balance Sheet (Unaudited)
(Dollars in millions)
September 30, 2024
December 31, 2023
ASSETS
Current assets
Cash and cash equivalents
$ 10,644
$ 7,925
Short-term investments
275
170
Accounts receivable, less allowances of $319 and $323, respectively
7,884
7,530
Inventories
6,338
6,178
Assets held for sale
1,518
—
Other current assets
1,505
1,699
Total current assets
28,164
23,502
Investments and long-term receivables
1,463
939
Property, plant and equipment—net
5,822
5,660
Goodwill
21,270
18,049
Other intangible assets—net
5,749
3,231
Insurance recoveries for asbestos-related liabilities
160
170
Deferred income taxes
374
392
Other assets
10,490
9,582
Total assets
$ 73,492
$ 61,525
LIABILITIES
Current liabilities
Accounts payable
$ 6,640
$ 6,849
Commercial paper and other short-term borrowings
3,135
2,085
Current maturities of long-term debt
1,760
1,796
Accrued liabilities
7,566
7,809
Liabilities held for sale
433
—
Total current liabilities
19,534
18,539
Long-term debt
25,934
16,562
Deferred income taxes
2,077
2,094
Postretirement benefit obligations other than pensions
122
134
Asbestos-related liabilities
1,422
1,490
Other liabilities
6,422
6,265
Redeemable noncontrolling interest
7
7
Shareowners’ equity
17,974
16,434
Total liabilities, redeemable noncontrolling interest and shareowners’ equity
$ 73,492
$ 61,525
Honeywell International Inc.
Consolidated Statement of Cash Flows (Unaudited)
(Dollars in millions)
Three Months Ended
September 30,
Nine Months Ended
September 30,
2024
2023
2024
2023
Cash flows from operating activities
Net income
$ 1,415
$ 1,515
$ 4,450
$ 4,424
Less: Net income attributable to noncontrolling interest
2
1
30
29
Net income attributable to Honeywell
1,413
1,514
4,420
4,395
Adjustments to reconcile net income attributable to Honeywell to net cash provided by
(used for) operating activities
Depreciation
171
166
500
493
Amortization
186
142
457
382
Impairment of assets held for sale
125
—
125
—
Repositioning and other charges
52
88
189
331
Net payments for repositioning and other charges
(118)
(128)
(329)
(323)
NARCO Buyout payment
—
—
—
(1,325)
Pension and other postretirement income
(148)
(137)
(443)
(410)
Pension and other postretirement benefit payments
(10)
(2)
(25)
(25)
Stock compensation expense
45
39
153
148
Deferred income taxes
(10)
(28)
(46)
168
Other
(58)
89
(641)
(554)
Changes in assets and liabilities, net of the effects of acquisitions and divestitures
Accounts receivable
(69)
161
(218)
(344)
Inventories
(156)
(110)
(233)
(448)
Other current assets
(32)
(67)
195
141
Accounts payable
281
(18)
(142)
96
Accrued liabilities
325
100
(146)
(340)
Net cash provided by operating activities
1,997
1,809
3,816
2,385
Cash flows from investing activities
Capital expenditures
(279)
(249)
(771)
(675)
Proceeds from disposals of property, plant and equipment
—
8
—
21
Increase in investments
(230)
(175)
(698)
(404)
Decrease in investments
172
176
564
808
Receipts (payments) from settlements of derivative contracts
(326)
250
(250)
212
Cash paid for acquisitions, net of cash acquired
(2,134)
(55)
(7,047)
(716)
Net cash used for investing activities
(2,797)
(45)
(8,202)
(754)
Cash flows from financing activities
Proceeds from issuance of commercial paper and other short-term borrowings
2,523
2,727
9,516
10,727
Payments of commercial paper and other short-term borrowings
(3,988)
(3,554)
(8,477)
(11,484)
Proceeds from issuance of common stock
40
36
349
151
Proceeds from issuance of long-term debt
4,697
19
10,407
2,985
Payments of long-term debt
(776)
(26)
(1,381)
(1,410)
Repurchases of common stock
—
(1,011)
(1,200)
(2,187)
Cash dividends paid
(715)
(728)
(2,161)
(2,144)
Other
(21)
(27)
5
(65)
Net cash provided by (used for) financing activities
1,760
(2,564)
7,058
(3,427)
Effect of foreign exchange rate changes on cash and cash equivalents
108
(56)
47
(61)
Net increase (decrease) in cash and cash equivalents
1,068
(856)
2,719
(1,857)
Cash and cash equivalents at beginning of period
9,576
8,626
7,925
9,627
Cash and cash equivalents at end of period
$ 10,644
$ 7,770
$ 10,644
$ 7,770
Appendix
Non-GAAP Financial Measures
The following information provides definitions and reconciliations of certain non-GAAP financial measures presented in this press release to which this reconciliation is attached to the most directly comparable financial measures calculated and presented in accordance with generally accepted accounting principles (GAAP).
Management believes that, when considered together with reported amounts, these measures are useful to investors and management in understanding our ongoing operations and in the analysis of ongoing operating trends. Management believes the change to adjust for amortization of acquisition-related intangibles and certain acquisition- and divestiture-related costs provides investors with a more meaningful measure of its performance period to period, aligns the measure to how management will evaluate performance internally, and makes it easier for investors to compare our performance to peers. These measures should be considered in addition to, and not as replacements for, the most comparable GAAP measure. Certain measures presented on a non-GAAP basis represent the impact of adjusting items net of tax. The tax-effect for adjusting items is determined individually and on a case-by-case basis. Other companies may calculate these non-GAAP measures differently, limiting the usefulness of these measures for comparative purposes.
Management does not consider these non-GAAP measures in isolation or as an alternative to financial measures determined in accordance with GAAP. The principal limitations of these non-GAAP financial measures are that they exclude significant expenses and income that are required by GAAP to be recognized in the consolidated financial statements. In addition, they are subject to inherent limitations as they reflect the exercise of judgments by management about which expenses and income are excluded or included in determining these non-GAAP financial measures. Investors are urged to review the reconciliation of the non-GAAP financial measures to the comparable GAAP financial measures and not to rely on any single financial measure to evaluate Honeywell’s business.
Honeywell International Inc.
Reconciliation of Organic Sales Percent Change
(Unaudited)
Three Months Ended
September 30, 2024
Honeywell
Reported sales percent change
6 %
Less: Foreign currency translation
— %
Less: Acquisitions, divestitures and other, net
3 %
Organic sales percent change
3 %
Aerospace Technologies
Reported sales percent change
12 %
Less: Foreign currency translation
— %
Less: Acquisitions, divestitures and other, net
2 %
Organic sales percent change
10 %
Industrial Automation
Reported sales percent change
(5) %
Less: Foreign currency translation
— %
Less: Acquisitions, divestitures and other, net
— %
Organic sales percent change
(5) %
Building Automation
Reported sales percent change
14 %
Less: Foreign currency translation
— %
Less: Acquisitions, divestitures and other, net
11 %
Organic sales percent change
3 %
Energy and Sustainability Solutions
Reported sales percent change
1 %
Less: Foreign currency translation
— %
Less: Acquisitions, divestitures and other, net
— %
Organic sales percent change
1 %
We define organic sales percentage as the year-over-year change in reported sales relative to the comparable period, excluding the impact on sales from foreign currency translation and acquisitions, net of divestitures, for the first 12 months following the transaction date. We believe this measure is useful to investors and management in understanding our ongoing operations and in analysis of ongoing operating trends.
A quantitative reconciliation of reported sales percent change to organic sales percent change has not been provided for forward-looking measures of organic sales percent change because management cannot reliably predict or estimate, without unreasonable effort, the fluctuations in global currency markets that impact foreign currency translation, nor is it reasonable for management to predict the timing, occurrence and impact of acquisition and divestiture transactions, all of which could significantly impact our reported sales percent change.
Honeywell International Inc.
Reconciliation of Operating Income to Segment Profit, Calculation of Operating Income and Segment Profit Margins
(Unaudited)
(Dollars in millions)
Three Months Ended September 30,
Twelve Months
Ended
December 31,
2024
2023
2023
Operating income
$ 1,858
$ 1,926
$ 7,084
Stock compensation expense1
45
39
202
Repositioning, Other2,3
69
100
952
Pension and other postretirement service costs3
16
17
66
Amortization of acquisition-related intangibles
120
87
292
Acquisition-related costs4
15
1
2
Indefinite-lived intangible asset impairment1
48
—
—
Impairment of assets held for sale
125
—
—
Segment profit
$ 2,296
$ 2,170
$ 8,598
Operating income
$ 1,858
$ 1,926
$ 7,084
÷ Net sales
$ 9,728
$ 9,212
$ 36,662
Operating income margin %
19.1 %
20.9 %
19.3 %
Segment profit
$ 2,296
$ 2,170
$ 8,598
÷ Net sales
$ 9,728
$ 9,212
$ 36,662
Segment profit margin %
23.6 %
23.6 %
23.5 %
1
Included in Selling, general and administrative expenses.
2
Includes repositioning, asbestos, environmental expenses, equity income adjustment, and other charges.
3
Included in Cost of products and services sold and Selling, general and administrative expenses.
4
Includes acquisition-related fair value adjustments to inventory.
We define operating income as net sales less total cost of products and services sold, research and development expenses, impairment of assets held for sale, and selling, general and administrative expenses. We define segment profit, on an overall Honeywell basis, as operating income, excluding stock compensation expense, pension and other postretirement service costs, amortization of acquisition-related intangibles, certain acquisition- and divestiture-related costs and impairments, and repositioning and other charges. We define segment profit margin, on an overall Honeywell basis, as segment profit divided by net sales. We believe these measures are useful to investors and management in understanding our ongoing operations and in analysis of ongoing operating trends.
A quantitative reconciliation of operating income to segment profit, on an overall Honeywell basis, has not been provided for all forward-looking measures of segment profit and segment profit margin included herein. Management cannot reliably predict or estimate, without unreasonable effort, the impact and timing on future operating results arising from items excluded from segment profit, particularly pension mark-to-market expense as it is dependent on macroeconomic factors, such as interest rates and the return generated on invested pension plan assets. The information that is unavailable to provide a quantitative reconciliation could have a significant impact on our reported financial results. To the extent quantitative information becomes available without unreasonable effort in the future, and closer to the period to which the forward-looking measures pertain, a reconciliation of operating income to segment profit will be included within future filings.
Acquisition amortization and acquisition- and divestiture-related costs are significantly impacted by the timing, size, and number of acquisitions or divestitures we complete and are not on a predictable cycle and we make no comment as to when or whether any future acquisitions or divestitures may occur. We believe excluding these costs provides investors with a more meaningful comparison of operating performance over time and with both acquisitive and other peer companies.
Honeywell International Inc.
Reconciliation of Earnings per Share to Adjusted Earnings per Share
(Unaudited)
Three Months Ended September 30,
Twelve Months Ended December 31,
2024
2023
2023
2024(E)
Earnings per share of common stock – diluted1
$ 2.16
$ 2.27
$ 8.47
$9.23 – $9.33
Pension mark-to-market expense2
—
—
0.19
No Forecast
Amortization of acquisition-related intangibles3
0.14
0.10
0.35
0.50
Acquisition-related costs4
0.03
0.01
0.01
0.10
Divestiture-related costs5
—
—
—
0.04
Russian-related charges6
—
—
—
0.03
Net expense related to the NARCO Buyout and HWI Sale7
—
—
0.01
—
Adjustment to estimated future Bendix liability8
—
—
0.49
—
Indefinite-lived intangible asset impairment9
0.06
—
—
0.06
Impairment of assets held for sale10
0.19
—
—
0.19
Adjusted earnings per share of common stock – diluted
$ 2.58
$ 2.38
$ 9.52
$10.15 – $10.25
1
For the three months ended September 30, 2024, and 2023, adjusted earnings per share utilizes weighted average shares of approximately 654.1 million and 667.0 million, respectively. For the twelve months ended December 31, 2023, adjusted earnings per share utilizes weighted average shares of approximately 668.2 million. For the twelve months ended December 31, 2024, expected earnings per share utilizes weighted average shares of approximately 655 million.
2
Pension mark-to-market expense uses a blended tax rate of 18%, net of tax benefit of $27 million, for 2023.
3
For the three months ended September 30, 2024, acquisition-related intangibles amortization includes approximately $95 million, net of tax benefit of approximately $25 million. For the three months ended September 30, 2023, and twelve months ended December 31, 2023, acquisition-related intangibles amortization includes $67 million and $231 million, net of tax benefit of approximately $20 million and $61 million, respectively. For the twelve months ended December 31, 2024, expected acquisition-related intangibles amortization includes approximately $330 million, net of tax benefit of approximately $85 million.
4
For the three months ended September 30, 2024, the adjustment for acquisition-related costs, which is principally comprised of third-party transaction and integration costs and acquisition-related fair value adjustments to inventory, is approximately $20 million, net of tax benefit of approximately $5 million. For the three months ended September 30, 2023, and twelve months ended December 31, 2023, the adjustment for acquisition-related costs, which is principally comprised of third-party transaction and integration costs and acquisition-related fair value adjustments to inventory, is approximately $4 million and $7 million, net of tax benefit of approximately $2 million and $2 million, respectively. For the twelve months ended December 31, 2024, the expected adjustment for acquisition-related costs, which is principally comprised of third-party transaction and integration costs and acquisition-related fair value adjustments to inventory, is approximately $65 million, net of tax benefit of approximately $15 million.
5
For the twelve months ended December 31, 2024, the expected adjustment for divestiture-related costs, which is principally comprised of third-party transaction costs, is approximately $25 million, net of tax benefit of approximately $5 million.
6
For the twelve months ended December 31, 2023, the adjustment was a benefit $3 million, without tax expense. For the twelve months ended December 31, 2024, the expected adjustment is a $17 million expense, without tax benefit, due to the settlement of a contractual dispute with a Russian entity associated with the Company’s suspension and wind down activities in Russia.
7
For the twelve months ended December 31, 2023, the adjustment was $8 million, net of tax benefit of $3 million, due to the net expense related to the NARCO Buyout and HWI Sale.
8
Bendix Friction Materials (“Bendix”) is a business no longer owned by the Company. In 2023, the Company changed its valuation methodology for calculating legacy Bendix liabilities. For the twelve months ended December 31, 2023, the adjustment was $330 million, net of tax benefit of $104 million (or $434 million pre-tax) due to a change in the estimated liability for resolution of asserted (claims filed as of the financial statement date) and unasserted Bendix-related asbestos claims. The Company experienced fluctuations in average resolution values year-over-year in each of the past five years with no well-established trends in either direction. In 2023, the Company observed two consecutive years of increasing average resolution values (2023 and 2022), with more volatility in the earlier years of the five-year period (2019 through 2021). Based on these observations, the Company, during its annual review in the fourth quarter of 2023, reevaluated its valuation methodology and elected to give more weight to the two most recent years by shortening the look-back period from five years to two years (2023 and 2022). The Company believes that the average resolution values in the last two consecutive years are likely more representative of expected resolution values in future periods. The $434 million pre-tax amount was attributable primarily to shortening the look-back period to the two most recent years, and to a lesser extent to increasing expected resolution values for a subset of asserted claims to adjust for higher claim values in that subset than in the modelled two-year data set. It is not possible to predict whether such resolution values will increase, decrease, or stabilize in the future, given recent litigation trends within the tort system and the inherent uncertainty in predicting the outcome of such trends. The Company will continue to monitor Bendix claim resolution values and other trends within the tort system to assess the appropriate look-back period for determining average resolution values going forward.
9
For the three months ended September 30, 2024, the impairment charge of indefinite-lived intangible assets associated with the personal protective equipment business was $37 million, net of tax benefit of $11 million. For the twelve months ended December 31, 2024, the expected impairment charge of indefinite-lived intangible assets associated with the personal protective equipment business is $37 million, net of tax benefit of $11 million.
10
For the three months ended September 30, 2024, the impairment charge of assets held for sale was $125 million, without tax benefit. For the twelve months ended December 31, 2024, the expected impairment charge of assets held for sale is $125 million, with no tax benefit.
We define adjusted earnings per share as diluted earnings per share adjusted to exclude various charges as listed above. We believe adjusted earnings per share is a measure that is useful to investors and management in understanding our ongoing operations and in analysis of ongoing operating trends. For forward-looking information, management cannot reliably predict or estimate, without unreasonable effort, the pension mark-to-market expense as it is dependent on macroeconomic factors, such as interest rates and the return generated on invested pension plan assets. We therefore do not include an estimate for the pension mark-to-market expense. Based on economic and industry conditions, future developments, and other relevant factors, these assumptions are subject to change.
Acquisition amortization and acquisition- and divestiture-related costs are significantly impacted by the timing, size, and number of acquisitions or divestitures we complete and are not on a predictable cycle and we make no comment as to when or whether any future acquisitions or divestitures may occur. We believe excluding these costs provides investors with a more meaningful comparison of operating performance over time and with both acquisitive and other peer companies.
Honeywell International Inc.
Reconciliation of Cash Provided by Operating Activities to Free Cash Flow
(Unaudited)
(Dollars in millions)
Three Months Ended
September 30, 2024
Three Months Ended
September 30, 2023
Cash provided by operating activities
$ 1,997
$ 1,809
Capital expenditures
(279)
(249)
Free cash flow
$ 1,718
$ 1,560
We define free cash flow as cash provided by operating activities less cash for capital expenditures.
We believe that free cash flow is a non-GAAP measure that is useful to investors and management as a measure of cash generated by operations that will be used to repay scheduled debt maturities and can be used to invest in future growth through new business development activities or acquisitions, pay dividends, repurchase stock, or repay debt obligations prior to their maturities. This measure can also be used to evaluate our ability to generate cash flow from operations and the impact that this cash flow has on our liquidity.
Honeywell International Inc.
Reconciliation of Expected Cash Provided by Operating Activities to Expected Free Cash Flow
(Unaudited)
Twelve Months Ended
December 31, 2024(E) ($B)
Cash provided by operating activities
~$6.2 – $6.5
Capital expenditures
~(1.1)
Free cash flow
~$5.1 – $5.4
We define free cash flow as cash provided by operating activities less cash for capital expenditures.
We believe that free cash flow is a non-GAAP measure that is useful to investors and management as a measure of cash generated by operations that will be used to repay scheduled debt maturities and can be used to invest in future growth through new business development activities or acquisitions, pay dividends, repurchase stock, or repay debt obligations prior to their maturities. This measure can also be used to evaluate our ability to generate cash flow from operations and the impact that this cash flow has on our liquidity.
Contacts:
Media
Investor Relations
Stacey Jones
Sean Meakim
(980) 378-6258
(704) 627-6200
View original content to download multimedia:https://www.prnewswire.com/news-releases/honeywell-reports-third-quarter-results-updates-2024-guidance-302285281.html
SOURCE Honeywell

You may like
Technology
Dental 3D Printing Market worth $10.08 billion by 2031 – Exclusive Report by MarketsandMarkets™
Published
20 minutes agoon
November 2, 2026By
DELRAY BEACH, Fla., Nov. 2, 2026 /PRNewswire/ — According to MarketsandMarkets™, the Dental 3D Printing Market is projected to reach USD 10.08 billion by 2031 from USD 4.35 billion in 2026, at a CAGR of 18.3% during the forecast period.
Browse 250 market data Tables and 60 Figures spread through 300 Pages and in-depth TOC on ‘Dental 3D Printing Market- Global Forecast to 2031’
Dental 3D Printing Market Size & Forecast:
Market Size Available for Years: 2026–20312026 Market Size: USD 4.35 billion2031 Projected Market Size: USD 10.08 billionCAGR (2026–2031): 18.3%
Dental 3D Printing Market Trends & Insights:
North America held the largest share in 2025.By product & service, the materials segment is expected to register the highest CAGR of 21.3% during the forecast period.By technology, the VAT photopolymerization segment accounted for the largest share of 61.5% in 2025.
Download PDF Brochure: https://www.marketsandmarkets.com/pdfdownloadNew.asp?id=258228239
The dental 3D printing market is driven by several factors. One key driver is rising oral health awareness, combined with a growing global population, which increases demand for dental services. This creates a favorable environment for innovative solutions like 3D printing. Additionally, advances in 3D printing hardware, software, and materials improve accuracy, speed, and affordability, making the technology more accessible and appealing for dental applications. However, certain challenges could hinder market growth. These include regulatory hurdles, high upfront costs, operational expenses, and a shortage of skilled workers.
By technology, the VAT photopolymerization segment accounted for the largest share of the dental 3D printing market during the forecast period.
The dental 3D printing market is segmented by technology into VAT photopolymerization, fused deposition modeling, selective laser sintering, PolyJet printing, and other technologies. VAT photopolymerization holds the largest share of the dental 3D printing market due to its precision, versatility with various materials, and broad applicability to dental procedures. Technologies such as stereolithography (SLA) and digital light processing (DLP) produce high-resolution prints with a smooth finish, making them particularly suitable for crowns, bridges, surgical guides, occlusal splints, and aligners. Their compatibility with biocompatible resins allows for both temporary and permanent restorations. Dental labs rely on this technology because it can produce many custom pieces at once, saving time and resources. It is also gaining popularity among small clinics and dental support organizations (DSOs), as many new systems are affordable, compact, and user-friendly. Additionally, 3D printing generates less waste than conventional milling or handwork and continues to evolve with advances in resin chemistry and printer technology.
By end user, the dental laboratories segment accounted for the largest share of the dental 3D printing market during the forecast period.
The dental 3D printing market can be divided by end user into three main categories: dental laboratories, dental hospitals & clinics, and dental academic & research institutions. Dental laboratories represent the largest segment of the dental 3D printing industry, driven by the increasing demand for advanced technologies in dental practices, cosmetic treatments, and high-quality products. These labs manufacture a variety of dental products—such as prosthetics, crowns, dentures, veneers, and night guards—using 3D printing because it offers greater accuracy, speed, and affordability. Larger laboratory chains are adopting this technology because of their purchasing power, and outsourcing fabrication to these labs is increasingly common, further increasing demand. Digitizing processes through 3D printing leads to significant time and cost savings, as well as greater precision in producing dental items.
Inquiry Before Buying: https://www.marketsandmarkets.com/Enquiry_Before_BuyingNew.asp?id=258228239
North America dominates the dental 3D printing market.
The global dental 3D printing market is divided into six main regions: North America, Europe, Asia Pacific, Latin America, the Middle East & Africa, and the GCC countries.
North America leads the dental 3D printing market because of its well-developed healthcare system, rapid adoption of advanced dental technologies, and strong demand for cosmetic and restorative treatments. The region’s dominance in innovation and market share can be attributed to the fact that many companies in the dental 3D printing sector are based there. Additionally, high disposable incomes and a high standard of living in countries like the US and Canada further drive the demand for quality dental treatments. The ongoing digitalization of dental procedures also helps maintain North America’s position as a market leader.
Key Players
Leading players in the Dental 3D Printing companies include Stratasys (US and Israel), 3D Systems, Inc. (US), and Align Technology, Inc. (US).
Get 10% Free Customization on this Report: https://www.marketsandmarkets.com/requestCustomizationNew.asp?id=258228239
Investment Funding Context
Investment activity in the dental 3D printing ecosystem remains strong and is primarily concentrated on practice acquisitions, geographic expansion, technology adoption, and platform consolidation. Disclosed transactions in the dental 3D printing market indicate a focus on proprietary printing technologies, advanced dental materials, geographic expansion, and integrating digital manufacturing capabilities. Venture funding has supported the expansion of specialized providers.
In October 2022, SprintRay secured more than USD 100 million in Series D funding led by SoftBank Vision Fund 2, with the proceeds intended to support expansion across Europe and the United States. Strategic acquisitions have also enabled companies to strengthen their technology portfolios. In January 2024, Align Technology completed its acquisition of Cubicure, reporting total purchase consideration of approximately USD 85.8 million, including the fair value of its pre-existing ownership interest. The acquisition was intended to expand Align’s capabilities in direct 3D printing, materials development, and manufacturing of customized orthodontic appliances. In September 2025, SprintRay acquired the EnvisionTEC/ETEC dental product portfolio, including patents, trademarks, inventory, and intellectual property relating to dental materials and printing technologies, strengthening its capabilities across laboratory and chairside applications. The announcement did not disclose the transaction value. In October 2025, LuxCreo also announced a strategic investment from Angelalign Technology to support joint development of next-generation 3D printing materials for clear aligners. The investment, whose value was not disclosed in the announcement, was directed toward material research and development, platform improvements, and expansion of the digital dentistry ecosystem, demonstrating strategic interest in direct printing technologies for orthodontic applications.
Revenue Shift Context
Revenue opportunities in the dental 3D printing market are broadening across equipment sales, recurring material purchases, and digital design and production services. Manufacturer disclosures indicate that printer installations can generate subsequent demand for consumables and support services as production volumes increase. Dental applications are also expanding beyond models used in conventional fabrication workflows toward directly printed restorations and appliances. For example, Stratasys launched its TrueDent-D resin in Europe in January 2025, extending its monolithic digital denture offering to additional markets and creating opportunities for printer deployment and repeat resin sales. The commercial contribution of newer applications is evident in 3D Systems’ fourth-quarter 2025 results, which reported strong double-digit sequential growth in its dental business, supported by a recovery in the aligner market and the launch of its denture manufacturing technology.
Digital services provide additional revenue channels alongside hardware and materials. SprintRay offers paid Cloud Design services and design subscriptions, while its Design Suite combines automated design, professional design assistance, and outsourced print-and-ship services. These offerings enable suppliers to participate in multiple stages of the dental production workflow and generate revenue through ongoing customer activity. These developments suggest that competitive differentiation increasingly depends on application breadth, material compatibility, workflow integration, and printer utilization, with revenue opportunities extending throughout the operating life of installed systems.
Mergers & Acquisitions
M&A activity in the dental 3D printing market is focused on strengthening printing capabilities, expanding material portfolios, and integrating digital production workflows. Selected transactions show acquisitions of complementary technologies to support dental laboratories and chairside applications. In September 2025, SprintRay acquired the EnvisionTEC/ETEC dental product portfolio, adding printing technologies, dental materials, and associated intellectual property to its offering. During the same month, Pac-Dent acquired Ackuretta Technologies, combining its Rodin dental printing resins with Ackuretta’s printers, post-processing equipment, and ALPHA AI CAM software. The transaction supports Pac-Dent’s development of an interoperable digital dentistry platform and expansion of customer support capabilities. Align Technology’s January 2024 acquisition of Cubicure strengthened its capabilities in polymer materials, direct 3D printing, and manufacturing customized orthodontic appliances. These transactions indicate consolidation is aimed at combining hardware, materials, and software expertise, broadening application coverage, and supporting scalable production of patient-specific dental products.
DENTAL 3D PRINTING MARKET: MERGERS & ACQUISITIONS, JANUARY 2023–SEPTEMBER 2026
Month & Year
Deal Type
Company 1
Company 2
Description
September 2025
Acquisition
SprintRay (US)
EnvisionTEC/ETEC dental product portfolio (US)
SprintRay acquired the EnvisionTEC/ETEC dental product portfolio, formerly part of Desktop Health, including patents, trademarks, inventory, and intellectual property relating to dental materials and 3D printing technologies. The acquisition strengthened its offerings across dental laboratory and chairside applications and included plans to continue resin supply and customer support.
September 2025
Acquisition
Pac-Dent (US
Ackuretta Technologies (Taiwan)
Pac-Dent acquired Ackuretta Technologies, combining its Rodin dental 3D printing resins and restorative materials with Ackuretta’s printing hardware, post-processing systems, and ALPHA AI CAM software. The acquisition supports integrated, open-system workflows for dental laboratories and clinics, alongside expanded training, service, and technical support.
January 2024
Acquisition
Align Technology (US)
Cubicure (Austria)
Align Technology completed its acquisition of Cubicure on January 2, 2024. Cubicure’s polymer printing technologies, materials expertise, and manufacturing capabilities were acquired to strengthen the Align Digital Platform and support the development and scaling of directly printed orthodontic devices.
Company Revenue Share Details
The dental 3D printing market is highly fragmented, with established manufacturers and specialized technology providers competing across dental 3D printers, photopolymer resins, printing software, post-processing systems, and integrated digital dentistry workflows. Key participants include Stratasys, 3D Systems, SprintRay, Formlabs, DWS S.r.l., Prodways Group, and Carbon.
Browse Adjacent Market: Medical Devices Market Research Reports &Consulting
See More Latest Medical Devices Reports:
3D Bioprinting Market by Component (3D bioprinters (Microextrusion, Inkjet, Laser), Bioinks, Software, Consumable), Material (Hydrogels, ECM), Application (Research (Regenerative Medicine, 3D cell Culture), Clinical (Skin, Bone)) – Global Forecast to 2029
Dental Implants and Prosthetics Market by Product [Dental Implants (Titanium, Zirconium), Dental Prosthetics (Bridges, Crowns, Dentures, Veneers, and Inlays & Onlays)], by End User (Dental Hospitals & Clinics, Dental Labs) – Global Forecast to 2031
About MarketsandMarkets™
MarketsandMarkets™ has been recognized as one of America’s Best Management Consulting Firms by Forbes, as per their recent report.
MarketsandMarkets™ is a blue ocean alternative in growth consulting and program management, leveraging a man-machine offering to drive supernormal growth for progressive organizations in the B2B space. With the widest lens on emerging technologies, we are proficient in co-creating supernormal growth for clients across the globe.
Today, 80% of Fortune 2000 companies rely on MarketsandMarkets, and 90 of the top 100 companies in each sector trust us to accelerate their revenue growth. With a global clientele of over 13,000 organizations, we help businesses thrive in a disruptive ecosystem.
The B2B economy is witnessing the emergence of $25 trillion in new revenue streams that are replacing existing ones within this decade. We work with clients on growth programs, helping them monetize this $25 trillion opportunity through our service lines – TAM Expansion, Go-to-Market (GTM) Strategy to Execution, Market Share Gain, Account Enablement, and Thought Leadership Marketing.
Built on the ‘GIVE Growth’ principle, we collaborate with several Forbes Global 2000 B2B companies to keep them future-ready. Our insights and strategies are powered by industry experts, cutting-edge AI, and our Market Intelligence Cloud, KnowledgeStore™, which integrates research and provides ecosystem-wide visibility into revenue shifts.
MarketsandMarkets™ SalesPlay is an AI-driven Revenue Intelligence Co-Pilot designed to help revenue teams prioritize the right accounts, identify critical changes early, and surface opportunities ahead of demand, so pipeline builds naturally and deals close with greater consistency.
To find out more, visit www.MarketsandMarkets™.com or follow us on Twitter, LinkedIn and Facebook.
Contact:
Mr. Rohan Salgarkar
MarketsandMarkets™ INC.
1615 South Congress Ave.
Suite 103, Delray Beach, FL 33445
USA: +1-888-600-6441
Email: sales@marketsandmarkets.com
Visit Our Website: https://www.marketsandmarkets.com/
Research Insight: https://www.marketsandmarkets.com/ResearchInsight/dental-3d-printing-market.asp
Content Source: https://www.marketsandmarkets.com/PressReleases/dental-3d-printing.asp
View original content to download multimedia:https://www.prnewswire.co.uk/news-releases/dental-3d-printing-market-worth-10-08-billion-by-2031—exclusive-report-by-marketsandmarkets-302926298.html
Technology
Tree Hut Unwraps Seven Festive Scents In Its New Limited-Edition Holiday Collection
Published
20 minutes agoon
November 2, 2026By
From Candy Cane to Frosted Plum, America’s No. 1 Body Scrub Brand Brings the Aromas of the Holidays to Self-Care
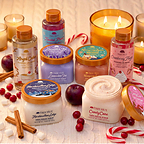
America’s No. 1 Body Scrub brand, Tree Hut, is introducing its limited-edition holiday collection in seven new seasonal scents that evoke the coziness of winter. The assortment ranges from sweet fragrances like Candy Cane and Cranberry Fluff to warm notes of Honeycrisp Spice, along with the return of vault favorite Marshmallow Lodge.The collection features a range of fan-favorite product forms, like the Shea Sugar Scrub, Foaming Gel Wash and more, bringing each fragrance to life through rich, sensorial textures and skin-loving formulas.Rounding out the line, seven gift sets make shopping this holiday season easy, with options for stocking stuffers or gifting. The collection is available nationally now at retailers like Target, Walmart, and Ulta Beauty, and online on Amazon.
COPPELL, Texas, Nov. 2, 2026 /PRNewswire/ — Cozy is calling! It’s officially sweater weather, and Tree Hut is making wintertime a little toastier. America’s No. 1 Body Scrub brand, Tree Hut, launches its holiday collection, filled with festive cheer and cabin-inspired charm to add to any routine. Featuring warm, nostalgic scents that range from sweet and creamy to bright and spiced, the collection makes every shower feel like a sensory escape. Consumers can fall in love with these limited-edition holiday favorites now at retailers like Target, Walmart, and Ulta Beauty, as well as online on Amazon.
As the season settles in, Tree Hut is serving up body care made for gifting, getting ready and warming up from the cold, wrapped in packaging inspired by Nordic folk art and the homey feeling of the holidays. From Shea Sugar Scrubs that exfoliate the skin to moisturizing Whipped Body Butters and gift-worthy sets, this assortment features rich aromas that embrace the season. Candy Cane, Angel Cake, Cranberry Fluff, Honeycrisp Spice, Frosted Plum, Lavender Ice and the return of vault scent, Marshmallow Lodge, transport consumers to a winter wonderland with every use. Crafted with Tree Hut’s skin-loving formulas featuring Shea Butter, real Sugar and nourishing oils, each offering brings a touch of indulgence to holiday self-care.
“Holiday body care should be just as fun to use as it is to give,” said Lindsey Scales, Vice President of Marketing at Tree Hut. “We wanted to create an assortment with scent notes that capture the essence of the holidays. The collection feels giftable, collectible and joyful, with irresistible textures and craveable fragrances that make consumers want to reach for it every day. It is a fresh take on the category that adds seasonal excitement to the shower.”
Tree Hut is bringing the spirit of the holidays to brand fans and winter lovers in a variety of new scents, including:
Candy Cane:Indulge in the sweet aroma of minty iced peppermint, cotton candy & vanilla beanAvailable in: Foaming Gel Wash (Tumbler), Foaming Gel Wash (Pump), Shea Sugar Scrub, Daily Moisturizing Scrub, Moisturizing Shave Oil, Whipped Body Butter, Hydraglow Body Lotion, Lip Butter and Mini Shea Sugar ScrubAngel Cake (Exclusively at Target):Soft notes of vanilla, cashmere and tonka bean make a sweet, whipped treat for an everything showerAvailable in: Foaming Gel Wash, Shea Sugar Scrub, Whipped Body Butter, Lip Butter and select minis; Foaming Gel Wash, Shea Sugar Scrub and Whipped Body ButterCranberry Fluff:A berry-sweet treat, made with cranberry, marshmallow and toasted sugarAvailable in: Foaming Gel Wash, Shea Sugar Scrub and Mini Shea Sugar ScrubHoneycrisp Spice (Exclusively at Walmart):A spiced, festive treat for your routine, made with apple, clove and cardamomAvailable in: Foaming Gel Wash and Shea Sugar ScrubFrosted Plum (Exclusively at Ulta):A rich mix of bright plum, juicy clementine and soft velvet muskAvailable in: Foaming Gel Wash and Shea Sugar ScrubLavender Ice (Exclusively at Target):A calm, magical winter reset, made with lavender, vanilla and coconut milkAvailable in Shea Sugar ScrubMarshmallow Lodge (Exclusively at Ulta):Bringing back a beloved vault scent with a comforting blend of bright bergamot, soft rice milk and sweet vanillaAvailable in Shea Sugar Scrub
To take the guesswork out of shopping, the brand’s offerings include sets that are ideal for treating family or friends. The assortment features: Candy Cane Lane Gift Set, Mini Fan Favorites Gift Set, Angel Cake Gift Set (Target Exclusive), Holly Jolly Bear Bath Regimen Trio (Target Exclusive), 6 Days of Holidays Gift Set (Target Exclusive), Very Vanilla Gift Set (Ulta Exclusive) and Frosted Fairytale Gift Set (Ulta Exclusive). From playful treats to sweet holiday favorites, there is something to make every holiday wish list a little merrier.
For more information on Tree Hut, please visit treehutshea.com and follow the brand on Instagram and TikTok.
About Tree Hut
Tree Hut believes that everyone deserves to take time in their day to feel good. The family-owned brand still manufactures out of Coppell, TX, and has spent over twenty years making high-quality skin and body care at an affordable price. The now global Tree Hut brand has grown to include body and shave collections, known for delicious scents, bright packaging, and premium ingredients. With an uplifting, inclusive approach to self-care, Tree Hut has built its brand largely via word of mouth, with customers and beauty influencers alike passionately sharing their favorite products and avidly anticipating seasonal launches.
View original content to download multimedia:https://www.prnewswire.com/news-releases/tree-hut-unwraps-seven-festive-scents-in-its-new-limited-edition-holiday-collection-302924121.html
SOURCE Tree Hut
Technology
Ruder Finn Promotes Tejas Totade to Global Chief Technology Officer and Chief Data & AI Officer
Published
20 minutes agoon
November 2, 2026By
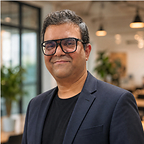
NEW YORK, Nov. 2, 2026 /PRNewswire/ — Ruder Finn, one of the world’s leading independent communications and integrated marketing agencies, today announced the promotion of Tejas Totade to Global Chief Technology Officer and Chief Data & AI Officer, establishing a global leadership role that brings the agency’s technology, data and artificial intelligence capabilities under a shared strategic vision. Tejas has built a strong digital, analytics and engineering team with several dozen specialists in hubs across India, the Philippines, and New York.
The move reflects the growing connection of these disciplines across both Ruder Finn’s business and client work. In his expanded role, Totade will widen access to tools and training in every region and build the architecture that supports the agency’s AI capabilities end to end. The global mandate formalizes work he has led across markets over the past year, including AI strategy and adoption programs in India and the U.K.
“The greatest opportunity comes when we work together choosing the right technology, grounding it in data, and applying AI to solve a real business problem,” said Totade. “This role gives us an opportunity to create that shared vision globally and help our teams and clients translate the enormous potential of AI into measurable value.”
“Ruder Finn has always believed that technology should expand what communicators are able to accomplish, and Tejas has been central to building that capability within our agency,” said Kathy Bloomgarden, CEO of Ruder Finn. “As technology, data and AI become increasingly interconnected, we’re committed to bringing the most cutting edge AI capabilities to clients, under the leadership of Tejas.”
Ruder Finn has also appointed Nick Driver as Managing Director, Research and Analytics, reporting to Totade. With 20 years of experience applying insight and analytics to complex challenges, Driver will lead research and analytics in the U.S, working across practices and client teams to advance audience intelligence, AI-driven insights, and measurement. He will also help strengthen the connection between strategy and technology, with a focus on developing more rigorous, practice-specific approaches and demonstrating the business impact of communications.
“What drew me to Ruder Finn is the clarity of the agency’s tech-forward vision and the genuine commitment to making it real,” said Driver. “The technology, the talent and the ambition are already here. I’m excited to help make research and analytics an even more central part of how we understand audiences, guide strategy and demonstrate impact for clients.”
Together, these appointments further build out the leadership and expertise supporting Ruder Finn’s integrated approach to technology, data and AI.
Totade has spent more than 16 years at Ruder Finn building the agency’s technology, data and AI capabilities. He joined the company as a senior developer and went on to establish rf.TechLab, Ruder Finn’s emerging technology incubator, in 2018. Today, he leads an international team spanning engineering, analytics and digital development, co-leads the agency’s AI-powered creative studio rf.Studio53, and oversees research and insights capabilities that combine proprietary methodologies with enterprise analytics tools. He has received significant industry recognition, including PRWeek’s “40 Under 40”, PRovoke Media’s Data Professional of the Year award and being named one of the PRNews People of the Year in the Agency Innovators.
About Ruder Finn
Ruder Finn is one of the world’s largest independent global communications and integrated marketing agencies, leading the industry in AI strategy and implementation. Founded in 1948, Ruder Finn has defined and redefined PR for over 75 years, shaping communications that move industry-defining brands, companies, and leaders from what’s now to what’s next. Ruder Finn provides clients with bold strategies based on a global perspective and localized market knowledge that redefine leadership, reimagine the marketplace, and rethink customer experiences. The agency is organized around five core areas of expertise—Healthcare, Technology, Consumer Brand, Leadership and Workplace—with innovative tech incubator RF TechLab providing cutting-edge predictive analytics, AI-powered creative hub RF Studio53 offering breakthrough creative, and specialized teams delivering customer-focused digital engagement. Ruder Finn has offices across four continents including the U.S., Asia, Europe and the Middle East. Wholly owned agencies and offerings within Ruder Finn Group include: Ruder Finn Inc., RF Studio53, RF Engage, Touchdown, Peppercomm, RF Comunicad, Mantis, jacobstahl, Flightpath, Ruder Finn Atteline, Pandan Social, RF Bloom, and Big Sky Communications. For more information visit www.ruderfinn.com.
View original content to download multimedia:https://www.prnewswire.com/news-releases/ruder-finn-promotes-tejas-totade-to-global-chief-technology-officer-and-chief-data–ai-officer-302926576.html
SOURCE Ruder Finn


Dental 3D Printing Market worth $10.08 billion by 2031 – Exclusive Report by MarketsandMarkets™

Tree Hut Unwraps Seven Festive Scents In Its New Limited-Edition Holiday Collection

Ruder Finn Promotes Tejas Totade to Global Chief Technology Officer and Chief Data & AI Officer

Send Rakhi to UK swiftly with UK Gifts Portal

Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

Nullmax and Renesas Forge Strategic Partnership to Deliver Competitive ADAS Solutions for the Global Market

Why You Should Build on #NEAR – Co-founder Illia Polosukhin at CV Labs
Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

NEAR End of Year Town Hall 2021: The Open Web World, MetaBUILD 2 Hackathon and 2021 recap
Trending
-

 Coin Market4 days ago
Binance hack may involve private key ‘misuse,’ not theft: Blockaid CEO
-
 Coin Market4 days ago
Canton Foundation grants RedStone 15.8M Canton Coin for pricing standard
-
 Technology4 days ago
Moonello Shifts Focus to AI and Software Engineering, Introduces Four Fixed-Fee Services
-

 Technology4 days ago
From Catapult to capital: NextFin Asia reaches first investment milestone with Indonesia’s Finfra
-
 Technology4 days ago
Appian Defense Cloud Achieves IL5 Authorization Across Department of War Operations
-
 Technology4 days ago
United Premier Soccer League Names Corgi Insurance Its Official Insurance Partner
-
Technology4 days ago
Thirty Weihai Companies Added to Shandong’s Green Factory List
-
 Technology3 days ago
Thirty Weihai Companies Added to Shandong’s Green Factory List