Connect with us

Technology

Avionics Display Market to grow by USD 1.33 Billion (2024-2028), driven by rising automation demand, Report highlights AI-driven market evolution – Technavio

Published

on

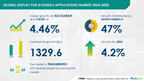
NEW YORK, Dec. 4, 2024 /PRNewswire/ — Report on how AI is driving market transformation – The global display for avionics applications market  size is estimated to grow by USD 1.33 billion from 2024-2028, according to Technavio. The market is estimated to grow at a CAGR of over 4.46%  during the forecast period. Growing demand for automation is driving market growth, with a trend towards introduction of automatic ground collision avoidance system (auto-gcas). However, barriers to adoption of new technologies and equipment  poses a challenge. Key market players include Astronautics Corp. Of America, Astronics Corp., Avidyne Corp., BAE Systems Plc, Diehl Stiftung and Co. KG, Elbit Systems Ltd., Excelitas Technologies Corp., FDS Avionics Corp., Gables Engineering Inc., Garmin Ltd., General Electric Co., Honeywell International Inc., L3Harris Technologies Inc., Mercury Systems Inc., Nytric Ltd., Parker Hannifin Corp., RTX Corp., ScioTeq BV, Thales Group, and The Boeing Co..

AI-Powered Market Evolution Insights. Our comprehensive market report ready with the latest trends, growth opportunities, and strategic analysis- View Free Sample Report PDF

Forecast period

2024-2028

Base Year

2023

Historic Data

2018 – 2022

Segment Covered

End-user (Civil aviation and Military aviation), Type (In-flight display and Heads-up display (HUD)), and Geography (North America, Europe, APAC, South America, and Middle East and Africa)

Region Covered

North America, Europe, APAC, South America, and Middle East and Africa

Key companies profiled

Astronautics Corp. Of America, Astronics Corp., Avidyne Corp., BAE Systems Plc, Diehl Stiftung and Co. KG, Elbit Systems Ltd., Excelitas Technologies Corp., FDS Avionics Corp., Gables Engineering Inc., Garmin Ltd., General Electric Co., Honeywell International Inc., L3Harris Technologies Inc., Mercury Systems Inc., Nytric Ltd., Parker Hannifin Corp., RTX Corp., ScioTeq BV, Thales Group, and The Boeing Co.

Key Market Trends Fueling Growth

The Avionics Applications Market is experiencing significant growth, particularly in the areas of Primary Flight Displays and Multifunction Displays. Smaller displays under 5 inches are popular for military applications, while larger displays between 5 to 10 inches and greater than 10 inches cater to commercial aviation. Enhanced safety and situational awareness are key trends, with automated flight control and lightweight components also in demand. Display blackouts and system failures are major concerns, driving the need for large-format multi-functional displays, external display processors, video sensors, FLIR, and radar. Defense plans rely on advanced avionics, including weapons, cameras, and user interfaces. New aircraft, such as the Checkmate fighter, feature portrait orientation radars and full-glass cockpits with flight-control computers. Commercial aircraft focus on air traffic, load factor, and flight data. Modern cockpit displays offer touchscreens, wide viewing angles, high-resolution graphics, and heads-up displays. The aerospace industry seeks display solutions with smart displays, augmented reality, and digital cockpits to improve flight safety. Power consumption and contrast ratio are crucial factors, with liquid crystal displays being widely used. The Avionics Application Market serves pilots and civil and military aviation with flight instruments and outside views. 

The avionics market has seen significant advancements in technology to enhance aviation safety. In 2010, NASA, the US Air Force, and Lockheed Martin developed the Automatic Ground Collision Avoidance System (auto-GCAS) to prevent aircraft accidents. This system continuously monitors an aircraft’s position and distance from the ground, providing real-time status to pilots and assisting during critical situations. In 2022, the US military aviation specialists required upgrades to the flight-control software in Navy combat aircraft to minimize ground collisions. The Boeing Company provided the solution with advanced software upgrades for their defense, space, and security division. 

Insights on how AI is driving innovation, efficiency, and market growth- Request Sample!

Market Challenges

The Avionics Applications Market encompasses various display solutions for the Aviation industry, including Primary Flight Displays and Multifunction Displays in various sizes: less than 5 inches, 5 to 10 inches, and greater than 10 inches. These displays are essential for military and commercial aircraft, enhancing safety and situational awareness with automated flight control, lightweight components, and enhanced contrast ratio. However, challenges include display blackouts, system failure, and power consumption. Large-format multi-functional displays, external display processors, video sensors like FLIR and Radar, weapons, cameras, and defense plans are integral to military avionics. Commercial aircraft require displays for air traffic, load factor, and flight data. Modern cockpit displays include touchscreens, wide viewing angles, high-resolution graphics, and user interfaces for pilots, offering outside views and heads-up displays. The market includes smart displays, augmented reality, and digital cockpits, with ongoing advancements in military and civil aviation.In the avionics market for commercial aircraft applications, regulatory compliance is a top priority. Vendors supplying avionic systems must adhere to stringent regulations set by organizations like the FAA, ICAO, and EASA to ensure passenger safety. Advanced technologies undergo thorough testing and certification processes before implementation. However, introducing new technologies comes with challenges, including high costs and the requirement for specialized expertise. The increasing demand for efficient, lightweight, dependable, and long-lasting equipment drives up research and development expenses.

Insights into how AI is reshaping industries and driving growth- Download a Sample Report

Segment Overview 

This display for avionics applications market report extensively covers market segmentation by

End-user 1.1 Civil aviation1.2 Military aviationType 2.1 In-flight display2.2 Heads-up display (HUD)Geography 3.1 North America3.2 Europe3.3 APAC3.4 South America3.5 Middle East and Africa

1.1 Civil aviation-  The civil aviation display market is segmented into primary flight displays (PFDs) and multifunctional displays (MFDs), based on display technologies and applications. PFDs provide pilots with vital flight information, including altitude, speed, and navigational data, using LCD or OLED technologies. MFDs offer a range of functions, from navigation and communication to engine monitoring and weather information, and may include head-up displays (HUDs). Avionics systems incorporate various displays, such as cockpit displays, cabin management displays, test and maintenance displays, and emergency and warning displays. Touchscreen technology enhances these displays, providing an intuitive user interface. In 2020, the civil aviation industry faced challenges due to COVID-19, leading to a decline in air passenger traffic and a reduction in aircraft orders. However, the resumption of manufacturing plants and increasing demand for single-engine and multi-engine piston aircraft are driving market growth. Innovations in display technology, such as the integration of HUDs, are also contributing to market expansion. For instance, China’s mandatory adoption of HUDs by 2025 will increase the demand for avionics application displays.

Download complimentary Sample Report to gain insights into AI’s impact on market dynamics, emerging trends, and future opportunities- including forecast (2024-2028) and historic data (2018 – 2022) 

Research Analysis

The Display for Avionics Applications market encompasses a range of primary flight displays and multifunction displays used in the Aviation industry. These displays come in various sizes, including less than 5 inches, 5 to 10 inches, and greater than 10 inches. They are employed in both military and commercial aviation, including new aircraft and cockpit components. These displays offer enhanced safety and situational awareness for pilots by providing modern cockpit displays with touchscreens, wide viewing angles, and high-resolution graphics. They can also include automated flight control systems, outside views, and user interfaces for cockpit instruments and head-up displays. Lightweight components ensure reduced weight in aircraft design. Avionics applications continue to evolve, offering advanced features for flight safety and improved operational efficiency.

Market Research Overview

The Display for Avionics Applications market encompasses a range of primary flight displays and multifunction displays, available in sizes less than 5 inches, 5 to 10 inches, and greater than 10 inches. These displays are integral to both military and commercial aviation industries, enhancing safety and situational awareness in new aircraft cockpits. They serve as cockpit components, providing automated flight control, lightweight components, and advanced features like external display processors, video sensors, FLIR, radar, weapons, and cameras. These displays are designed for various orientations, including portrait orientation, and offer enhanced functionality with radars, full-glass cockpits, and flight-control computers. They cater to commercial aircraft, providing air traffic, load factor, and flight data information to pilots. The market also includes advanced technologies like touchscreens, wide viewing angles, high-resolution graphics, and smart displays with augmented reality capabilities. The Display for Avionics Applications market is crucial for defense and aerospace industries, contributing to defense plans and aircraft deliveries, as well as the development of digital cockpits and heads-up displays for military aviation and civil aviation.

Table of Contents:

1 Executive Summary
2 Market Landscape
3 Market Sizing
4 Historic Market Size
5 Five Forces Analysis
6 Market Segmentation

End-userCivil AviationMilitary AviationTypeIn-flight DisplayHeads-up Display (HUD)GeographyNorth AmericaEuropeAPACSouth AmericaMiddle East And Africa

7 Customer Landscape
8 Geographic Landscape
9 Drivers, Challenges, and Trends
10 Company Landscape
11 Company Analysis
12 Appendix

About Technavio

Technavio is a leading global technology research and advisory company. Their research and analysis focuses on emerging market trends and provides actionable insights to help businesses identify market opportunities and develop effective strategies to optimize their market positions.

With over 500 specialized analysts, Technavio’s report library consists of more than 17,000 reports and counting, covering 800 technologies, spanning across 50 countries. Their client base consists of enterprises of all sizes, including more than 100 Fortune 500 companies. This growing client base relies on Technavio’s comprehensive coverage, extensive research, and actionable market insights to identify opportunities in existing and potential markets and assess their competitive positions within changing market scenarios.

Contacts

Technavio Research
Jesse Maida
Media & Marketing Executive
US: +1 844 364 1100
UK: +44 203 893 3200
Email: media@technavio.com
Website: www.technavio.com/

View original content to download multimedia:https://www.prnewswire.com/news-releases/avionics-display-market-to-grow-by-usd-1-33-billion-2024-2028-driven-by-rising-automation-demand-report-highlights-ai-driven-market-evolution—technavio-302321187.html

SOURCE Technavio

Continue Reading

Technology

JinkoSolar Announces Results of 2026 Annual General Meeting

Published

on

By

SHANGRAO, China, Oct. 21, 2026 /PRNewswire/ — JinkoSolar Holding Co., Ltd. (“JinkoSolar” or the “Company”) (NYSE: JKS), today announced that all shareholders resolutions proposed at the Company’s 2026 annual general meeting held today were duly passed.

Specifically, the Company’s shareholders passed the following ordinary resolutions approving:

1. The re-election of Mr. Gang Chu as an independent director of the Company;
2. The re-election of Mr. Steven Markscheid as an independent director of the Company;
3. The ratification of the appointment of PricewaterhouseCoopers Zhong Tian LLP as auditors of the Company for the fiscal year of 2026;
4. The authorization of the directors of the Company to determine the remuneration of the auditors of the Company; and
5. The authorization of each of the directors of the Company to take any and all action that might be necessary to effect the foregoing resolutions 1 to 4 and resolutions 6 to 7 set out below as such director, in his or her absolute discretion, thinks fit.

The Company’s shareholders also passed the following special resolutions approving:

6. The change of the English name of the Company from “JinkoSolar Holding Co., Ltd.” to “Jinko Holdings Limited”; and
7. The adoption of “晶科控股有限公司” as the dual foreign name of the Company.

 About JinkoSolar Holding Co., Ltd.

JinkoSolar (NYSE: JKS) is a holding company combining clean energy industrial operations and strategic investment in emerging technologies. Its industrial foundation is a controlling interest in Jinko Solar Co., Ltd. (SSE: 688223), a global leader in clean energy technology. The Company makes disciplined strategic investments in renewable energy, advanced materials, artificial intelligence, commercial space and other frontier technologies, drawing on its industrial experience and its ability to identify emerging technologies and bring them to commercial scale.

Through Jinko Solar Co., Ltd., the Company distributes its solar products and sells its solutions and services to a diversified international utility, commercial and residential customer base in China, the United States, Japan, Germany, the United Kingdom, Chile, South Africa, India, Mexico, Brazil, the United Arab Emirates, Italy, Spain, France, Belgium, Netherlands, Poland, Austria, Switzerland, Greece and other countries and regions.

JinkoSolar has over 10 production facilities globally, over 20 overseas subsidiaries in Japan, South Korea, Vietnam, India, Turkey, Germany, Italy, Switzerland, the United States, Mexico, and other countries, and a global sales network with sales teams in China, the United States, Canada, Brazil, Chile, Mexico, Italy, Germany, Turkey, Spain, Japan, the United Arab Emirates, Netherlands, Vietnam and India, as of June 30, 2026.

For investor and media inquiries, please contact:

In China:

Ms. Stella Wang
JinkoSolar Holding Co., Ltd.
Tel: +86 21-5180-8777 ext.7806
Email: ir@jinkosolar.com 

Mr. Christian Arnell
Christensen
Tel: +852 2117 0861
Email: christian.arnell@christensencomms.com 

In the U.S.:

Email: jinko@christensencomms.com 

View original content:https://www.prnewswire.com/news-releases/jinkosolar-announces-results-of-2026-annual-general-meeting-302914898.html

SOURCE JinkoSolar Holding Co., Ltd.

Continue Reading

Technology

Price still dominates car buying in US and Europe, while China puts technology first–Bain & Company survey

Published

on

By

Dealers stay important: More than 80% of car buyers globally now combine online and offline channels, yet nine in 10 still complete their purchase at dealersAI is reshaping car-buying journey in all markets – more than 60% of younger buyers use AI when deciding on their next carConsumers who have test-driven a battery electric vehicle are up to 2.2 times as willing to consider buying oneCustomer loyalty is decreasing – more than a third of customers in Western markets are open to new brands entering the market Autonomous-driving technology could challenge traditional brand loyalty, with consumers willing to switch brands for better functionality

BOSTON and MUNICH, Oct. 21, 2026 /PRNewswire/ — New technologies, including AI, are changing how consumers research and choose cars around the globe. Brand loyalty is decreasing and price continues to play a powerful role in purchasing decisions in the US and Europe, but less so for Chinese buyers, as new research released today by Bain & Company finds.

Bain’s new Global Automotive Consumer Survey, based on responses from more than 12,000 car buyers worldwide*, finds price remains the top consideration when buying a car in the US and Europe, cited by 68% and 62% of consumers respectively, while technology and features (58%) rank ahead of price in China. Loyalty to established automakers also varies considerably: US buyers remain the most committed, while newer Chinese brands are entering consideration in Europe.

The findings come as legacy automakers face weak industry growth and continued pressure on profitability, alongside rapid advances in electrification, artificial intelligence and autonomous driving.

“The car-buying journey is changing quickly, but what stands out is how differently consumers across the globe are responding to that change,” said Klaus Stricker, leader of Bain’s Global Automotive & Mobility practice. “Technology can be a powerful differentiator for some buyers, while for others, price and brand remain decisive. We find that car buyers are increasingly using AI to compare brands, models and options.”

Digital car buying accelerates, but dealerships remain critical

The way consumers choose cars has become increasingly digital. Bain finds that more than 80% of respondents globally now combine online and offline interactions during the purchase journey, while more than six in 10 start the buying process online. China is further ahead, with 95% using both online and physical channels and more than eight in 10 willing to consider completing their purchase online.

But greater use of digital channels has not diminished the importance of the physical dealership. Nine in 10 consumers globally still complete their purchase offline, and more than half of buyers in Europe, the US and China have at least two interactions with dealers along the way.

Artificial intelligence is also reshaping how consumers research and compare cars. AI is already widely used by car buyers across several Asian markets and UAE, reaching more than 90% in Indonesia and close to 80% across age groups in China. In Japan, Europe and the US, adoption is more concentrated among younger buyers, with 52%, 61% and 55% respectively using AI, more than twice the share of older consumers.

Younger consumers drive BEV interest, but barriers to wider adoption remain

Consumer interest in battery electric vehicles (BEVs) is strong, particularly among younger buyers, the survey finds. Younger consumers (Generations Y and Z) in general are more likely to buy BEVs, but in China, willingness to buy BEVs is high across both younger and older generations.

For consumers still reluctant to buy a BEV, cost and charging remain the biggest sticking points. In the US and Europe, around six in 10 are unwilling to pay more for a BEV than for a comparable combustion-engine car, while almost half cite charging times as a concern. Bain concludes that closing the price gap and making charging more convenient will be critical to persuading more consumers to make the switch.

Bain cites an example in Germany where BEV-buying decisions shifted once price parity narrowed. In August 2026, BEV registrations jumped 75% year-on-year to reach around 32% of new car sales. New government incentives and rising fuel prices drove the change – in addition to new strong BEV models entering the market.

Getting more buyers behind the wheel provides another lever. Consumers who have already test-driven a BEV are up to 2.2 times more willing to consider purchasing one than those who have not. Yet mass-market buyers in Europe and the US are less likely to have tried a BEV, compared to premium buyers. With many potential buyers yet to try one, making test-drives easier to access could be one of the most effective ways for automakers and dealers to encourage wider BEV adoption.

Autonomous driving could challenge traditional brand loyalty

Appetite for autonomous-driving technology is substantially stronger in China and several Asian and Middle Eastern markets than in Europe and the US, Bain finds. Some 84% of Chinese consumers would consider buying a vehicle offering at least Level 3 (L3) autonomy, compared with 47% in Europe and 40% in the US. L3 allows a car to drive itself under certain conditions but requires the driver to take over when prompted. Interest is even higher in the UAE, India and Indonesia.

Greater interest in autonomous driving could also weaken traditional brand loyalty. Consumers most interested in the technology are more willing to switch manufacturers for better functionality, with premium buyers in Europe and the US particularly open to changing brands. In China, willingness to switch is more widespread. For automakers, better autonomous-driving functionality could therefore become an increasingly important way to attract customers from competitors.

“Technology is now part of the reason customers choose one manufacturer over another,” Stricker added. “That raises the stakes for automakers. Brands need to understand where customers are willing to pay for innovation, where affordability remains the overriding consideration, and where better technology could be enough to persuade a customer to switch. That requires a much more precise understanding of what different customers value.”

*Markets included in the survey: Canada, US, UK, Germany, France, Italy, UAE, China, India, Indonesia, and Japan. 

Media contacts:
Ann Lee (Singapore) — ann.lee@bain.com
Gary Duncan (London) — gary.duncan@bain.com
Dan Pinkney (Boston) — dan.pinkney@bain.com 

About Bain & Company

Bain & Company works with leaders worldwide to solve their toughest challenges and deliver enduring results. Since 1973, we’ve partnered with clients, including private equity and portfolio companies, to build the capabilities they need to stay ahead of change and help them redefine their industries. We measure our success by our clients’ success, and we proudly hold the highest levels of client advocacy in our field.

Bain is consistently recognized globally as one of the best places to work. We operate as one global team, uniting strategists, industry and functional experts, technologists, and advisors with a vibrant ecosystem of technology partners.

Notes to Editors 

Bain & Company was founded in 1973 and today has 19,000 employees across 67 cities in 40 countries. We have worked with more than two-thirds of the Global 500 and more than 9,000 companies worldwide. Bain has pledged to deliver $2 billion in pro bono consulting to nonprofit, public sector, and charitable organizations by 2035. The firm is consistently recognized as a Leader in major analyst rankings across multiple areas, including digital business, innovation, strategy, experience design, customer experience, and carbon-zero transformation.

View original content to download multimedia:https://www.prnewswire.com/news-releases/price-still-dominates-car-buying-in-us-and-europe-while-china-puts-technology-firstbain–company-survey-302914783.html

SOURCE Bain & Company

Continue Reading

Technology

HiTHIUM enters Canada with first 8-hour BESS and sodium-ion solutions adapted to extreme cold

Published

on

By

TORONTO, Oct. 21, 2026 /CNW/ — HiTHIUM, an integrated full-scenario energy storage solutions provider, has announced its entry into the Canadian market. Ranked in the top two globally for energy storage component, the manufacturer has surpassed 200 GWh in cumulative delivered capacity, focusing exclusively on stationary energy storage technologies.

Canada’s energy storage expansion requires reliable large-scale suppliers and local presence

Mizhi Zhang, HiTHIUM President of Global Business, commented: “We are committed to delivering Canadian customers advanced, robust solutions, from 8-hour long duration energy storage to extreme-weather-ready sodium-ion BESS. But this also means being present for customers wherever they are, able to serve them quickly and locally. While Toronto serves as the main hub for our Canadian operations, we have subsidiary offices in British Columbia and Alberta, as well as operating sites in Quebec, Yellowknife, and Fort Smith.” 

HiTHIUM has introduced 4-hour and 8-hour BESS solutions to serve the market’s rapid buildout of utility-scale energy storage. With installed Canadian storage expected to double between 2025 and 2027, and the country’s total wind, solar, and energy storage capacity on track to reach 50 GW by 2035, HiTHIUM is positioned to fill the growing demand for BESS on a large scale. The company has also revealed a new 4 MWh sodium-ion storage solution, which is designed for an extra-long service life, supports storage durations from 2 to 8 hours, and is perfect for extremely cold climates, like Northern Canada.

“Canada’s ambitious clean energy targets, as well as its high safety and regulatory standards, require partners who can deliver advanced technology that’s also tested and compliance-ready. At the same time, project developers have to consider the tough climate. As a vertically integrated, global solutions provider, HiTHIUM is structured to meet exactly this nexus of challenges. Our strategy of advancing both lithium-ion and sodium-ion storage is designed to offer customers in markets like Canada the benefits of flexibility, since we see these technologies as highly complementary,” continued Zhang.

“Our partners, whether major energy developers, public utilities, or industrial enterprises, rely on our readiness for local certification and our long-term bankability to support them, from permitting through project commissioning,” added Jordan Hebbert, HiTHIUM Senior Manager of Canada. “Likewise, they depend on the proven durability of HiTHIUM technology–including performance even in extreme weather conditions. In fact, long-term operational data from North American and European projects has recently demonstrated systems outperforming even our guarantees. And we offer customers a wider range of durations and choice of chemistries because we understand that they’re coming to us with a very diverse range of energy storage needs.”

4-hour or 8-hour BESS: Matching duration to project specifications

The manufacturer’s 4-hour BESS solution consists of its “∞Power” 6.25 MWh container, built on HiTHIUM’s own 1175 Ah cell. Most Canadian projects are currently designed around the 4-hour unit. This enables them to shift wind, solar, and baseload output to later peak times, strengthen grid reliability, and drive the consumption of more renewables, particularly as electrification increases demand. The ∞Power system design fits more capacity into the typical 20-foot container but also reduces a project’s overall footprint, because the containers can be placed back-to-back and side-to-side.

In a groundbreaking step for long duration energy storage, HiTHIUM also developed the first ever native 8-hour solution based on lithium-ion technology. Its 6.9 MWh 8-hour BESS, built with HiTHIUM’s own 1300 Ah cells, fewer components overall, and a 25-year lifespan, is designed to address issues like curtailments and to fill key gaps for zero-downtime industrial segments like AI data centers. For wind project developers and data center operators alike, 8-hour BESS offers risk reduction and greater revenue reliability.  

Extreme fire test validates safety architecture

HiTHIUM additionally worked with UL Solutions at the start of 2026 on an independently conducted, extreme fire test of its 6.25 MWh block’s intrinsic safety systems. A container was subjected to 24 hours of extreme combustion conditions, with its doors opened for maximum thermal spread, while neighboring containers were placed just 15 cm away. Only the containers’ passive safety systems were enabled. The results validated HiTHIUM’s multi-layer safety architecture, with the tested container structurally intact after the test, no thermal propagation across the containers, and the temperatures of cells in adjacent containers remaining below safety thresholds.

View original content:https://www.prnewswire.com/news-releases/hithium-enters-canada-with-first-8-hour-bess-and-sodium-ion-solutions-adapted-to-extreme-cold-302914919.html

SOURCE HiTHIUM

Continue Reading

Trending