
Technology
Amcor reports second quarter and first half result. Reaffirms fiscal 2025 outlook

Published
2 years agoon
By

December 2024 Quarter Highlights:
Further sequential improvement in year over year volume growth;Net sales of $3,241 million;GAAP Net income of $163 million; GAAP diluted earnings per share (EPS) of 11.3 cps;Adjusted EBIT of $363 million, up 5% on a comparable constant currency basis;Adjusted EPS of 16.1 cps, up 5% on a comparable constant currency basis; andAnnounced highly complementary and financially compelling combination with Berry Global
Fiscal 2025 First Half Highlights:
Net sales of $6,594 million;GAAP Net income of $354 million; GAAP diluted EPS of 24.4 cps;Adjusted EBIT of $728 million, up 4% on a comparable constant currency basis; andAdjusted EPS of 32.2 cps, up 5% on a comparable constant currency basis.
Fiscal 2025 outlook reaffirmed:
Adjusted EPS of 72-76 cents per share; Adjusted Free Cash Flow of $900-1,000 million.
ZURICH, Feb. 4, 2025 /PRNewswire/ —
Amcor delivers another quarter of solid earnings and volume growth; Reaffirms FY25 guidance;
Combination with Berry Global to significantly enhance value for our customers and shareholders
CEO Peter Konieczny said: “Amcor delivered a solid second quarter result aligned with the expectations we set out in October, giving us the confidence to again reaffirm our guidance for the fiscal year. We continued to execute well on our underlying business, delivering our fourth consecutive quarter of sequential volume improvement. Margins continued to expand, supporting adjusted EBIT and EPS growth of 5% on a comparable basis for the quarter.”
“We also announced the next transformational step for Amcor, agreeing to combine with Berry Global. Bringing these two companies together will deliver on our strategy to become an even stronger company with accelerated volume-driven organic growth achieved through an unwavering focus on our customers, sustainability and portfolio mix. The combined company will have enhanced positions in attractive categories, the material science and innovation capabilities required to further revolutionize product development and a broader, more complete portfolio of primary packaging solutions for consumer and healthcare customers. With faster growth and $650 million of identified synergies, this combination will drive significant near and long term value for all shareholders. The path to completion is well advanced and we remain on track to close in mid calendar year 2025.”
Key Financials
Six Months Ended December 31,
GAAP results
2023 $ million
2024 $ million
Net sales
6,694
6,594
Net income attributable to Amcor plc
286
354
EPS (diluted US cents)
19.8
24.4
Comparable
constant
currency ∆%
Six Months Ended December 31,
Reported ∆%
Adjusted non-GAAP results(1)
2023 $ million
2024 $ million
Net sales
6,694
6,594
(1)
(1)
EBITDA
913
919
1
2
EBIT
709
728
3
4
Net income
453
467
3
5
EPS (diluted US cents)
31.3
32.2
3
5
Free Cash Flow
52
(38)
(1) Adjusted non-GAAP results exclude items which are not considered representative of ongoing operations. Comparable constant currency ∆% excludes the impact of movements in foreign exchange rates and items affecting comparability. Further details related to non-GAAP measures and reconciliations to GAAP measures can be found under “Presentation of non-GAAP information” in this release. Note: All amounts referenced throughout this document are in US dollars unless otherwise indicated and numbers may not add up precisely to the totals provided due to rounding.
Shareholder returns
Dividend
The Amcor Board of Directors today declared a quarterly cash dividend of 12.75 cents per share (compared with 12.5 cents per share in the same quarter last year). The dividend will be paid in US dollars to holders of Amcor’s ordinary shares trading on the NYSE. Holders of CDIs trading on the ASX will receive an unfranked dividend of 20.40 Australian cents per share, which reflects the quarterly dividend of 12.75 cents per share converted at an AUD:USD average exchange rate of 0.6251 over the five trading days ended January 31, 2025.
The ex-dividend date will be February 25, 2025 for holders of CDIs trading on the ASX and February 26, 2025 for holders of shares trading on the NYSE. For all shareholders, the record date will be February 26, 2025 and the payment date will be March 18, 2025.
Financial results – Six Months Ended December 31, 2024
Segment information
Six Months Ended December 31, 2023
Six Months Ended December 31, 2024
Adjusted non-GAAP
results
Net sales
$ million
EBIT
$ million
EBIT /
Sales %
EBIT / Average
funds employed
%(1)
Net sales
$ million
EBIT
$ million
EBIT /
Sales %
EBIT / Average
funds employed
%(1)
Flexibles
5,049
634
12.6
5,062
651
12.9
Rigid Packaging
1,645
113
6.9
1,532
115
7.5
Other(2)
—
(38)
—
(38)
Total Amcor
6,694
709
10.6
14.5
6,594
728
11.0
15.0
(1) Return on average funds employed includes shareholders’ equity and net debt, calculated using a four quarter average and last twelve months adjusted EBIT.
(2) Represents corporate expenses.
Six months ended December 31, 2024:
Net sales of $6,594 million were 1% lower than last year on a reported basis, including an unfavorable impact of approximately 1% related to movements in foreign exchange rates. The pass through of lower raw material costs had no material impact on net sales.
Volumes were up 2% compared with the same six month period last year. Price/mix had an unfavorable impact of approximately 3%, primarily due to expected lower volumes in high value healthcare categories. On a comparable constant currency basis, net sales were down less than 1% compared with last year.
Adjusted EBIT of $728 million was 4% higher than last year on a comparable constant currency basis reflecting higher volumes and strong cost performance, partly offset by unfavorable impacts from price/mix. Adjusted EBIT margin improved to 11.0%, a 40 basis point increase over the prior year.
December 2024 quarter:
Net sales of $3,241 million were in line with last year on a reported basis, including an unfavorable impact of approximately 1% related to movements in foreign exchange rates and a favorable impact of 1% related to the pass through of higher raw material costs of approximately $20 million.
Volumes were up 2.3% compared with last year, improving on first quarter year over year volume growth of 1.6% and the fourth consecutive quarter of sequential volume improvement. As expected, destocking continued in healthcare and demand remained soft in the North America beverage business through the December quarter, unfavorably impacting overall volumes by more than 1%. Across the balance of the business, overall volume growth was consistent with the first quarter, up approximately 4%. Price/mix had an unfavorable impact of approximately 2% primarily due to lower volumes in high value healthcare categories. On a comparable constant currency basis, sales returned to growth in the December quarter and were marginally higher than last year.
Adjusted EBIT of $363 million was approximately 5% higher than last year on a comparable constant currency basis.
Higher volumes, continued strong cost performance and benefits from restructuring initiatives were partly offset by unfavorable impacts from price/mix. Adjusted EBIT margin improved to 11.2%, a 40 basis point increase over the prior year.
Flexibles segment – December 2024 quarter
Three Months Ended December 31,
Reported
∆%
Comparable
constant
currency ∆%
2023 $ million
2024 $ million
Net sales
2,481
2,511
1
1
Adjusted EBIT
312
322
3
4
Adjusted EBIT / Sales %
12.6
12.8
Net sales of $2,511 million were 1% higher than last year on a reported basis. Unfavorable movements in foreign exchange rates and favorable impacts related to the pass through of higher raw material costs each had an offsetting impact on net sales of approximately 1%.
Volumes were up approximately 3% compared with the prior year with continued growth across all key regions. As expected, destocking continued in healthcare, unfavorably impacting overall segment volumes by approximately 1%. Across the balance of the Flexibles business, overall volumes were approximately 4% higher than the prior year. Price/mix had an unfavorable impact on net sales of approximately 2%, primarily due to lower volumes in high value healthcare categories. On a comparable constant currency basis net sales were approximately 1% higher than last year.
In North America, net sales grew at low single digit rates on a comparable constant currency basis driven by mid single digit volume growth, partly offset by unfavorable price/mix. Volumes were higher across a broad range of categories including meat, dairy, liquids and fresh & frozen foods and this was partly offset by lower volumes in categories including snacks & confectionary and pharmaceutical.
In Europe, net sales grew at low single digit rates on a comparable constant currency basis driven by mid single digit volume growth, partly offset by unfavorable price/mix. Volumes were higher in the dairy, single serve coffee, home & personal care and pet care end markets and this was partly offset by lower volumes in categories including snacks & confectionary and healthcare.
Across Asia, net sales grew at high single digit rates on a comparable constant currency basis driven by mid single digit volume growth and modest price/mix benefits. Volumes were higher in China and across the South East Asia region. In Latin America, net sales on a comparable constant currency basis grew at low single digit rates primarily driven by favorable price/mix benefits. Volumes were broadly in line with last year.
Adjusted EBIT of $322 million was 4% higher than last year on a comparable constant currency basis. The positive impact of higher volumes and strong cost performance was partly offset by unfavorable price/mix. Adjusted EBIT margin of 12.8% was 20 basis points higher than last year.
Flexibles segment – December YTD
Six Months Ended December 31,
Reported
∆%
Comparable
constant
currency ∆%
2023 $ million
2024 $ million
Net sales
5,049
5,062
—
—
Adjusted EBIT
634
651
3
4
Adjusted EBIT / Sales %
12.6
12.9
Net sales of $5,062 million were up modestly compared with last year on a reported basis. Unfavorable movements in foreign exchange rates and favorable impacts related to the pass through of higher raw material costs each had an offsetting impact on net sales of approximately 1%.
Volumes were up approximately 3% compared with the prior year with growth delivered across all key regions. Destocking in healthcare categories unfavorably impacted overall segment volumes by approximately 1%. Price/mix had an unfavorable impact on net sales of approximately 3%, primarily due to lower volumes in high value healthcare categories. On a comparable constant currency basis net sales were in line with last year.
In North America, net sales were up low single digits on a comparable constant currency basis, driven by low to mid single digit volume growth partly offset by unfavorable price/mix.
In Europe, net sales were in line with last year on a comparable constant currency basis, driven by mid single digit volume growth offset by unfavorable price/mix.
Across Asia, net sales on a comparable constant currency basis and volumes increased at mid single digit rates with growth in India and China partly offset by lower volumes in South East Asia. In Latin America, net sales on a comparable constant currency basis and volumes increased at low to mid single digit rates, largely driven by growth in Brazil and Peru.
Adjusted EBIT of $651 million was approximately 4% higher than last year on a comparable constant currency basis. The positive impact of higher volumes, favorable cost performance and benefits from restructuring initiatives was partly offset by unfavorable price/mix. Adjusted EBIT margin of 12.9% was 30 basis points higher than last year.
Rigid Packaging segment – Dec 2024 quarter
Three Months Ended December 31,
Reported
∆%
Comparable
constant
currency ∆%
2023 $ million
2024 $ million
Net sales
770
730
(5)
(1)
Adjusted EBIT
51
53
5
10
Adjusted EBIT / Sales %
6.6
7.3
Net sales of $730 million were 5% lower than last year on a reported basis, including an unfavorable impact of approximately 2% related to movements in foreign exchange rates and an unfavorable impact of approximately 2% related to the pass through of lower raw material costs of approximately $15 million.
On a comparable constant currency basis, net sales were approximately 1% lower than last year reflecting an unfavorable price/mix impact of approximately 2% partly offset by approximately 1% higher volumes.
As expected, consumer and customer demand remained soft and variable in the North America beverage business and volumes and comparable net sales declined at mid single digit rates. In Latin America, net sales were up mid single digits on a comparable constant currency basis reflecting favorable price/mix. Across the balance of the Rigid Packaging business volumes were higher than last year.
Adjusted EBIT of $53 million was 10% higher than last year on a comparable constant currency basis, reflecting benefits from continued cost actions and higher volumes, partly offset by unfavorable price/mix. Adjusted EBIT margin of 7.3% was 70 basis points higher than last year.
Rigid Packaging segment – December YTD
Six Months Ended December 31,
Reported
∆%
Comparable
constant
currency ∆%
2023 $ million
2024 $ million
Net sales
1,645
1,532
(7)
(3)
Adjusted EBIT
113
115
2
6
Adjusted EBIT / Sales %
6.9
7.5
Net sales of $1,532 million were 7% lower than last year on a reported basis, including an unfavorable impact of approximately 2% related to movements in foreign exchange rates and an unfavorable impact of approximately 2% related to the pass through of lower raw material costs of approximately $40 million.
On a comparable constant currency basis, net sales were approximately 3% lower than last year reflecting approximately 2% lower volumes and an unfavorable price/mix impact of approximately 1%.
North America beverage comparable net sales and volumes declined at mid single digit rate. In Latin America, comparable net sales were up mid single digits, primarily reflecting favorable price/mix benefits. Across the balance of the Rigid Packaging business volumes were higher than last year.
Adjusted EBIT of $115 million was approximately 6% higher than last year on a comparable constant currency basis, with the impact of lower volumes and unfavorable price/mix more than offset by benefits from cost actions. Adjusted EBIT margin of 7.5% was 60 basis points higher than last year.
Net interest and income tax expense
For the six months ended December 31, 2024, net interest expense of $147 million compares with $153 million last year. GAAP income tax expense was $101 million compared with $67 million last year. Adjusted tax expense for the six months ended December 31, 2024 of $108 million compared with $99 million last year. Adjusted tax expense for the six months ended December 31, 2024 represents an effective tax rate of 18.6%, compared with 18.0% in the prior year.
Adjusted Free Cash Flow
For the six months ended December 31, 2024, adjusted free cash outflow was $38 million, in line with the company’s expectations and compares with an inflow of $52 million last year.
Net debt was $6,496 million at December 31, 2024 and leverage, measured as net debt divided by adjusted trailing twelve month EBITDA, was 3.3 times and in line with expectations. Leverage is expected to be at or below 3.0x at June 30, 2025.
Fiscal 2025 Guidance reaffirmed
For the twelve month period ending June 30, 2025, the Company continues to expect:
Adjusted EPS of approximately 72 to 76 cents per share, which represents comparable constant currency growth of 3% to 8% (includes approximately 4% headwind related to normalization of incentive compensation payments) compared with 70.2 cents per share in fiscal 2024.Assuming current exchange rates prevail through fiscal 2025, movements in exchange rates are not expected to have a material impact on reported EPS.Adjusted Free Cash Flow of approximately $900 million to $1,000 million.
Amcor’s guidance contemplates a range of factors which create a degree of uncertainty and complexity when estimating future financial results. Further information can be found under ‘Cautionary Statement Regarding Forward-Looking Statements’ in this release. Reconciliations of the fiscal 2025 projected non-GAAP measures are not included herein because the individual components are not known with certainty as individual financial statements for fiscal 2025 have not been completed. Amcor’s guidance does not factor in any potential impact from the merger with Berry Global which may arise if the transaction closes before fiscal 2025 year end.
Conference Call
Amcor is hosting a conference call with investors and analysts to discuss these results on Tuesday February 4, 2025 at 8:00am US Eastern Standard Time / Wednesday February 5, 2025 at 12:00am Australian Eastern Daylight Time. Investors are invited to listen to a live webcast of the conference call at our website, www.amcor.com, in the “Investors” section.
Those wishing to access the call should use the following toll-free numbers, with the Conference ID: 2990465
USA: 800 715 9871 (toll free)USA: 646 307 1963 (local)Australia: 1800 519 630 (toll free), 02 9133 7103 (local)United Kingdom: 0800 358 0970 (toll free), 020 3433 3846 (local)Singapore: +65 3159 5133 (local)Hong Kong: +852 3002 3410 (local)
From all other countries, the call can be accessed by dialing +1 646 307 1963 (toll).
A replay of the webcast will also be available in the ‘Investors” section at www.amcor.com following the call.
About Amcor
Amcor is a global leader in developing and producing responsible packaging solutions across a variety of materials for food, beverage, pharmaceutical, medical, home and personal-care, and other products. Amcor works with leading companies around the world to protect products, differentiate brands, and improve supply chains. The Company offers a range of innovative, differentiating flexible and rigid packaging, specialty cartons, closures and services. The company is focused on making packaging that is increasingly recyclable, reusable, lighter weight and made using an increasing amount of recycled content. In fiscal year 2024, 41,000 Amcor people generated $13.6 billion in annual sales from operations that span 212 locations in 40 countries. NYSE: AMCR; ASX: AMC
www.amcor.com I LinkedIn I YouTube
Contact Information
Investors
Tracey Whitehead
Damien Bird
Damon Wright
Global Head of Investor Relations
Vice President Investor Relations Asia Pacific
Vice President Investor Relations North America
Amcor
Amcor
Amcor
+61 408 037 590
+61 481 900 499
+1 224 313 7141
Media – Australia
Media – Europe
Media – North America
James Strong
Ernesto Duran
Julie Liedtke
Managing Director
Head of Global Communications
Director, Media Relations
Sodali & Co
Amcor
Amcor
+61 448 881 174
+41 78 698 69 40
+1 847 204 2319
Amcor plc UK Establishment Address: 83 Tower Road North, Warmley, Bristol, England, BS30 8XP, United Kingdom
UK Overseas Company Number: BR020803
Registered Office: 3rd Floor, 44 Esplanade, St Helier, JE4 9WG, Jersey
Jersey Registered Company Number: 126984, Australian Registered Body Number (ARBN): 630 385 278
Cautionary Statement Regarding Forward-Looking Statements
This document contains certain statements that are “forward-looking statements” within the meaning of the safe harbor provisions of the U.S. Private Securities Litigation Reform Act of 1995. Forward-looking statements are generally identified with words like “believe,” “expect,” “target,” “project,” “may,” “could,” “would,” “approximately,” “possible,” “will,” “should,” “intend,” “plan,” “anticipate,” “commit,” “estimate,” “potential,” “ambitions,” “outlook,” or “continue,” the negative of these words, other terms of similar meaning, or the use of future dates. Such statements, including projections as to the anticipated benefits of the proposed Transaction (as defined herein), the impact of the proposed Transaction on Amcor’s business and future financial and operating results and prospects, and the amount and timing of synergies from the proposed Transaction, are based on the current estimates, assumptions, projections and expectations of the management of Amcor and are qualified by the inherent risks and uncertainties surrounding future expectations generally. Actual results could differ materially from those currently anticipated due to a number of risks and uncertainties many of which are beyond Amcor’s control. Neither Amcor nor any of its respective directors, executive officers, or advisors, provide any representation, assurance, or guarantee that the occurrence of the events expressed or implied in any forward-looking statements will actually occur or if any of them do occur, what impact they will have on the business, results of operations or financial condition of Amcor. Should any risks and uncertainties develop into actual events, these developments could have a material adverse effect on Amcor’s business, the proposed Transaction and the ability to successfully complete the proposed Transaction and realize its expected benefits. Risks and uncertainties that could cause actual results to differ from expectations include, but are not limited to: occurrence of any event, change or other circumstance that could give rise to the termination of the Agreement and Plan of Merger (“Merger Agreement”) in connection with the proposed merger (the “Transaction”) of Amcor and Berry Global Group, Inc. (“Berry”); risk that the conditions to the completion of the proposed Transaction with Berry (including shareholder and regulatory approvals) are not satisfied in a timely manner or at all; risks arising from the integration of the Amcor and Berry businesses; risk that the anticipated benefits of the proposed Transaction may not be realized when expected or at all; risk of unexpected costs or expenses resulting from the proposed Transaction; risk of litigation related to the proposed Transaction; risks related to the disruption of management’s time from ongoing business operations as a result of the proposed Transaction; risk that the proposed Transaction may have an adverse effect on our ability to retain key personnel and customers; general economic, market and social developments and conditions; evolving legal, regulatory and tax regimes under which we operate; potential business uncertainty, including changes to existing business relationships, during the pendency of the proposed Transaction that could affect our financial performance; changes in consumer demand patterns and customer requirements in numerous industries; the loss of key customers, a reduction in their production requirements, or consolidation among key customers; significant competition in the industries and regions in which we operate; an inability to expand our current business effectively through either organic growth, including product innovation, investments, or acquisitions; challenging global economic conditions; impacts of operating internationally; price fluctuations or shortages in the availability of raw materials, energy, and other inputs which could adversely affect our business; production, supply, and other commercial risks, including counterparty credit risks, which may be exacerbated in times of economic volatility; pandemics, epidemics, or other disease outbreaks; an inability to attract and retain our global executive team and our skilled workforce and manage key transitions; labor disputes and an inability to renew collective bargaining agreements at acceptable terms; physical impacts of climate change; cybersecurity risks, which could disrupt our operations or risk of loss of our sensitive business information; failures or disruptions in our information technology systems which could disrupt our operations, compromise customer, employee, supplier, and other data; a significant increase in our indebtedness or a downgrade in our credit rating could reduce our operating flexibility and increase our borrowing costs and negatively affect our financial condition and results of operations; rising interest rates that increase our borrowing costs on our variable rate indebtedness and could have other negative impacts; foreign exchange rate risk; a significant write-down of goodwill and/or other intangible assets; a failure to maintain an effective system of internal control over financial reporting; an inability of our insurance policies, including our use of a captive insurance company, to provide adequate protection against all of the risks we face; an inability to defend our intellectual property rights or intellectual property infringement claims against us; litigation, including product liability claims or litigation related to Environmental, Social, and Governance (“ESG”), matters or regulatory developments; increasing scrutiny and changing expectations from investors, customers, suppliers, and governments with respect to our ESG practices and commitments resulting in additional costs or exposure to additional risks; changing ESG government regulations including climate-related rules; changing environmental, health, and safety laws; changes in tax laws or changes in our geographic mix of earnings; and other risks and uncertainties are supplemented by those identified from time to time in our filings with the Securities and Exchange Commission (the “SEC”), including without limitation, those described under Part I, “Item 1A – Risk Factors” in our Annual Report on Form 10-K for the fiscal year ended June 30, 2024 and as updated by our quarterly reports on Form 10-Q. You can obtain copies of Amcor’s filings with the SEC for free at the SEC’s website (www.sec.gov). Forward-looking statements included herein are made only as of the date hereof and Amcor does not undertake any obligation to update any forward-looking statements, or any other information in this communication, as a result of new information, future developments or otherwise, or to correct any inaccuracies or omissions in them which become apparent, except as expressly required by law. All forward-looking statements in this communication are qualified in their entirety by this cautionary statement.
Presentation of non-GAAP information
Included in this release are measures of financial performance that are not calculated in accordance with U.S. GAAP. These measures include adjusted EBITDA and EBITDA (calculated as earnings before interest and tax and depreciation and amortization), adjusted EBIT and EBIT (calculated as earnings before interest and tax), adjusted net income, adjusted earnings per share, adjusted free cash flow, net debt and synergies from the proposed Transaction. In arriving at these non-GAAP measures, we exclude items that either have a non-recurring impact on the income statement or which, in the judgment of our management, are items that, either as a result of their nature or size, could, were they not singled out, potentially cause investors to extrapolate future performance from an improper base. Note that while amortization of acquired intangible assets is excluded from non-GAAP adjusted financial measures, the revenue of the acquired entities and all other expenses unless otherwise stated, are reflected in our non-GAAP financial performance earnings measures. While not all inclusive, examples of these items include: material restructuring programs, including associated costs such as employee severance, pension and related benefits, impairment of property and equipment and other assets, accelerated depreciation, termination payments for contracts and leases, contractual obligations, and any other qualifying costs related to restructuring plans; material sales and earnings from disposed or ceased operations and any associated profit or loss on sale of businesses or subsidiaries; changes in the fair value of economic hedging instruments on commercial paper and contingent purchase consideration; pension settlements; impairments in goodwill and equity method investments; material acquisition compensation and transaction costs such as due diligence expenses, professional and legal fees, and integration costs; material purchase accounting adjustments for inventory; amortization of acquired intangible assets from business combination; gains or losses on significant property and divestitures and significant property and other impairments, net of insurance recovery; certain regulatory and legal matters; impacts from highly inflationary accounting; expenses related to the Company’s Chief Executive Officer transition; and impacts related to the Russia–Ukraine conflict.
Amcor also evaluates performance on a comparable constant currency basis, which measures financial results assuming constant foreign currency exchange rates used for translation based on the average rates in effect for the comparable prior year period. In order to compute comparable constant currency results, we multiply or divide, as appropriate, current-year U.S. dollar results by the current year average foreign exchange rates and then multiply or divide, as appropriate, those amounts by the prior-year average foreign exchange rates. We then adjust for other items affecting comparability. While not all inclusive, examples of items affecting comparability include the difference between sales or earnings in the current period and the prior period related to disposed, or ceased operations. Comparable constant currency net sales performance also excludes the impact from passing through movements in raw material costs.
Management has used and uses these measures internally for planning, forecasting and evaluating the performance of the Company’s reporting segments and certain of the measures are used as a component of Amcor’s Board of Directors’ measurement of Amcor’s performance for incentive compensation purposes. Amcor believes that these non-GAAP measures are useful to enable investors to perform comparisons of current and historical performance of the Company. For each of these non-GAAP financial measures, a reconciliation to the most directly comparable U.S. GAAP financial measure has been provided herein. These non-GAAP financial measures should not be construed as an alternative to results determined in accordance with U.S. GAAP. The Company provides guidance on a non-GAAP basis as we are unable to predict with reasonable certainty the ultimate outcome and timing of certain significant forward-looking items without unreasonable effort. These items include but are not limited to the impact of foreign exchange translation, restructuring program costs, asset impairments, possible gains and losses on the sale of assets, and certain tax related events. These items are uncertain, depend on various factors, and could have a material impact on U.S. GAAP earnings and cash flow measures for the guidance period.
This document also includes certain projections of non-GAAP financial measures related to the combined company after the consummation of the proposed Transaction. Due to the high variability and difficulty in making accurate forecasts and projections in connection with the results of the combined company after the consummation of the proposed Transaction, together with certain information excluded from these projected non-GAAP financial measures not being ascertainable or accessible, Amcor is unable to quantify certain amounts that would be required to be included in the most directly comparable GAAP financial measures without unreasonable effort. Consequently, no disclosure of estimated comparable GAAP financial measures for such projected non-GAAP financial measures and no reconciliation of projected non-GAAP financial measure for the combined company to directly comparable GAAP measures has been included in this document.
Important Information for Investors and Shareholders
This communication does not constitute an offer to sell or the solicitation of an offer to buy or exchange any securities or a solicitation of any vote or approval in any jurisdiction. It does not constitute a prospectus or prospectus equivalent document. No offering of securities shall be made except by means of a prospectus meeting the requirements of Section 10 of the U.S. Securities Act of 1933, as amended.
In connection with the proposed transaction between Amcor plc (“Amcor”) and Berry Global Group (“Berry”), on January 13, 2025, Amcor filed with the Securities and Exchange Commission (the “SEC”) a registration statement on Form S-4, as amended on January 21, 2025, containing a joint proxy statement of Amcor and Berry that also constitutes a prospectus of Amcor. The registration statement was declared effective by the SEC on January 23, 2025 and Amcor and Berry commenced mailing the definitive joint proxy statement/prospectus to their respective shareholders on or about January 23, 2025. INVESTORS AND SECURITY HOLDERS OF AMCOR AND BERRY ARE URGED TO READ THE DEFINITIVE JOINT PROXY STATEMENT/PROSPECTUS AND OTHER DOCUMENTS FILED OR THAT WILL BE FILED WITH THE SEC CAREFULLY AND IN THEIR ENTIRETY BECAUSE THEY CONTAIN OR WILL CONTAIN IMPORTANT INFORMATION. Investors and security holders may obtain free copies of the registration statement and the definitive joint proxy statement/prospectus and other documents filed with the SEC by Amcor or Berry through the website maintained by the SEC at http://www.sec.gov. Copies of the documents filed with the SEC by Amcor are available free of charge on Amcor’s website at amcor.com under the tab “Investors” and under the heading “Financial Information” and subheading “SEC Filings.” Copies of the documents filed with the SEC by Berry are available free of charge on Berry’s website at berryglobal.com under the tab “Investors” and under the heading “Financials” and subheading “SEC Filings.”
Certain Information Regarding Participants
Amcor, Berry, and their respective directors and executive officers may be considered participants in the solicitation of proxies from the shareholders of Amcor and Berry in connection with the proposed transaction. Information about the directors and executive officers of Amcor is set forth in its Annual Report on Form 10-K for the year ended June 30, 2024, which was filed with the SEC on August 16, 2024, its proxy statement for its 2024 annual meeting, which was filed with the SEC on September 24, 2024, and its Current Report on Form 8-K, which was filed with the SEC on January 6, 2025. Information about the directors and executive officers of Berry is set forth in its Annual Report on Form 10-K for the year ended September 28, 2024, which was filed with the SEC on November 26, 2024, and its proxy statement for its 2025 annual meeting, which was filed with the SEC on January 7, 2025. Information about the directors and executive officers of Amcor and Berry and other information regarding the potential participants in the proxy solicitations and a description of their direct and indirect interests, by security holdings or otherwise, are contained in the definitive joint proxy statement/prospectus filed with the SEC and other relevant materials filed with or to be filed with the SEC regarding the proposed transaction when they become available. To the extent holdings of Amcor’s or Berry’s securities by its directors or executive officers have changed since the amounts set forth in the definitive joint proxy statement/prospectus, such changes have been or will be reflected on Initial Statements of Beneficial Ownership on Form 3 or Statements of Beneficial Ownership on Form 4 filed with the SEC. You may obtain these documents (when they become available) free of charge through the website maintained by the SEC at http://www.sec.gov and from Amcor’s or Berry’s website as described above.
Dividends
Amcor has received a waiver from the ASX’s settlement operating rules, which will allow the Company to defer processing conversions between its ordinary share and CDI registers from February 25, 2025 to February 26, 2025 inclusive.
U.S. GAAP Condensed Consolidated Statements of Income (Unaudited)
Three Months Ended December 31,
Six Months Ended December 31,
($ million)
2023
2024
2023
2024
Net sales
3,251
3,241
6,694
6,594
Cost of sales
(2,630)
(2,615)
(5,428)
(5,309)
Gross profit
621
626
1,266
1,285
Selling, general, and administrative expenses
(299)
(295)
(601)
(610)
Research and development expenses
(28)
(27)
(55)
(55)
Restructuring and other activities, net
(24)
(33)
(52)
(39)
Other income/(expenses), net
(28)
26
(46)
28
Operating income
242
297
512
609
Interest expense, net
(78)
(72)
(153)
(147)
Other non-operating income/(expenses), net
1
(1)
—
(2)
Income before income taxes and equity in
income/(loss) of affiliated companies
165
224
359
460
Income tax expense
(28)
(58)
(67)
(101)
Equity in income/(loss) of affiliated companies, net of tax
(1)
1
(2)
1
Net income
136
167
290
360
Net income attributable to non-controlling interests
(2)
(4)
(4)
(6)
Net income attributable to Amcor plc
134
163
286
354
USD:EUR average FX rate
0.9295
0.9379
0.9244
0.9238
Basic earnings per share attributable to Amcor
0.093
0.113
0.198
0.245
Diluted earnings per share attributable to Amcor
0.092
0.113
0.198
0.244
Weighted average number of shares outstanding –
Basic
1,439
1,443
1,439
1,442
Weighted average number of shares outstanding –
Diluted
1,440
1,446
1,440
1,445
U.S. GAAP Condensed Consolidated Statements of Cash Flows (Unaudited)
Six Months Ended December 31,
($ million)
2023
2024
Net income
290
360
Depreciation, amortization and impairment
295
267
Net gain on disposal of businesses
—
(8)
Changes in operating assets and liabilities, excluding effect of acquisitions, divestitures, and
currency
(445)
(503)
Other non-cash items
88
43
Net cash provided by operating activities
228
159
Purchase of property, plant and equipment and other intangible assets
(245)
(243)
Proceeds from sales of property, plant and equipment and other intangible assets
11
7
Business acquisitions and investments in affiliated companies, and other
(22)
(11)
Proceeds from divestitures, net of cash divested
—
113
Net debt proceeds
257
267
Dividends paid
(361)
(366)
Share buyback/cancellations
(30)
—
Purchase of treasury shares, proceeds from exercise of options and tax withholdings for share-
based incentive plans
(51)
(38)
Other, including effect of exchange rate on cash and cash equivalents
(46)
(31)
Net decrease in cash and cash equivalents
(259)
(143)
Cash and cash equivalents balance at beginning of the year
689
588
Cash and cash equivalents balance at end of the period
430
445
U.S. GAAP Condensed Consolidated Balance Sheets (Unaudited)
($ million)
June 30, 2024
December 31, 2024
Cash and cash equivalents
588
445
Trade receivables, net
1,846
1,775
Inventories, net
2,031
2,126
Property, plant, and equipment, net
3,763
3,629
Goodwill and other intangible assets, net
6,736
6,590
Other assets
1,560
1,600
Total assets
16,524
16,165
Trade payables
2,580
2,380
Short-term debt and current portion of long-term debt
96
104
Long-term debt, less current portion
6,603
6,837
Accruals and other liabilities
3,292
3,053
Shareholders’ equity
3,953
3,791
Total liabilities and shareholders’ equity
16,524
16,165
Components of Fiscal 2025 Net Sales growth
Three Months Ended December 31,
Six Months Ended December 31,
($ million)
Flexibles
Rigid
Packaging
Total
Flexibles
Rigid
Packaging
Total
Net sales fiscal 2025
2,511
730
3,241
5,062
1,532
6,594
Net sales fiscal 2024
2,481
770
3,251
5,049
1,645
6,694
Reported Growth %
1
(5)
—
—
(7)
(1)
FX %
(1)
(2)
(1)
(1)
(2)
(1)
Constant Currency Growth %
2
(3)
1
1
(5)
(1)
RM Pass Through %
1
(2)
1
1
(2)
—
Items affecting comparability %
—
—
—
—
—
—
Comparable Constant Currency Growth %
1
(1)
—
—
(3)
(1)
Acquired operations %
—
—
—
—
—
—
Organic Growth %
1
(1)
—
—
(3)
(1)
Volume %
3
1
2
3
(2)
2
Price/Mix %
(2)
(2)
(2)
(3)
(1)
(3)
Reconciliation of Non-GAAP Measures
Reconciliation of adjusted Earnings before interest, tax, depreciation, and amortization (EBITDA), Earnings before interest and tax (EBIT), Net income, Earnings per share (EPS) and Adjusted Free Cash Flow
Three Months Ended December 31, 2023
Three Months Ended December 31, 2024
($ million)
EBITDA
EBIT
Net
Income
EPS
(Diluted
US
cents)(1)
EBITDA
EBIT
Net
Income
EPS
(Diluted
US
cents)
Net income attributable to Amcor
134
134
134
9.2
163
163
163
11.3
Net income attributable to non-controlling
interests
2
2
4
4
Tax expense
28
28
58
58
Interest expense, net
78
78
72
72
Depreciation and amortization
145
130
EBITDA, EBIT, Net income, and EPS
387
242
134
9.2
427
297
163
11.3
Impact of highly inflationary accounting
34
34
34
2.4
3
3
3
0.2
Restructuring and related expenses, net(2)
24
24
24
1.7
23
23
23
1.6
Other
9
9
9
0.6
—
—
—
—
Amortization of acquired intangibles(3)
43
43
3.0
40
40
2.8
Tax effect of above items
(17)
(1.2)
4
0.2
Adjusted EBITDA, EBIT, Net income and EPS
454
352
227
15.7
453
363
233
16.1
Reconciliation of adjusted growth to comparable constant currency growth
% growth – Adjusted EBITDA, EBIT, Net income, and EPS
—
3
3
3
% items affecting comparability
—
—
—
—
% currency impact
2
2
2
2
% comparable constant currency growth
2
5
5
5
Adjusted EBITDA
454
453
Interest paid, net
(94)
(91)
Income tax paid
(71)
(52)
Purchase of property, plant and equipment and
other intangible assets
(121)
(98)
Proceeds from sales of property, plant and
equipment and other intangible assets
7
6
Movement in working capital
60
153
Other
44
(13)
Adjusted Free Cash Flow
279
358
(1) Calculation of diluted EPS for the three months ended December 31, 2023 excludes net income attributable to shares to be repurchased under forward contracts of $1 million.
(2) Includes incremental restructuring and related expenses attributable to group wide initiatives to partly offset divested earnings from the Russian business.
(3) Amortization of acquired intangible assets from business combinations.
Six Months Ended December 31, 2023
Six Months Ended December 31, 2024
($ million)
EBITDA
EBIT
Net
Income
EPS
(Diluted
US
cents)(1)
EBITDA
EBIT
Net
Income
EPS
(Diluted
US
cents)(1)
Net income attributable to Amcor
286
286
286
19.8
354
354
354
24.4
Net income attributable to non-controlling
interests
4
4
6
6
Tax expense
67
67
101
101
Interest expense, net
153
153
147
147
Depreciation and amortization
287
270
EBITDA, EBIT, Net income, and EPS
797
510
286
19.8
878
608
354
24.4
Impact of highly inflationary accounting
51
51
51
3.6
5
5
5
0.4
Restructuring and related expenses, net(2)
52
52
52
3.6
29
29
29
2.0
Other
13
13
13
0.8
7
7
7
0.4
Amortization of acquired intangibles(3)
83
83
5.8
79
79
5.5
Tax effect of above items
(32)
(2.3)
(7)
(0.5)
Adjusted EBITDA, EBIT, Net income and EPS
913
709
453
31.3
919
728
467
32.2
Reconciliation of adjusted growth to comparable constant currency growth
% growth – Adjusted EBITDA, EBIT, Net income, and EPS
1
3
3
3
% items affecting comparability
—
—
—
—
% currency impact
1
1
2
2
% comparable constant currency growth
2
4
5
5
Adjusted EBITDA
913
919
Interest paid, net
(141)
(127)
Income tax paid
(124)
(127)
Purchase of property, plant and equipment and
other intangible assets
(245)
(243)
Proceeds from sales of property, plant and
equipment and other intangible assets
11
7
Movement in working capital
(400)
(433)
Other
38
(34)
Adjusted Free Cash Flow
52
(38)
(1) Calculation of diluted EPS for the six months ended December 31, 2024 excludes net income attributable to shares to be repurchased under forward contracts of $1 million. Calculation of diluted EPS for the six months ended December 31, 2023 excludes net income attributable to shares to be repurchased under forward contracts of $1 million.
(2) Includes incremental restructuring and related expenses attributable to group wide initiatives to partly offset divested earnings from the Russian business.
(3) Amortization of acquired intangible assets from business combinations.
Reconciliation of adjusted EBIT by reportable segment
Three Months Ended December 31, 2023
Three Months Ended December 31, 2024
($ million)
Flexibles
Rigid
Packaging
Other
Total
Flexibles
Rigid
Packaging
Other
Total
Net income attributable to Amcor
134
163
Net income attributable to non-
controlling interests
2
4
Tax expense
28
58
Interest expense, net
78
72
EBIT
250
11
(19)
242
259
62
(24)
297
Impact of highly inflationary
accounting
—
34
—
34
—
3
—
3
Restructuring and related expenses,
net(1)
19
5
—
24
23
—
—
23
Other(2)
1
—
8
9
3
(14)
11
—
Amortization of acquired intangibles(3)
42
1
—
43
37
2
1
40
Adjusted EBIT
312
51
(11)
352
322
53
(12)
363
Adjusted EBIT / sales %
12.6 %
6.6 %
10.8 %
12.8 %
7.3 %
11.2 %
Reconciliation of adjusted growth to comparable constant currency growth
% growth – Adjusted EBIT
3
5
—
3
% items affecting comparability
—
—
—
—
% currency impact
1
5
—
2
% comparable constant currency
4
10
—
5
(1) Includes incremental restructuring and related expenses attributable to group wide initiatives to partly offset divested earnings from the Russian business.
(2) For the three months ended December 31, 2024, includes pre-tax gains and losses on the disposal of certain assets in the Flexibles and Rigid Packaging segments and transaction costs related to the announced Merger with Berry Global in Other.
(3) Amortization of acquired intangible assets from business combinations.
Six Months Ended December 31, 2023
Six Months Ended December 31, 2024
($ million)
Flexibles
Rigid
Packaging
Other
Total
Flexibles
Rigid
Packaging
Other
Total
Net income attributable to Amcor
286
354
Net income attributable to non-
controlling interests
4
6
Tax expense
67
101
Interest expense, net
153
147
EBIT
506
51
(47)
510
539
121
(52)
608
Impact of highly inflationary
accounting
—
51
—
51
—
5
—
5
Restructuring and related expenses,
net(1)
43
9
—
52
29
—
—
29
Other
4
—
9
13
9
(14)
12
7
Amortization of acquired intangibles(2)
81
2
—
83
74
3
2
79
Adjusted EBIT
634
113
(38)
709
651
115
(38)
728
Adjusted EBIT / sales %
12.6 %
6.9 %
10.6 %
12.9 %
7.5 %
11.0 %
Reconciliation of adjusted growth to comparable constant currency growth
% growth – Adjusted EBIT
3
2
—
3
% items affecting comparability
—
—
—
—
% currency impact
1
4
—
1
% comparable constant currency
4
6
—
4
(1) Includes incremental restructuring and related expenses attributable to group wide initiatives to partly offset divested earnings from the Russian business.
(2) Amortization of acquired intangible assets from business combinations.
Reconciliation of net debt
($ million)
June 30, 2024
December 31, 2024
Cash and cash equivalents
(588)
(445)
Short-term debt
84
91
Current portion of long-term debt
12
13
Long-term debt, less current portion
6,603
6,837
Net debt
6,111
6,496
View original content:https://www.prnewswire.com/news-releases/amcor-reports-second-quarter-and-first-half-result-reaffirms-fiscal-2025-outlook-302367319.html
SOURCE Amcor

You may like
Technology
Dan Gilbert Makes Historic Gift to Detroit, Pledges $1 Billion to Create New Nonprofit to Transform Detroit’s Renaissance Center and East Riverfront
Published
57 minutes agoon
October 19, 2026By
A new nonprofit will redevelop, own and operate the landmark and surrounding east riverfront district, with all surplus proceeds invested in the community
DETROIT, Oct. 19, 2026 /PRNewswire/ — Dan Gilbert, founder and chairman of Rocket Companies and Bedrock, today pledged approximately $1 billion in development capital to form a new nonprofit organization that will redevelop, own and operate the Renaissance Center and surrounding east riverfront district.
As a result of this philanthropic gift, believed to be the largest contribution to a non-profit redevelopment initiative in the history of American cities, Gilbert and his companies will receive no profits from the redevelopment of the Renaissance Center and 35-acre waterfront district. Gilbert’s contribution will not be repaid.
The nonprofit will develop, own and operate the property for civic betterment, guided by the dual missions of community benefit and long-term sustainability. After completion of the project, revenue will first cover operating expenses, debt payments, reserves and necessary reinvestment in the properties over time. Any surplus funds will go to support Detroiters and the community.
“The Renaissance Center is a symbol of Detroit, and the riverfront is one of Detroit’s most treasured assets,” said Gilbert. “We all share the goals of bringing new life to the Renaissance Center, of building a thriving riverfront district for all to enjoy, and of maximizing positive community impact. I cannot think of better way to accomplish these goals than through a nonprofit organization dedicated to this mission in perpetuity.”
This new pledge builds on Gilbert’s long history of philanthropic support for Detroit.
In 2021, the Gilbert Family Foundation and Rocket Community Fund announced a $500 million, 10-year commitment to strengthen Detroit neighborhoods. Through the end of 2025, the organizations have invested more than $100 million in housing stability, including efforts to prevent foreclosure and eviction, repair homes and expand homeownership. Another $183 million has been invested to support small businesses, expand economic opportunity, and support neighborhood parks, the arts and community spaces. Together, the organizations have invested nearly $300 million of the initial commitment, putting them ahead of pace toward their goal.
In 2023, Gilbert Family Foundation committed nearly $375 million to bring Shirley Ryan AbilityLab, the top rehabilitative care center in the nation, to Detroit and to establish the Nick Gilbert Neurofibromatosis Research Institute. These projects are part of Henry Ford Health’s Future of Health, a transformational campus expansion in Detroit’s New Center neighborhood. In addition to these philanthropic gifts, his family office, ROCK, has invested millions in Detroit and Cleveland.
This new organization will extend Gilbert’s philanthropic commitments to Detroit’s waterfront. The vision includes transforming the Renaissance Center and surrounding 35-acre district, now consisting largely of surface parking lots, into the best, broadly accessible, family-friendly waterfront destination in the country—providing a series of new amenities for Detroiters and creating a new engine of tourism and growth for the city. The redevelopment will include affordable housing, dedicated space for Detroit-based small businesses, and 18-acres of programmed and publicly accessible civic space. It is anticipated to create more than 8,000 local construction jobs and 2,600 permanent jobs. The 30-year direct fiscal benefit to the City of Detroit is estimated to be $301.5 million, and on top of that, the district is anticipated to generate $3.03 billion in new visitor spend for the city over the same period.
“What Dan Gilbert is announcing today is truly historic,” said Detroit Mayor Mary Sheffield. “This was already the largest, most transformative investment ever pledged in Detroit and one of the largest ever in any American city. For Dan to make a billion-dollar investment – and to guarantee that only the city and its people can benefit – truly shows the depth of his generosity and of his commitment to Detroit.”
The nonprofit will be structured as a 501(c)(4) social welfare organization focused on civic improvement and community well-being. Reverend Dr. Wendell Anthony, president of the Detroit Branch of the NAACP, will serve on the inaugural Board of Directors and help lead recruitment of a diverse and experienced board to oversee the nonprofit. Bill Emerson, former CEO of Rocket Companies and member of several of the region’s most prominent non-profit boards, will also serve on the board to help lead the organization through its formative stages.
Bedrock will provide project management services to the nonprofit at no cost, bringing its expertise and continuity to the redevelopment project.
“The day has come and a new era has begun. The Iconic Renaissance Center will serve as a historic marker now reimagined and reinvented into what I like to call Renaissance II,” said Reverend Dr. Anthony. This is a historic, unprecedented and never before witnessed in any community pledge that has now been made. Dan Gilbert is openly establishing a new model for community development not only for Detroit but for cities across the nation. This is a true legacy cemented in the soil of Detroit by a true Philanthropist.”
The announcement builds on General Motors’ 2024 commitment to donate any profits it receives from the redevelopment toward education in Detroit. Additional details about the nonprofit will be announced as further steps are taken in its formation. Contributions to 501(c)(4) organizations are not deductible as charitable contributions for federal income tax purposes.
“Dan Gilbert has played an essential role in the continued revitalization of Detroit and its downtown, and this new organization is the latest example of his deep and lasting commitment to our city,” said General Motors President Mark Reuss. “It will build upon the progress GM has already made in helping create the #1 ranked riverwalk in the nation and will set up the east riverfront for long-term success to be enjoyed by citizens and visitors alike for generations to come.”
About the Renaissance Center and East Riverfront Project
The redevelopment of the iconic Renaissance Center represents of the most complex and consequential adaptive reuse projects ever undertaken, combined with one of the nation’s most ambitious community-driven waterfront redevelopment initiatives. The $2.2 billion development plan includes the reimagination of the Renaissance Center and the comprehensive transformation of the 35-acre east riverfront district, consisting primarily of vacant surface parking lots, with the goal of creating the best, broadly accessible, family-friendly waterfront destination in the country. More information about the Renaissance Center and east riverfront project may be found at DRF.dev.
View original content to download multimedia:https://www.prnewswire.com/news-releases/dan-gilbert-makes-historic-gift-to-detroit-pledges-1-billion-to-create-new-nonprofit-to-transform-detroits-renaissance-center-and-east-riverfront-302912867.html
SOURCE ROCK
Technology
Dan Gilbert Makes Historic Gift to Detroit, Pledges $1 Billion to Create New Nonprofit to Transform Detroit’s Renaissance Center and East Riverfront
Published
57 minutes agoon
October 19, 2026By
A new nonprofit will redevelop, own and operate the landmark and surrounding east riverfront district, with all surplus proceeds invested in the community
DETROIT, Oct. 19, 2026 /PRNewswire/ — Dan Gilbert, founder and chairman of Rocket Companies and Bedrock, today pledged approximately $1 billion in development capital to form a new nonprofit organization that will redevelop, own and operate the Renaissance Center and surrounding east riverfront district.
As a result of this philanthropic gift, believed to be the largest contribution to a non-profit redevelopment initiative in the history of American cities, Gilbert and his companies will receive no profits from the redevelopment of the Renaissance Center and 35-acre waterfront district. Gilbert’s contribution will not be repaid.
The nonprofit will develop, own and operate the property for civic betterment, guided by the dual missions of community benefit and long-term sustainability. After completion of the project, revenue will first cover operating expenses, debt payments, reserves and necessary reinvestment in the properties over time. Any surplus funds will go to support Detroiters and the community.
“The Renaissance Center is a symbol of Detroit, and the riverfront is one of Detroit’s most treasured assets,” said Gilbert. “We all share the goals of bringing new life to the Renaissance Center, of building a thriving riverfront district for all to enjoy, and of maximizing positive community impact. I cannot think of better way to accomplish these goals than through a nonprofit organization dedicated to this mission in perpetuity.”
This new pledge builds on Gilbert’s long history of philanthropic support for Detroit.
In 2021, the Gilbert Family Foundation and Rocket Community Fund announced a $500 million, 10-year commitment to strengthen Detroit neighborhoods. Through the end of 2025, the organizations have invested more than $100 million in housing stability, including efforts to prevent foreclosure and eviction, repair homes and expand homeownership. Another $183 million has been invested to support small businesses, expand economic opportunity, and support neighborhood parks, the arts and community spaces. Together, the organizations have invested nearly $300 million of the initial commitment, putting them ahead of pace toward their goal.
In 2023, Gilbert Family Foundation committed nearly $375 million to bring Shirley Ryan AbilityLab, the top rehabilitative care center in the nation, to Detroit and to establish the Nick Gilbert Neurofibromatosis Research Institute. These projects are part of Henry Ford Health’s Future of Health, a transformational campus expansion in Detroit’s New Center neighborhood. In addition to these philanthropic gifts, his family office, ROCK, has invested millions in Detroit and Cleveland.
This new organization will extend Gilbert’s philanthropic commitments to Detroit’s waterfront. The vision includes transforming the Renaissance Center and surrounding 35-acre district, now consisting largely of surface parking lots, into the best, broadly accessible, family-friendly waterfront destination in the country—providing a series of new amenities for Detroiters and creating a new engine of tourism and growth for the city. The redevelopment will include affordable housing, dedicated space for Detroit-based small businesses, and 18-acres of programmed and publicly accessible civic space. It is anticipated to create more than 8,000 local construction jobs and 2,600 permanent jobs. The 30-year direct fiscal benefit to the City of Detroit is estimated to be $301.5 million, and on top of that, the district is anticipated to generate $3.03 billion in new visitor spend for the city over the same period.
“What Dan Gilbert is announcing today is truly historic,” said Detroit Mayor Mary Sheffield. “This was already the largest, most transformative investment ever pledged in Detroit and one of the largest ever in any American city. For Dan to make a billion-dollar investment – and to guarantee that only the city and its people can benefit – truly shows the depth of his generosity and of his commitment to Detroit.”
The nonprofit will be structured as a 501(c)(4) social welfare organization focused on civic improvement and community well-being. Reverend Dr. Wendell Anthony, president of the Detroit Branch of the NAACP, will serve on the inaugural Board of Directors and help lead recruitment of a diverse and experienced board to oversee the nonprofit. Bill Emerson, former CEO of Rocket Companies and member of several of the region’s most prominent non-profit boards, will also serve on the board to help lead the organization through its formative stages.
Bedrock will provide project management services to the nonprofit at no cost, bringing its expertise and continuity to the redevelopment project.
“The day has come and a new era has begun. The Iconic Renaissance Center will serve as a historic marker now reimagined and reinvented into what I like to call Renaissance II,” said Reverend Dr. Anthony. This is a historic, unprecedented and never before witnessed in any community pledge that has now been made. Dan Gilbert is openly establishing a new model for community development not only for Detroit but for cities across the nation. This is a true legacy cemented in the soil of Detroit by a true Philanthropist.”
The announcement builds on General Motors’ 2024 commitment to donate any profits it receives from the redevelopment toward education in Detroit. Additional details about the nonprofit will be announced as further steps are taken in its formation. Contributions to 501(c)(4) organizations are not deductible as charitable contributions for federal income tax purposes.
“Dan Gilbert has played an essential role in the continued revitalization of Detroit and its downtown, and this new organization is the latest example of his deep and lasting commitment to our city,” said General Motors President Mark Reuss. “It will build upon the progress GM has already made in helping create the #1 ranked riverwalk in the nation and will set up the east riverfront for long-term success to be enjoyed by citizens and visitors alike for generations to come.”
About the Renaissance Center and East Riverfront Project
The redevelopment of the iconic Renaissance Center represents of the most complex and consequential adaptive reuse projects ever undertaken, combined with one of the nation’s most ambitious community-driven waterfront redevelopment initiatives. The $2.2 billion development plan includes the reimagination of the Renaissance Center and the comprehensive transformation of the 35-acre east riverfront district, consisting primarily of vacant surface parking lots, with the goal of creating the best, broadly accessible, family-friendly waterfront destination in the country. More information about the Renaissance Center and east riverfront project may be found at DRF.dev.
View original content to download multimedia:https://www.prnewswire.com/news-releases/dan-gilbert-makes-historic-gift-to-detroit-pledges-1-billion-to-create-new-nonprofit-to-transform-detroits-renaissance-center-and-east-riverfront-302912867.html
SOURCE ROCK
Technology
TilePix Expands into Select Walmart Stores Nationwide with New Nail-Free Wall Décor Frames & Accessories
Published
57 minutes agoon
October 19, 2026By
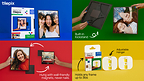
TilePix’s first-ever in-store launch introduces new TilePix frame sizes and the Super Nail hanging solution, alongside the Walmart-exclusive 6×6 TilePix Mini launch
NEW YORK, Oct. 19, 2026 /PRNewswire/ — TilePix, the magnetic, nail-free wall décor brand, today announces its first nationwide in-store product launch at Walmart. Now rolling out on Walmart.com and in select stores across the U.S., the expanded assortment of TilePix wall décor and hanging products begin hitting shelves on October 19th, with the full in-store rollout expected to be complete by the end of October. The launch marks a major expansion of TilePix’s retail presence.
The launch brings three new additions to Walmart shoppers:
TilePix blank magnetic frames in 8×10, 11×14 and 12×12 sizesThe Super Nail by TilePix, a new universal nail-free hanging solution for frames up to three poundsThe TilePix Mini, a new Walmart-exclusive 6×6 magnetic photo tile
For the first time, Walmart customers can purchase TilePix’s new 8×10, 11×14 and 12×12 blank magnetic frames on store shelves in addition to the online assortment to open and add their own photos, artwork or designs. Customers can even print photos through Walmart Photo and create a custom gallery wall in one trip. Each frame uses TilePix’s magnetic backers, allowing consumers to peel, stick and hang TilePix frames without nails, tools or wall damage. As always, the brand’s re-stickable magnetic wall pads make TilePix easy to move, swap and rearrange. The new blank frames also all come with a built-in kickstand, giving consumers the option to display each frame on a wall or tabletop.
Also making its debut at Walmart is The Super Nail by TilePix, a universal nail-free hanging solution designed to hold virtually any small picture frame or lightweight wall art up to three pounds. TilePix’s Super Nail attaches to the wall through a peel-and-stick application and features an adjustable hanger that lets users shift frame placement without starting over. Its slim design stays hidden behind the frame, giving consumers the flexibility to straighten, reposition and restyle their wall décor without traditional nails or tools. Available in one or two-pack options, the Super Nail brings the innovation behind TilePix’s traditional frames to any frame 3 pounds or lighter.
Finally, this month, TilePix introduces its smallest frame yet, the TilePix Mini is a 6×6 photo tile, hung nail-free with magnets, available exclusively at Walmart. The smaller format brings the flexibility of TilePix to a new scale, making it easy to turn favorite photos and memories into nail-free wall displays in bedrooms, dorms, apartments, kids’ rooms and smaller spaces.
“This nationwide expansion with Walmart marks a pivotal moment for Tracer as we evolve TilePix from a standalone magnetic tile into a full nail-free wall décor ecosystem,” says Tracer Imaging CEO and Founder Steven Spiro. “Whether framing a print, hanging existing art with the Super Nail, or styling a space with the new TilePix Mini, we are eliminating the friction of traditional home décor and making personalized design accessible to everyone.”
The Walmart expansion comes ahead of the 2026 holiday season, giving shoppers new ways to personalize their homes and gift their favorite memories. TilePix will support the launch with a holiday campaign centered on DIY creativity, product education and style-driven inspiration, showing how consumers can use the new assortment to make their walls feel more personal without making their decorating decisions permanent.
The Walmart launch marks a major next step for TilePix: not only is the brand available at retail, but it’s moving beyond its original magnetic photo tiles and into a broader ecosystem of flexible wall décor and hanging solutions. Whether consumers are creating a personalized gallery wall with TilePix frames, hanging an existing frame with the Super Nail or building a display with the new TilePix Mini, each product is designed around the same idea: your walls should be as easy to change as your style.
Beginning October 19th, TilePix 8×10, 11×14 and 12×12 blank magnetic frames and TilePix Super Nail will be available on shelves at more than 3,000 Walmart stores nationwide. The TilePix Mini, the new Walmart-exclusive 6×6 magnetic photo tile, will be available through Walmart.com and on in-store kiosks for shipping and in-store pickup.
For more information, visit Walmart’s dedicated TilePix page HERE.
GET SOCIAL WITH US:
Instagram: @tile.pix @walmart
TikTok: @tilepix @walmart
MEDIA CONTACTS:
Sabrina Levine Communications
Nicole Waldman | nicole@sabrinalevinepr.com | (805) 404-8152
Maxie Katsikas | maxie@sabrinalevinepr.com | (917) 991-3750
ABOUT TILEPIX
TilePix is a wall décor brand making it easier to personalize, hang and rearrange walls without nails, tools or damage. Launched in 2022, TilePix is best known for its patented magnetic hanging system, which allows consumers to peel, stick, hang and rearrange their wall décor as their spaces and styles change.
TilePix offers customizable photo tiles, magnetic frames and other wall décor products designed to make decorating more flexible and personal. The brand also partners with artists and designers, including Jonathan Adler, to bring curated artwork to its growing wall décor assortment.
TilePix is a brand of Tracer Imaging, a photo and printing company with more than 20 years of experience developing products and technology for major retailers.
View original content to download multimedia:https://www.prnewswire.com/news-releases/tilepix-expands-into-select-walmart-stores-nationwide-with-new-nail-free-wall-decor-frames–accessories-302912883.html
SOURCE TilePix


Dan Gilbert Makes Historic Gift to Detroit, Pledges $1 Billion to Create New Nonprofit to Transform Detroit’s Renaissance Center and East Riverfront
Dan Gilbert Makes Historic Gift to Detroit, Pledges $1 Billion to Create New Nonprofit to Transform Detroit’s Renaissance Center and East Riverfront

TilePix Expands into Select Walmart Stores Nationwide with New Nail-Free Wall Décor Frames & Accessories

Send Rakhi to UK swiftly with UK Gifts Portal

Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

Nullmax and Renesas Forge Strategic Partnership to Deliver Competitive ADAS Solutions for the Global Market

Why You Should Build on #NEAR – Co-founder Illia Polosukhin at CV Labs
Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

NEAR End of Year Town Hall 2021: The Open Web World, MetaBUILD 2 Hackathon and 2021 recap
Trending
-
 Coin Market5 days ago
Organizations join forces to fight Illinois crypto tax, after 6-month pause
-
 Coin Market5 days ago
EU authority classifies Circle’s USDC as ‘significant’ under MiCA
-
 Technology5 days ago
Carrier Logistics and LSP44 Join Forces to Solve AI Bot Fatigue
-
 Technology5 days ago
How The Mobile Robot Company is Upending Logistics by Stopping at 80% Automation
-
 Technology5 days ago
Ricoh and ETRIA launch “Circular New,” a manufacturing concept, turning resource circulation into competitive advantage
-
 Technology5 days ago
Payoneer Checkout Launches in Singapore, Helping Businesses Turn Global Demand into Revenue
-
 Coin Market5 days ago
Polygon gains US payments licenses after closing Coinme deal
-

 Coin Market3 days ago
OpenAI model helped itself to testnet crypto, then kept quiet about it