Connect with us

Technology

Fleet Management Market to Grow by USD 52.23 Billion by 2029, Driven by E-Commerce and Last-Mile Delivery, Report on AI-Powered Market Evolution – Technavio

Published

on

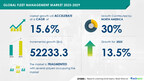
NEW YORK, Feb. 5, 2025 /PRNewswire/ — Report on how AI is driving market transformation – The global fleet management market size is estimated to grow by USD 52.23 billion from 2025-2029, according to Technavio. The market is estimated to grow at a CAGR of  15.6%  during the forecast period. Rise in e-commerce and last-mile delivery is driving market growth, with a trend towards increasing adoption of telematics and autonomous vehicle. However, issues in gps connectivity  poses a challenge. Key market players include AT and T Inc., Avrios International AG, Bridgestone Corp., Chevin Fleet Solutions, Donlen Corp., Element Fleet Management Corp., Fleetio, Geotab Inc., GPS Insight, GURTAM, Holman Inc., MiX Telematics Ltd., Motive Technologies Inc., NetraDyne Inc., Samsara Inc., Solera Holdings LLC, JSC Teltonika, TomTom NV, Trimble Inc., Verizon Communications Inc., Via Transportation Inc., and Vontier Corp..

Key insights into market evolution with AI-powered analysis. Explore trends, segmentation, and growth drivers- View Free Sample PDF

Fleet Management Market Scope

Report Coverage

Details

Base year

2024

Historic period

2019 – 2023

Forecast period

2025-2029

Growth momentum & CAGR

Accelerate at a CAGR of 15.6%

Market growth 2025-2029

USD 52233.3 million

Market structure

Fragmented

YoY growth 2022-2023 (%)

13.5

Regional analysis

North America, Europe, APAC, South America, and Middle East and Africa

Performing market contribution

North America at 30%

Key countries

US, China, Germany, UK, Japan, Canada, India, South Korea, France, and Italy

Key companies profiled

AT and T Inc., Avrios International AG, Bridgestone Corp., Chevin Fleet Solutions, Donlen Corp., Element Fleet Management Corp., Fleetio, Geotab Inc., GPS Insight, GURTAM, Holman Inc., MiX Telematics Ltd., Motive Technologies Inc., NetraDyne Inc., Samsara Inc., Solera Holdings LLC, JSC Teltonika, TomTom NV, Trimble Inc., Verizon Communications Inc., Via Transportation Inc., and Vontier Corp.

Market Driver

Fleet management is a crucial aspect of transportation and logistics industries, helping fleet owners and managers optimize operational efficiency and reduce overhead costs. Trends in fleet management include routing and navigation solutions using GPS connectivity from services like Google Maps and satellites. Vehicle security and driver safety are key concerns, with fleet management solutions offering real-time visibility, geofencing, scheduling, and advanced routing. Fuel costs are a significant expense, with fleet management tools providing fuel management and maintenance scheduling. Fleet size and logistic providers benefit from fleet performance analysis, inventory storage, and warehouse systems. The fleet management market continues to grow with the integration of technology, such as the Internet of Things, autonomous vehicles, and 5G deployment. Fleet operators in freight and logistics face the challenges of managing commercial vehicles, light and heavy, and must comply with federal rules like electronic logging and the use of electronic logging devices. Fleet management systems offer hardware, software, and service options, including on-premises and cloud solutions, to meet the diverse needs of transportation enterprises. 

The telematics industry took off with the advent of 2G telecommunication systems and GPS positioning, enabling the sharing of vehicle location details. Initially, GPS-based navigation systems became mandatory for commercial vehicles worldwide. The emergence of electric and hybrid vehicles, as well as self-driving cars, will boost investments in sensors, connectivity devices, and network components. Autonomous vehicles rely on extensive semiconductor components like sensors and integrated circuits for navigation. These vehicles obtain information from a connected car network and IoT to operate effectively. 

Request Sample of our comprehensive report now to stay ahead in the AI-driven market evolution!

 Market Challenges

•         Fleet management is a crucial aspect of transportation and logistics industries, helping fleet managers optimize operational efficiency and ensure safety for their vehicles and drivers. Challenges include routing, vehicle security, driver safety, fleet performance, fuel costs, and overhead costs. Fleet management solutions use GPS connectivity and navigation services like Google Maps to provide real-time visibility, optimize routes, and track vehicles. However, natural barriers like satellite signal interference and GPS signal loss can impact performance. Fleet owners face challenges in managing large fleets, from commercial vehicles to connected trucks and containers. Fleet management tools offer fuel management, maintenance management, and driver management solutions. The fleet management market continues to evolve with advancements in technology, including automation, the Internet of Things, and 5G deployment. Asset management systems and financial tracking solutions are essential for fleet operators to manage costs and improve performance. Fleet management software, available on-premises or in the cloud, offers features like geocoding, fleet routing, route optimization algorithm, fleet tracking, geofencing, scheduling, and real-time visibility. Electronic logging and electronic logging devices help comply with federal rules. Vehicle leasing companies and allied carriers also benefit from fleet management solutions to optimize their operations during peak seasons like the holiday shopping season.

•         The global fleet management market relies heavily on connectivity for real-time tracking and monitoring of vehicles. Satellite and cellular communication networks are utilized to determine a vehicle’s location, speed, and direction. However, connectivity issues pose a significant challenge. In some regions, such as developing countries and remote areas, high-speed Internet and reliable cellular connectivity may not be readily available. Suburban areas and highways can also experience weak cellular connectivity. These situations can hinder the effectiveness of fleet management systems, making it crucial for providers to address and mitigate connectivity issues to ensure seamless operations.

Discover how AI is revolutionizing market trends- Get your access now!

Segment Overview 

This fleet management market report extensively covers market segmentation by  

TypeSubscriptionOthersVehicle TypeCommercial FleetPassenger CarGeographyNorth AmericaEuropeAPACSouth AmericaMiddle East And AfricaCommunication TechnologyGNSSCellular System

1.1 Subscription-  Subscription-based fleet management solutions offer businesses flexibility and predictability in managing their commercial fleets and personal vehicles. With these models, businesses can easily adjust their service plans based on their current needs as their fleet size grows or changes. The subscription plans provide consistent costs, simplifying financial planning and managing cash flow. Cloud-based solutions require minimal hardware setup for quick deployment and access to regular updates, new features, and improvements without additional costs. Subscription models often include integrated features such as GPS tracking, telematics, fuel management, and maintenance tracking, streamlining fleet management processes. Vendors like Azuga Inc. Provide subscription-based fleet tracking apps with real-time functions, sync with fleet management software, and customizable access levels for unlimited users. The growing demand for efficient fleet management and optimization increases the market potential for subscription-based solutions, making it a significant growth driver for the global fleet management market.

Download a Sample of our comprehensive report today to discover how AI-driven innovations are reshaping competitive dynamics

Research Analysis

Fleet management is a critical aspect of operating and maintaining commercial vehicles, encompassing a range of solutions to optimize fleet performance, reduce overhead costs, and ensure driver safety and vehicle security. Fleet managers oversee the day-to-day operations of fleet vehicles, including routing, fuel management, maintenance management, and driver management. Fleet owners utilize fleet management tools, such as GPS connectivity and fleet management software, to monitor distance traveled, fuel costs, driver behavior, and vehicle performance in real-time. The integration of IoT, automation, and connected vehicles is revolutionizing fleet management, enabling advanced features like weight/volume tracking, autonomous vehicles, and real-time maintenance alerts. Freight and logistics operators also benefit from these solutions to streamline their operations and enhance productivity.

Market Research Overview

Fleet management solutions play a crucial role in optimizing the efficiency and productivity of fleet operations for fleet owners and managers in the transportation and logistics industry. These solutions encompass various aspects such as routing, vehicle security, driver safety, and fleet performance. Routing and navigation services, including GPS connectivity, Google Maps, and satellite technology, enable real-time location tracking and advanced route optimization algorithms. Fleet management tools also provide insights into fuel costs, distance traveled, driver behavior, and overhead costs. Additionally, fleet management systems offer maintenance management, driver management, fuel management, and asset management solutions for commercial vehicles, including light and heavy commercial vehicles. The market for fleet management solutions is growing rapidly, driven by the increasing adoption of connected vehicles, automation, and the Internet of Things (IoT) in the transportation and logistics industry. Fleet operators, logistics providers, freight and logistics companies, and vehicle leasing companies all benefit from these advanced fleet management tools to enhance operational efficiency, safety, and financial performance. The holiday shopping season and 5G deployment are expected to further boost the demand for fleet management solutions in the coming years.

Table of Contents:

1 Executive Summary
2 Market Landscape
3 Market Sizing
4 Historic Market Size
5 Five Forces Analysis
6 Market Segmentation

TypeSubscriptionOthersVehicle TypeCommercial FleetPassenger CarGeographyNorth AmericaEuropeAPACSouth AmericaMiddle East And AfricaCommunication TechnologyGNSSCellular System

7 Customer Landscape
8 Geographic Landscape
9 Drivers, Challenges, and Trends
10 Company Landscape
11 Company Analysis
12 Appendix

About Technavio

Technavio is a leading global technology research and advisory company. Their research and analysis focuses on emerging market trends and provides actionable insights to help businesses identify market opportunities and develop effective strategies to optimize their market positions.

With over 500 specialized analysts, Technavio’s report library consists of more than 17,000 reports and counting, covering 800 technologies, spanning across 50 countries. Their client base consists of enterprises of all sizes, including more than 100 Fortune 500 companies. This growing client base relies on Technavio’s comprehensive coverage, extensive research, and actionable market insights to identify opportunities in existing and potential markets and assess their competitive positions within changing market scenarios.

Contacts

Technavio Research
Jesse Maida
Media & Marketing Executive
US: +1 844 364 1100
UK: +44 203 893 3200
Email: media@technavio.com
Website: www.technavio.com/

View original content to download multimedia:https://www.prnewswire.com/news-releases/fleet-management-market-to-grow-by-usd-52-23-billion-by-2029–driven-by-e-commerce-and-last-mile-delivery-report-on-ai-powered-market-evolution—technavio-302368475.html

SOURCE Technavio

Continue Reading

Technology

Electronic System Design Industry Posts $5.7 Billion in Revenue in Q2 2026, ESD Alliance Reports

Published

on

By

IC Physical Design & Verification, Semiconductor IP, and Services Reported Double-Digit Year-over-Year Revenue Increase

MILPITAS, Calif., Oct. 19, 2026 /PRNewswire/ — Electronic System Design (ESD) industry revenue increased 12.2% to $5,710.8 million in the second quarter of 2026 from the $5,089.4 million registered in the second quarter of 2025, the ESD Alliance, a SEMI Technology Coalition, announced today in its latest Electronic Design Market Data (EDMD) report. The four-quarter moving average rose 11.2%, based on a comparison of the most recent four quarters to the prior four.

“The electronic design automation industry once again reported strong year-over-year revenue growth in Q2 2026,” said Walden C. Rhines, Executive Sponsor of the SEMI Electronic Design Market Data report and Chief Executive Officer of Silvaco Group, Inc. “All product categories except Printed Circuit Board and Multi-Chip Module reported gains, with IC Physical Design and Verification, Semiconductor IP, and Services showing double digit growth. All geographic regions reported growth in Q2, with double digit increases in the APAC region.“

The companies tracked in the EDMD report employed 71,396 people globally in Q2 2026, a 1.6% decrease from the Q2 2025 headcount of 72,529 and down 1.6% compared to Q1 2025.

The quarterly EDMD report contains detailed revenue information within the following category and geographic breakdowns.

Second Quarter Revenue by Segment and Geographic Region ($Millions)

Americas

EMEA*

Japan

APAC*

Q2′ 26 Total

Q2′ 25 Total

% Growth

Total EDA Revenue

1400.3

451.9

266.7

1141.2

3260.0

3061.4

6.5 %

CAE

921.5

286.5

100.0

769.5

2077.6

1929.0

7.7 %

PCB & MCM

139.6

79.2

39.7

105.8

364.2

430.5

-15.4 %

IC Physical Design & Verification

339.1

86.2

127.0

266.0

818.3

701.9

16.6 %

Total SIP Revenue

881.7

183.0

21.9

1112.5

2199.0

1826.7

20.4 %

Reporting SIP Companies

289.2

70.5

21.9

343.6

725.2

618.9

17.2 %

Non-reporting SIP Companies**

592.4

112.5

0.0

768.9

1473.9

1207.8

22.0 %

Total Services Revenue

161.5

30.7

14.5

45.0

251.7

201.2

25.1 %

Total EDA, SIP & Services Revenue

2443.5

665.6

303.1

2298.7

5710.8

5089.4

12.2 %

* EMEA = Europe, Middle East, and Africa. APAC = Asia Pacific

** Non-reporting SIP companies include ARM Holdings PLC (excl. ARM PIPD), CEVA Inc., and
Rambus Inc. Beginning with Q4 2016, ARM PIPD exclusion is estimated.

Revenue by Product and Application Category – Year-Over-Year Change

Computer-Aided Engineering (CAE) revenue increased 7.7% to $2,077.6 million. The four-quarter CAE moving average increased 10.7%.

IC Physical Design and Verification revenue increased 16.6% to $818.3 million. The four-quarter moving average for the category increased 5.4%.

Printed Circuit Board and Multi-Chip Module (PCB and MCM) revenue dropped 15.4% to $364.2 million. The four-quarter moving average for PCB and MCM decreased 1.3%.

Semiconductor Intellectual Property (SIP) revenue increased 20.4% to $2,199.0 million. The four-quarter SIP moving average rose 16.6%.

Services revenue increased 25.1% to $251.7 million. The four-quarter Services moving average rose 15.2%.

Revenue by Region – Year-Over-Year Change

The Americas, the largest reporting region by revenue, procured $2,443.5 million of electronic system design products and services in Q2 2026, a 7.1% increase. The four-quarter moving average for the Americas rose 8.6%.

Europe, Middle East, and Africa (EMEA) procured $665.6 million of electronic system design products and services in Q2 2026, a 2.3% increase. The four-quarter moving average for EMEA grew 8.6%.

Japan’s procurement of electronic system design products and services increased 9.3% to $303.1 million in Q2 2026. The four-quarter moving average for Japan decreased 8.2%.

Asia Pacific (APAC) procured $2,298.7 million of electronic system design products and services in Q2 2026, a 22.4% increase. The four-quarter moving average for APAC grew 18.3%.

About the EDMD Report
The ESD Alliance Electronic Design Market Data (formerly the Market Statistics Service) report presents Electronic Design Automation (EDA), SIP and Services industry revenue data quarterly. Both public and private companies contribute data to the report available from SEMI. Each quarterly report is published approximately three months after quarter close. EDMD report data is segmented as follows:

Revenue by product category (CAE, IC Physical Design and Verification, SIP, PCB and MCM Layout, and Services) including numerous detailed sub-categoriesRevenue by geographic region (Americas, EMEA, Japan and APAC)Total employment at participating companies

For information about SEMI market research reports, visit the SEMI Market Research Reports and Databases Catalog.

About the Electronic System Design Alliance
The Electronic System Design (ESD) Alliance, a SEMI Technology Coalition, is the central voice to communicate and promote the value of the semiconductor design ecosystem as a vital component of the global electronics industry. As an international association of companies providing goods and services throughout the semiconductor design ecosystem, it is a forum to address technical, marketing, economic and legislative issues affecting the entire industry. For more information about the ESD Alliance, visit http://esd-alliance.org.

Follow the ESD Alliance

X: @ESDAllianceLinkedIn Facebook 

About SEMI
SEMI® is the global industry association connecting over 4,000 companies and 1.5 million professionals worldwide across the semiconductor and electronics design and manufacturing supply chain. We accelerate member collaboration on solutions to top industry challenges through Advocacy, Workforce Development, Sustainability, Supply Chain Management and other programs. Our SEMICON® expositions and events, technology communities, standards and market intelligence help advance our members’ business growth and innovations in design, devices, equipment, materials, services and software, enabling smarter, faster, more secure electronics. Visit www.semi.org, contact a regional office, and connect with SEMI on LinkedIn and X to learn more.

The information supplied by the ESD Alliance is believed to be accurate and reliable, but the ESD Alliance assumes no responsibility for any errors that may appear in this document. All trademarks and registered trademarks are the property of their respective owners.

Association Contacts

Paul Cohen
Phone: 508-769-2106
Email: pcohen@semi.org

Lisa Gillette-Martin/Bodewell Group (Media Inquiries)
Phone: 1-408-205-4732
Email: lgmartin@bodewellgroup.com 

View original content to download multimedia:https://www.prnewswire.co.uk/news-releases/electronic-system-design-industry-posts-5-7-billion-in-revenue-in-q2-2026–esd-alliance-reports-302912160.html

Continue Reading

Technology

Scorpion deepens its investment in pest control and lawn care, acquires Coalmarch Marketing

Published

on

By

Coalmarch’s team, client relationships, and pest and lawn care expertise join Scorpion, gaining more technology, data, and resources for Coalmarch clients

SALT LAKE CITY, Oct. 19, 2026 /PRNewswire/ — Scorpion, the leading provider of digital marketing and technology solutions for local businesses, today announced it has acquired Coalmarch Marketing, a Raleigh, North Carolina-based digital marketing agency dedicated to the pest control and lawn care industries since 2004. The move deepens Scorpion’s investment in pest control, lawn care, and landscape marketing, bringing Coalmarch’s team, its client relationships, and more than two decades of experience to Scorpion.

“This is really about two great teams coming together,” said Trey Pelz, Scorpion’s General Manager of Pest. “Coalmarch has built something special: great people, strong relationships, and a team that truly understands this industry. We don’t want to change what’s already working. We want to build on it and put more behind it. There’s no technology that can replace a great relationship, but we can give it more tools, better data, and more resources to help these businesses grow. That’s really what this is about: keeping what works, and giving it more.”

“We’re entering one of the most interesting periods marketing has ever seen, and we’re investing heavily in the technology and data behind it,” Pelz said. “Coalmarch’s clients keep the high-touch, industry-specific experience they already know, now with even more behind it.”

Jeff Davis, CEO of Coalmarch, shares that view. “I’ve gotten to know Trey and the Scorpion team well, and I’ve seen firsthand how they operate,” said Davis. “They share the same commitment to client growth that we’ve built Coalmarch on, now backed by a level of technology and investment that makes what we’ve built even stronger.”

Coalmarch clients now gain access to RevenueMAX, Scorpion’s AI-powered solution built to turn marketing into measurable revenue, not just leads.

“Welcoming Coalmarch to Scorpion is another intentional step in our M&A strategy,” said Kirby Oscar, SVP of Corporate Development at Scorpion. “This investment deepens our vertical commitment and supports a key pillar in our long-term growth plans. Coalmarch’s team has built an impressive business that has helped the pest, lawn, and landscaping industries grow, and we’re looking forward to accelerating that growth.”

Respectively, Scorpion and Coalmarch bring more than two decades of pest and lawn-specific marketing experience under one team.

About Scorpion
Scorpion is the leader in helping local businesses find their most valuable clients through digital marketing solutions. With technology focused on driving revenue at every step of the client journey, Scorpion is pushing the industry forward past a focus on leads, and toward a focus on what truly matters, revenue growth. Backed by award-winning AI, unmatched data, and more than 25 years of marketing expertise, Scorpion wins local businesses more customers, more revenue, and most importantly, better ROI. With Scorpion, there’s no guesswork, only growth. To learn more, visit Scorpion.co.

About Coalmarch
Coalmarch is a digital marketing agency dedicated exclusively to the pest control and lawn care industries. Founded in 2004 and based in Raleigh, North Carolina, Coalmarch has spent more than 20 years helping pest and lawn care businesses grow through SEO, paid search, website development, and marketing built specifically for how these companies operate in the field. Coalmarch is now part of Scorpion. Learn more at Coalmarch.com.

Media Contact
Scorpion Public Relations
ScorpionPR@Scorpion.co

View original content to download multimedia:https://www.prnewswire.com/news-releases/scorpion-deepens-its-investment-in-pest-control-and-lawn-care-acquires-coalmarch-marketing-302912687.html

SOURCE Scorpion

Continue Reading

Technology

Environment, Health, and Safety Market worth $13.97 Billion by 2032 – Report by MarketsandMarkets™

Published

on

By

DELRAY BEACH, Fla., Oct. 19, 2026 /PRNewswire/ — According to MarketsandMarkets™, the Environment, Health, and Safety Market is projected to grow from USD 9.28 billion in 2026 and to reach USD 13.97 billion by 2032, at a Compound Annual Growth Rate (CAGR) of 7.0% during the forecast period. 

Browse 300 market data Tables and 55 Figures spread through 350 Pages and in-depth TOC on “Environment, Health, and Safety Market – Global Forecast to 2032”

Environment, Health, and Safety Market Size & Forecast:

Market Size Available for Years: 2020–20322025 Market Size: USD 8.62 billion2026 Market Size: USD 9.28 billion2032 Projected Market Size: USD 13.97 billionCAGR (2026–2032): 7.0%

Environment, Health, and Safety Market Trends & Insights:

The global EHS market is witnessing strong growth, driven by increasing regulatory requirements, growing focus on workplace safety, and the need for organizations to manage environmental and occupational risks more effectively.By offering, the services segment is expected to register the highest CAGR of 9.8%.By vertical, the energy & utilities segment is projected to grow at the fastest rate from 2026 to 2032.Asia Pacific is projected to be the fastest-growing region in the global Environment, Health, and Safety Market.

Download PDF Brochure: https://www.marketsandmarkets.com/pdfdownloadNew.asp?id=59608773

The Environment, Health, and Safety Market is expected to reach USD 13.97 billion by 2032 from USD 9.28 billion in 2026, at a compound annual growth rate (CAGR) of 7.0% during 2026–2032. The market is witnessing strong growth as organizations increasingly focus on workplace safety, environmental compliance, risk management, and operational efficiency. Stricter regulations, rising awareness of employee health and safety, and the need to reduce workplace incidents are accelerating EHS adoption. Enterprises are increasingly investing in digital EHS software and services to streamline compliance management, incident reporting, risk assessment, audits, inspections, and environmental monitoring. The growing adoption of cloud-based platforms, analytics, automation, and connected technologies further supports more integrated, data-driven EHS management.

The growing deployment of EHS technologies enables organizations to continuously monitor workplace risks, environmental performance, safety incidents, and compliance requirements. These solutions support incident management, corrective actions, risk assessment, safety inspections, environmental reporting, and regulatory compliance. EHS software centralizes data, automates workflows, improves visibility, and enables faster decision-making, while services support implementation, consulting, training, and ongoing system management. As organizations prioritize safer workplaces, regulatory compliance, and sustainable operations, EHS market adoption is expected to expand across developed and emerging economies.

Request for Proposal: https://www.marketsandmarkets.com/requestsampleNew.asp?id=59608773

By offering, the software segment is expected to hold the largest market share.

The software segment is expected to hold the largest share of the global Environment, Health, and Safety (EHS) market, driven by the growing need for centralized, automated, data-driven management of workplace safety, environmental compliance, and operational risks. Organizations are increasingly adopting EHS software to manage incident reporting, risk assessments, audits, inspections, compliance requirements, environmental monitoring, and employee health and safety programs. The growing focus on regulatory compliance, sustainability, workplace safety, and ESG initiatives is further increasing demand for integrated EHS platforms.

These solutions leverage cloud computing, artificial intelligence (AI), analytics, mobile technologies, and automation to improve real-time visibility into EHS performance, identify potential risks, streamline reporting, and support faster corrective actions. Integration with enterprise systems, IoT devices, connected equipment, and environmental monitoring technologies is further enhancing EHS software capabilities. As organizations prioritize proactive risk management, regulatory compliance, and sustainability, EHS software is becoming critical to improving operational efficiency, reducing incidents, and enabling scalable, data-driven EHS management.

By service, the analytics services segment is expected to witness the highest growth rate during the forecast period.

The analytics services segment is expected to grow rapidly as organizations increasingly use EHS data analytics to identify risks, monitor compliance, and improve workplace safety. The growing volume of environmental, health, and safety data is driving demand for real-time dashboards, predictive analytics, incident trend analysis, and performance monitoring.

Analytics services also support EHS decision-making by converting complex operational data into actionable insights without requiring significant in-house analytical capabilities. The increasing adoption of cloud-based EHS platforms, IoT-enabled monitoring, and AI-driven analytics is enabling proactive risk identification, improved regulatory compliance, and stronger safety performance, further driving segment growth.

Request Pricing: https://www.marketsandmarkets.com/Enquiry_Before_BuyingNew.asp?id=59608773

Asia Pacific is expected to register the highest growth rate during the forecast period.

Asia Pacific is projected to register the highest CAGR in the Environment, Health, and Safety (EHS) market during the forecast period, driven by rapid industrialization, expanding manufacturing and infrastructure activities, stricter workplace safety regulations, and increasing adoption of cloud-based EHS software across countries such as China, Japan, India, South Korea, and Australia. Organizations are increasingly deploying digital EHS platforms for incident management, risk assessment, compliance management, environmental monitoring, workforce health, and safety analytics to improve operational visibility and reduce workplace risks. The region’s growing focus on sustainability, ESG reporting, worker protection, and regulatory compliance is further accelerating demand for integrated EHS solutions and services. AI, real-time analytics, mobile applications, and automated reporting are also enabling organizations to shift from reactive compliance to proactive risk prevention. A notable recent development is Cority’s 2026 expansion of AI-driven EHS capabilities, with more than 30 AI workflows demonstrated across safety, health, environmental, and operational risk management, highlighting the broader shift toward intelligent and integrated EHS platforms.

Top Companies in Environment, Health, and Safety Market:

The Top Companies in Environment, Health, and Safety Market are Wolters Kluwer (Netherlands), VelocityEHS (US), Intelex (Canada), Benchmark ESG (US), Cority (Canada), Intertek (UK), Sphera (US), Quentic (Germany), PureEHS (US), Ideagen (UK), SAP (Germany), IBM (US), Evotix (UK), EcoOnline (UK), Diligent Corporation (US), Octave Reliance (US), 3E (US), Dakota Software (US), IsoMetrix (South Africa), Enhesa (Belgium), VisiumKMS (US), SafetyCulture (Australia), TrueContext (Canada), ComplianceQuest (US), Pro-Sapien (UK), XGRC Software (South Africa), Mitratech (US), Indus Environmental Services (India), Inicia (Japan), Core-EHS (India), and EHS Brasil (Brazil).

Environment, Health, and Safety Market – Investment & funding +Merger & Acquisition

Investment and Funding Context

The Environment, Health, and Safety Market is attracting increasing investment as organizations prioritize cloud-based EHS platforms, AI-enabled risk management, sustainability integration, and digital compliance. Investment is increasingly directed toward AI, analytics, mobile EHS workflows, and integrated EHS and sustainability platforms. For instance, Sphera received a significant growth investment from Neuberger Berman in 2025, with Blackstone retaining a majority stake, supporting further expansion of its operational risk management software and data portfolio. Similarly, Medgate received a strategic investment led by Norwest Venture Partners in 2026 to accelerate product expansion, analytics innovation, and acquisitions in enterprise EHS software. These developments indicate growing private investment toward scalable, AI-enabled, and integrated EHS technology.

Revenue Shift Context

The Environment, Health, and Safety Market is shifting from traditional compliance-focused tools toward integrated, AI-enabled platforms that help organizations continuously identify risks, automate workflows, improve workforce safety, and connect EHS with sustainability and operational performance. Wolters Kluwer reported that 49% of EHS functions planned to invest in AI within 12 months, highlighting rising demand for AI-driven EHS capabilities. Cority is also expanding its CorityOne platform with AI, mobile capabilities, and integrated sustainability management, while its Cortex AI suite enables intelligent agents across EHS and sustainability workflows. This shift moves EHS from a compliance cost center to a data-driven performance and risk-prevention function, creating new revenue opportunities in AI, analytics, automation, connected worker solutions, and subscription-based platforms.

Mergers and Acquisitions

M&A activity in the Environment, Health, and Safety Market is increasingly focused on consolidating EHS software, occupational health, crisis management, sustainability, and AI-driven risk capabilities. Recent transactions demonstrate a shift toward integrated platforms that connect safety, environmental compliance, workforce health, emergency response, and sustainability management.

Environment, Health, and Safety Market: MERGERS AND ACQUISITIONS, JANUARY 2025–JUNE 2026

Month & Year

Deal Type

Company 1

Company 2

Description

February 2026

Acquisition

Peak Rock Capital (US)

UL Solutions EHS Software (US)

Peak Rock Capital agreed to acquire UL
Solutions’ EHS software business, which was
subsequently rebranded as PureEHS,
covering employee health, occupational
health, safety, and training.

December 2025

Acquisition

EcoOnline (UK)

Alcumus EHS Software (UK)

EcoOnline acquired Alcumus’ EHS software
business, expanding its global EHSQ
portfolio and customer reach across
multiple industries.

Company Revenue Share Details

The Environment, Health, and Safety Market remains highly competitive and fragmented, with no single vendor controlling the overall market because it covers environmental management, occupational health and safety, risk management, compliance, sustainability, and operational risk. Wolters Kluwer has strengthened its position with the Enablon platform, which combines EHS, operational risk, process safety, ESG, and AI-powered capabilities. Cority maintains a strong position through its integrated CorityOne platform, supported by EHS, sustainability, and ESG capabilities and acquisitions such as Greenstone. EcoOnline has expanded its global EHSQ footprint through acquisitions, including Alcumus’ EHS software business, adding complementary risk, compliance, and sustainability capabilities. Other major participants, including VelocityEHS, Intelex, Sphera, Benchmark ESG, Ideagen, SAP, IBM, and Evotix, contribute through EHS management, environmental compliance, operational risk, sustainability, and workplace safety solutions. Overall, demand for integrated cloud platforms, AI-enabled risk management, mobile workforce solutions, sustainability reporting, and connected EHS data is increasingly shaping competition, while the lack of standardized standalone EHS revenue reporting makes precise company revenue-share comparisons difficult.

Browse Adjacent Markets: Software and Services Market Research Reports & Consulting

Related Market Reports:

Workplace Safety Market by Hardware (Safety Sensors, RFID Tags & Readers, Wearables, Software), by System(Real-time Location Monitoring, EHS, Access Control & Surveillance), by Application(Incident & Emergency, PPE Detection, Asset & Staff Tracking) – Global Forecast to 2030

Risk Analytics Market by Offering (AI-Enabled & Predictive Risk Analytics Software, GRC & ERM Software, Third-party Risk Management Tools, Risk Assessment & Advisory Services, Cyber & IT Risk Management Services, Compliance & Regulatory Management Services), and Risk Type – Global Forecast to 2030

About MarketsandMarkets™  

MarketsandMarkets™ has been recognized as one of America’s Best Management Consulting Firms by Forbes, as per their recent report.

MarketsandMarkets™ is a blue ocean alternative in growth consulting and program management, leveraging a man-machine offering to drive supernormal growth for progressive organizations in the B2B space. With the widest lens on emerging technologies, we are proficient in co-creating supernormal growth for clients across the globe.

Today, 80% of Fortune 2000 companies rely on MarketsandMarkets, and 90 of the top 100 companies in each sector trust us to accelerate their revenue growth. With a global clientele of over 13,000 organizations, we help businesses thrive in a disruptive ecosystem.

The B2B economy is witnessing the emergence of $25 trillion in new revenue streams that are replacing existing ones within this decade. We work with clients on growth programs, helping them monetize this $25 trillion opportunity through our service lines – TAM Expansion, Go-to-Market (GTM) Strategy to Execution, Market Share Gain, Account Enablement, and Thought Leadership Marketing.

Built on the ‘GIVE Growth’ principle, we collaborate with several Forbes Global 2000 B2B companies to keep them future-ready. Our insights and strategies are powered by industry experts, cutting-edge AI, and our Market Intelligence Cloud, KnowledgeStore™, which integrates research and provides ecosystem-wide visibility into revenue shifts.

MarketsandMarkets™ SalesPlay is an AI-driven Revenue Intelligence Co-Pilot designed to help revenue teams prioritize the right accounts, identify critical changes early, and surface opportunities ahead of demand, so pipeline builds naturally and deals close with greater consistency.

To find out more, visit www.MarketsandMarkets™.com or follow us on Twitter, LinkedIn and Facebook.

Contact:
Mr. Rohan Salgarkar
MarketsandMarkets™ INC.
1615 South Congress Ave.
Suite 103, Delray Beach, FL 33445
USA: +1-888-600-6441
Email: sales@marketsandmarkets.com
Visit Our Website: https://www.marketsandmarkets.com/
Content Source: https://www.marketsandmarkets.com/PressReleases/environment-health-safety-ehs.asp

View original content to download multimedia:https://www.prnewswire.co.uk/news-releases/environment-health-and-safety-market-worth-13-97-billion-by-2032–report-by-marketsandmarkets-302912469.html

Continue Reading

Trending