
Technology
RICHMOND MUTUAL BANCORPORATION, INC. ANNOUNCES 2026 SECOND QUARTER FINANCIAL RESULTS

Published
3 months agoon
By

RICHMOND, Ind., July 27, 2026 /PRNewswire/ — Richmond Mutual Bancorporation, Inc., a Maryland corporation (the “Company”) (NASDAQ: RMBI), parent company of First Bank Richmond, today reported net income of $2.2 million, or diluted earnings per share of $0.22, for the second quarter of 2026. This compares to net income of $2.8 million, or $0.28 diluted earnings per share, for the first quarter of 2026, and net income of $2.6 million, or diluted earnings per share of $0.26, for the second quarter of 2025.
The decrease in net income and diluted earnings per share from the first quarter of 2026 was primarily due to higher noninterest expense, reflecting $1.9 million of non-recurring merger-related expenses associated with the Company’s acquisition of The Farmers Bancorp, Frankfort, Indiana (“Farmers Bancorp”), as well as a higher provision for credit losses. These items were partially offset by higher net interest income resulting from an expanded net interest margin and increased average loan balances, as well as higher noninterest income. Compared to the second quarter of 2025, net income decreased primarily as a result of merger-related expenses and a higher provision for credit losses, partially offset by higher net interest income driven by an expanded net interest margin and increased average interest-earning assets, together with higher noninterest income.
On July 1, 2026, the Company completed its previously announced merger with Farmers Bancorp pursuant to the Agreement and Plan of Merger dated November 11, 2025. Immediately thereafter, The Farmers Bank merged with and into First Bank Richmond. The combined company continues to operate as Richmond Mutual Bancorporation, Inc., while the combined bank is operating under the name First Bank Midwest. The combined company continues to trade on the Nasdaq Capital Market under the ticker symbol “RMBI.” The administrative headquarters of the holding company remains in Richmond, Indiana, while the combined bank is headquartered in Frankfort, Indiana.
The financial results presented in this earnings release reflect the Company’s operations through June 30, 2026, immediately prior to the completion of the merger. Accordingly, the operating results of Farmers Bancorp will first be included in the Company’s financial results for the quarter ending September 30, 2026.
CEO’s and President’s Message
Garry Kleer, Chairman and Chief Executive Officer, commented, “Our second quarter results reflected continued improvement in our core operating performance, highlighted by growth in net interest income and expansion of our net interest margin compared to both the prior quarter and the second quarter of last year. Loan growth remained solid, funding costs continued to improve, and our capital position remained strong. While earnings were impacted by a higher provision for credit losses and merger-related expenses during the quarter, we believe the Company entered this next phase from a position of financial strength.
“The successful completion of our merger with Farmers Bancorp marks an important milestone in our Company’s history. The combination creates a stronger community banking franchise with greater scale, an expanded market presence and enhanced opportunities to serve our customers and communities. I am pleased to welcome Christopher Cook as our President, along with our new colleagues from Farmers Bancorp, and I look forward to working together as we integrate our organizations and execute on the strategic opportunities this combination creates,” concluded Kleer.
Christopher Cook, President stated, “I am honored to join Richmond Mutual at such an exciting time. Our immediate priority is a successful integration that is seamless for our customers, employees and communities, while positioning the combined organization to realize the long-term benefits of this merger. I look forward to working alongside Garry and our entire team as we build on the strong foundation established by both organizations.”
Second Quarter Performance Highlights:
Net interest income increased by $628,000, or 5.5%, to $12.1 million for the three months ended June 30, 2026, from to $11.4 million for the quarter ended March 31, 2026. Net interest income increased by $1.3 million, or 12.2%, from $10.8 million for the comparable quarter in 2025.Annualized net interest margin was 3.22% for the current quarter, compared to 3.10% in the prior quarter and 2.93% for the comparable quarter in 2025.A provision for credit losses of $823,000 was recorded for the quarter ended June 30, 2026, compared to $693,000 and $745,000 for the quarters ended March 31, 2026 and June 30, 2025, respectively.Noninterest income increased $282,000, or 21.7%, to $1.6 million for the three months ended June 30, 2026, compared to $1.3 million for the quarter ended March 31, 2026, and increased $500,000, or 46.3%, from $1.1 million for the comparable quarter in 2025.Noninterest expense increased $1.5 million, or 16.8%, to $10.2 million for the three months ended June 30, 2026, compared to $8.7 million for the quarter ended March 31, 2026, and increased $2.1 million, or 25.4%, from $8.1 million for the comparable quarter in 2025. The increase in noninterest expense was primarily attributable to $1.9 million of nonrecurring merger-related expenses recorded during the second quarter of 2026, consisting primarily of professional fees and other transaction-related costs.Assets totaled $1.6 billion at June 30, 2026, compared to $1.5 billion at March 31, 2026 and December 31, 2025.Loans and leases, net of allowance for credit losses, totaled $1.2 billion at June 30, 2026, March 31, 2026, and December 31, 2025.Nonperforming loans and leases totaled $21.8 million, or 1.78% of total loans and leases, at June 30, 2026, compared to $17.6 million, or 1.48%, at March 31, 2026, and $17.4 million, or 1.46%, at December 31, 2025.The allowance for credit losses totaled $17.0 million, or 1.39% of total loans and leases outstanding, at June 30, 2026, compared to $16.7 million, or 1.41%, at March 31, 2026, and $16.5 million, or 1.38%, at December 31, 2025.Deposits totaled $1.1 billion at June 30, 2026, March 31, 2026, and December 31, 2025. At June 30, 2026, noninterest-bearing deposits totaled $100.1 million, or 8.7% of total deposits, compared to $99.4 million, or 9.0%, at March 31, 2026, and $100.1 million, or 9.0%, at December 31, 2025.Stockholders’ equity totaled $148.3 million at June 30, 2026, compared to $144.9 million at March 31, 2026, and $145.8 million at December 31, 2025. The Company’s equity to assets ratio was 9.55% at June 30, 2026.Book value per share and tangible book value per share were each $14.11 at June 30, 2026, compared to $13.80 at March 31, 2026 and $13.88 per share at December 31, 2025.The Bank’s Tier 1 capital to total assets was 10.90% at June 30, 2026, well in excess of regulatory requirements, reflecting the Company’s strong capital position.
Income Statement Summary
Net interest income before the provision for credit losses increased $628,000, or 5.5%, to $12.1 million in the second quarter of 2026, compared to $11.4 million in the first quarter of 2026, and increased $1.3 million, or 12.2%, from $10.8 million in the second quarter of 2025. The increase from the first quarter of 2026 was due to an increase in the average interest rate spread of 13 basis points, partially offset by a $3.0 million decrease in average net earning assets. Compared to the second quarter of 2025, the increase in net interest income was due to a 32 basis point increase in the average interest rate spread and a $9.4 million increase in average net earning assets.
Interest income increased $736,000, or 3.5%, to $21.9 million during the quarter ended June 30, 2026, compared to $21.2 million during the quarter ended March 31, 2026, and increased $552,000, or 2.6%, compared to $21.3 million during the quarter ended June 30, 2025, primarily due to higher interest income on loans and leases resulting from loan growth and higher yields.
Interest income on loans and leases increased $679,000, or 3.6%, to $19.8 million for the quarter ended June 30, 2026, compared to $19.1 million in the first quarter of 2026, due to a nine basis point increase in the average yield earned on loans and leases to 6.55%, and a $24.7 million increase in the average balance of loans and leases. Compared to the second quarter of 2025, interest income on loans and leases increased $607,000, or 3.2%, due to a $29.8 million increase in the average balance of loans and leases and a four basis point increase in the average yield earned, reflecting new loans originated at higher rates and variable-rate loans repricing.
Interest income on investment securities, excluding FHLB stock, decreased $2,000, or 0.1%, to $1.6 million during the quarter ended June 30, 2026, compared to the quarter ended March 31, 2026, and decreased $31,000, or 1.9%, from the comparable quarter in 2025. The decrease compared to the first quarter of 2026 was due to a $6.1 million decrease in the average balance of investment securities, partially offset by a six basis point increase in the average yield earned. The decrease compared to the second quarter of 2025 was primarily due to a $1.1 million decrease in the average balance of investment securities, and a four basis point decrease in the average yield earned on investment securities. Dividends on FHLB stock increased $10,000, or 3.4%, to $301,000 during the quarter ended June 30, 2026 compared to the quarter ended March 31, 2026, due to a 29 basis point increase in the average yield on FHLB stock, and decreased $8,000, or 2.6%, compared to the quarter ended June 30, 2025, due to a 23 basis point decrease in the average yield on FHLB stock.
Interest income on cash and cash equivalents increased $50,000, or 28.1%, to $228,000 during the quarter ended June 30, 2026, compared to the quarter ended March 31, 2026, and decreased $15,000, or 6.2%, compared to the quarter ended June 30, 2025. The increase from the first quarter of 2026 was primarily due to a $4.4 million increase in the average balance of cash and cash equivalents and a 20 basis point increase in the average yield. Compared to the second quarter of 2025, the decrease in interest income was due to a 40 basis point decrease in the average yield, partially offset by a $1.1 million increase in the average balance of cash and cash equivalents.
Interest expense increased $109,000, or 1.1%, to $9.8 million for the quarter ended June 30, 2026, compared to the quarter ended March 31, 2026, and decreased $762,000, or 7.2%, compared to the quarter ended June 30, 2025.
Interest expense on deposits decreased $85,000, or 1.2%, to $7.2 million for the quarter ended June 30, 2026, compared to the previous quarter and decreased $599,000, or 7.7%, from the comparable quarter in 2025. The decrease from the previous quarter was primarily due to a seven basis point decrease in the average rate paid on interest-bearing deposits. The decrease from the comparable quarter in 2025 was due to a 32 basis point decrease in the average rate paid on interest-bearing deposits, partially offset by a $28.8 million increase in the average balance of interest-bearing deposits. The average rate paid on interest-bearing deposits was 2.82%, 2.89%, and 3.14% for the quarters ended June 30, 2026, March 31, 2026, and June 30, 2025, respectively.
Interest expense on FHLB borrowings increased $194,000, or 8.0%, to $2.6 million for the second quarter of 2026 compared to the previous quarter, and decreased $163,000, or 5.9%, from the comparable quarter in 2025. The increase from the previous quarter was primarily due to an 11 basis point increase in the average rate paid on FHLB borrowings and a $12.5 million increase in the average balance. The decrease from the comparable quarter in 2025 was primarily due to an $8.5 million decrease in the average balance and a 12 basis point decrease in the average rate paid on FHLB borrowings. The average balance of FHLB borrowings totaled $253.6 million during the quarter ended June 30, 2026, compared to $241.1 million and $262.1 million for the quarters ended March 31, 2026, and June 30, 2025, respectively. The average rate paid on FHLB borrowings was 4.12% for the quarter ended June 30, 2026, compared to 4.01% for the quarter ended March 31, 2026, and 4.24% for the second quarter of 2025.
Annualized net interest margin was 3.22% for the second quarter of 2026, compared to 3.10% for the first quarter of 2026 and 2.93% for the second quarter of 2025. The increase in net interest margin from the first quarter of 2026 primarily reflected a higher average balance of interest-earning assets, continued improvement in funding costs, and a favorable change in the interest rate spread. The improvement compared to the second quarter of 2025 was driven by a higher average yield on loans and leases, and lower funding costs. The Federal Open Market Committee maintained the target federal funds rate range at 3.50% to 3.75% through the second quarter of 2026 following rate reductions implemented in late 2025.
A provision for credit losses of $823,000 was recorded in the second quarter of 2026, compared to $693,000 in the first quarter of 2026 and $745,000 in the second quarter of 2025. Net charge-offs for the second quarter of 2026 were $557,000, compared to $347,000 in the first quarter of 2026 and $626,000 in the second quarter of 2025.
Noninterest income increased $282,000, or 21.8%, to $1.6 million for the quarter ended June 30, 2026, compared to the quarter ended March 31, 2026, and increased $500,000, or 46.3%, from the comparable quarter in 2025. The increase from the first quarter of 2026 primarily resulted from an increase in other income, primarily due to increased wealth management income. Compared to the second quarter of 2025, the increase in noninterest income primarily resulted from net losses on sales of securities totaling $157,000 in the second quarter of 2025, while no securities were sold during the second quarter of 2026, and other income. Other income increased $243,000, or 62.0%, to $635,000 for the three months ended June 30, 2026, compared to the first quarter of 2026, and increased $281,000, or 79.5%, compared to the same period in 2025 as a result of increased estate fees included in wealth management income.
Total noninterest expense increased $1.5 million, or 16.8%, to $10.2 million for the three months ended June 30, 2026, compared to the first quarter of 2026, and increased $2.1 million, or 25.4%, compared to the same period in 2025. The increase in both comparisons was primarily attributable to $1.9 million of nonrecurring merger-related expenses recorded in the current quarter, consisting primarily of professional fees and other transaction-related costs. Salaries and employee benefits increased $163,000, or 3.6%, to $4.7 million for the quarter ended June 30, 2026, compared to the first quarter of 2026, and decreased $41,000, or 0.9%, compared to the quarter ended June 30, 2025, reflecting normal annual salary and benefit increases. Data processing fees decreased $91,000, or 7.6%, to $1.1 million for the quarter ended June 30, 2026, compared to the prior quarter, and increased $175,000, or 18.9%, compared to the same quarter of 2025, primarily due to new product implementations.
Income tax expense decreased $126,000 during the three months ended June 30, 2026, compared to the quarter ended March 31, 2026, and increased $54,000 compared to the quarter ended June 30, 2025. The effective tax rate for the second quarter of 2026 was 16.4%, compared to 16.8% in the first quarter of 2026 and 12.8% in the second quarter a year ago.
Balance Sheet Summary
Total assets increased $26.2 million, or 1.7%, to $1.6 billion at June 30, 2026, as compared to December 31, 2025. The increase was primarily the result of a $31.0 million, or 2.6%, increase in loans and leases, net of allowance for credit losses to $1.2 billion, partially offset by a $7.0 million, or 2.8%, decrease in investment securities to $247.6 million.
Investment securities decreased $7.0 million, or 2.8%, to $247.6 million at June 30, 2026, compared to $254.7 million at December 31, 2025. The decrease was primarily due to $7.4 million in maturities and principal repayments, partially offset by $955,000 in purchases of investment securities. The proceeds from maturities and principal repayments were redeployed to support loan growth. While these portfolio shifts contributed to a decline in average balances and interest income from investment securities, they supported overall growth in net interest income and an improved net interest margin for the quarter.
The increase in loans and leases was attributable to increases in commercial mortgage loans, commercial and industrial loans, construction and development loans, and home equity lines of credit of $4.8 million, $15.6 million, $14.5 million, and $2.3 million, respectively. These increases were partially offset by a $1.1 million decrease in multi-family loans, a $1.0 million decrease in residential mortgage loans, a $1.3 million decrease in consumer loans, and a $2.2 million decrease in direct financing leases.
Nonperforming loans and leases, consisting of nonaccrual loans and leases and accruing loans and leases 90 days or more past due, totaled $21.8 million, or 1.78% of total loans and leases, at June 30, 2026, compared to $17.4 million, or 1.46%, at December 31, 2025. Nonaccrual loans and leases increased $6.9 million, or 52.2%, to $20.0 million at June 30, 2026, from $13.2 million at December 31, 2025, primarily due to a multi-family loan of $2.4 million, which was past due 90 days or more at December 31, 2025, and a multi-family loan of $3.5 million, which was current but placed on nonaccrual status as of June 30, 2026 due to a troubled loan modification.
The allowance for credit losses on loans and leases increased $508,000, or 3.1%, to $17.0 million, or 1.39% of total loans and leases, at June 30, 2026, from $16.5 million, or 1.38% of total loans and leases, at December 31, 2025. The allowance for credit losses provided coverage of 77.9% of nonperforming loans and leases at June 30, 2026, compared to 94.6% at December 31, 2025, primarily due to the increase in nonperforming loans during the period. Net charge-offs during the first half of 2026 were $904,000, or an annualized 0.18% of average loans and leases, compared to $1.0 million during the comparable period of 2025, as realized credit losses remained low.
Management regularly evaluates credit exposure across its loan portfolio and within its geographic markets. As of June 30, 2026, the Company’s credit risk assessment incorporated ongoing economic conditions, including inflationary pressures, capital market volatility, and geopolitical risks. Management continues to conduct portfolio stress testing and monitor credit metrics and believes the allowance for credit losses is appropriate based on the current composition of the loan and lease portfolio, the level of individually evaluated reserves, and the continued low level of net charge-offs.
Total deposits increased $31.8 million, or 2.8%, to $1.1 billion at June 30, 2026, compared to December 31, 2025. The increase in deposits from December 31, 2025 was primarily due to increases in brokered time deposits of $28.3 million and savings and money market accounts of $11.0 million, partially offset by a decrease in retail (non-brokered) time deposits of $17.8 million. Brokered time deposits totaled $264.3 million, or 23.0% of total deposits, at June 30, 2026, compared to $235.9 million, or 21.2% of total deposits at December 31, 2025. Noninterest-bearing demand deposits totaled $100.1 million at both June 30, 2026 and December 31, 2025, and were 8.7% and 9.0% of total deposits at June 30, 2026 and December 31, 2025, respectively.
Borrowings decreased $8.0 million, or 3.2%, to $244.0 million at June 30, 2026, compared to $252.0 million at December 31, 2025, reflecting decreases in other borrowings, partially offset by a $4.0 million increase in FHLB advances.
Stockholders’ equity totaled $148.3 million at June 30, 2026, an increase of $2.5 million, or 1.7%, from December 31, 2025. The increase in stockholders’ equity was primarily attributable to net income of $5.0 million, partially offset by $2.9 million in dividends paid to Company stockholders.
About Richmond Mutual Bancorporation, Inc.
Richmond Mutual Bancorporation, Inc., headquartered in Richmond, Indiana, is the holding company for First Bank Midwest, a community-oriented financial institution offering traditional financial and trust services within its local communities through its branch locations in Cambridge City, Centerville, Fishers, Frankfort, Kirklin, Lebanon, Michigantown, Mulberry, Noblesville, Richmond, Rossville, Shelbyville, Sheridan, Tipton, and Westfield, Indiana, and its locations in Columbus, Sidney, Piqua, and Troy, Ohio.
FORWARD-LOOKING STATEMENTS:
This document and other filings by the Company with the Securities and Exchange Commission (the “SEC”), as well as press releases or other public or stockholder communications released by the Company, may contain forward-looking statements, including, but not limited to, (i) statements regarding the financial condition, results of operations, and business of the Company, (ii) statements about the Company’s plans, objectives, expectations, and intentions and other statements that are not historical facts, and (iii) other statements identified by the words or phrases “will likely result,” “are expected to,” “will continue,” “is anticipated,” “estimate,” “project,” “intends,” or similar expressions that are intended to identify “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. These forward-looking statements are based on current beliefs and expectations of the Company’s management and are inherently subject to significant business, economic, and competitive uncertainties and contingencies, many of which are beyond the Company’s control. In addition, these forward-looking statements are subject to assumptions with respect to future business strategies and decisions that are subject to change. When considering forward-looking statements, keep in mind these risks and uncertainties. Undue reliance should not be placed on any forward-looking statement, which speaks only as of the date made.
The following factors, among others, could cause actual results to differ materially from the anticipated results or other expectations expressed in the forward-looking statements: adverse economic conditions in the Company’s local market areas or other markets where the Company has lending relationships; employment levels, labor shortages, and the effects of persistent inflation, recessionary pressures, or slowing economic growth; changes in interest rate levels and volatility, and the timing and pace of such changes, including actions by the Federal Reserve, which could adversely affect the Company’s revenues and expenses, the value of assets and obligations, and the availability and cost of capital and liquidity; the impact of inflation and monetary and fiscal policy responses thereto, and their impact on consumer and business behavior; the effects of a federal government shutdown, debt ceiling standoff, or other fiscal policy uncertainty; the impact of bank failures or adverse developments at other banks and related negative publicity about the banking industry in general on investor and depositor sentiment; legislative changes; changes in policies by regulatory agencies; the risks of lending and investing activities, including changes in the level and direction of loan delinquencies and write-offs and changes in estimates of the adequacy of the allowance for credit losses on loans and leases; the Company’s ability to access cost-effective funding, including maintaining the confidence of depositors; fluctuations in real estate values and both residential and commercial real estate market conditions; competitive pressures among depository institutions, including repricing and competitors’ pricing initiatives, and their impact on the Company’s market position, loan, and deposit products; changes in management’s business strategies, including expectations regarding key growth initiatives and strategic priorities; the ability to adapt to rapid technological changes, including advancements in artificial intelligence, digital banking platforms, and cybersecurity; legislation or regulatory changes, including but not limited to shifts in capital requirements, banking regulation, tax laws, or consumer protection laws; vulnerabilities in information technology systems or third-party service providers, including disruptions, breaches, or attacks; geopolitical developments and international conflicts, including but not limited to tensions or instability in Eastern Europe, South America, the Middle East, and Asia, or the imposition of new or increased tariffs and trade restrictions, which may disrupt financial markets, global supply chains, commodity prices, or economic activity in specific industry sectors; the effects of climate change, severe weather events, natural disasters, pandemics, epidemics and other public health crises, acts of war or terrorism, domestic political unrest, and other external events on the Company’s business; and other factors described in the Company’s latest Annual Report on Form 10-K and Quarterly Reports on Form 10-Q and other reports filed with or furnished to the Securities and Exchange Commission that are available on our website at www.firstbankrichmond.com and on the SEC’s website at www.sec.gov.
In addition, statements about the potential effects of the Company’s completed merger with Farmers Bancorp on the Company’s business, financial results, and condition may constitute forward-looking statements and are subject to the risk that the actual effects may differ, possibly materially, from what is reflected in the forward-looking statements due to factors and future developments which are uncertain, unpredictable and in many cases beyond the Company’s control, including the following: the potential that anticipated cost savings, synergies, or revenue enhancements from the merger may not be realized or may take longer to achieve than expected; the ability to successfully integrate the operations, systems, personnel, and technologies of the combined company; disruption to customer, employee, or vendor relationships, including key community relationships; diversion of management’s attention from ongoing operations and strategic initiatives as a result of integration activities; lower-than-expected revenues or profitability following the merger; and higher-than expected transaction or integration costs; as well as other factors detailed in the Company’s filings with the SEC.
The factors listed above could materially affect the Company’s financial performance and could cause the Company’s actual results for future periods to differ materially from any opinions or statements expressed with respect to future periods in any current statements. The Company does not undertake, and expressly disclaims any obligation, to publicly release the result of any revisions which may be made to any forward-looking statements to reflect events or circumstances after the date of such statements or to reflect the occurrence of anticipated or unanticipated events except as required by law.
Financial Highlights (unaudited)
Three Months Ended
Six Months Ended
SELECTED
OPERATIONS DATA:
June 30,
2026
March 31,
2026
June 30,
2025
June 30,
2026
June 30,
2025
(In thousands, except for per
share amounts)
Interest income
$ 21,899
$ 21,162
$ 21,346
$ 43,061
$ 42,214
Interest expense
9,825
9,716
10,587
19,541
21,196
Net interest income
12,074
11,446
10,759
23,520
21,018
Provision for credit losses
823
693
745
1,516
1,476
Net interest income after
provision for credit losses
11,251
10,753
10,014
22,004
19,542
Noninterest income
1,580
1,298
1,080
2,878
2,242
Noninterest expense
10,168
8,704
8,110
18,871
16,483
Income before income tax expense
2,663
3,347
2,984
6,011
5,301
Income tax provision
436
562
382
999
731
Net income
$ 2,227
$ 2,785
$ 2,602
$ 5,012
$ 4,570
Shares outstanding
10,505
10,501
10,389
10,505
10,389
Average shares outstanding:
Basic
9,693
9,678
9,558
9,686
9,699
Diluted
9,913
9,860
9,845
9,887
9,964
Earnings per share:
Basic
$ 0.23
$ 0.29
$ 0.27
$ 0.52
$ 0.47
Diluted
$ 0.22
$ 0.28
$ 0.26
$ 0.51
$ 0.46
SELECTED FINANCIAL CONDITION DATA:
June 30,
2026
March 31,
2026
December 31,
2025
September 30,
2025
June 30,
2025
(In thousands, except for per share amounts)
Total assets
$ 1,552,029
$ 1,519,216
$ 1,525,790
$ 1,525,565
$ 1,507,759
Cash and cash equivalents
34,721
34,798
33,130
34,265
27,211
Interest-bearing time deposits
2,850
2,820
2,070
—
300
Investment securities
247,625
247,872
254,663
253,221
252,280
Loans and leases, net of allowance for credit losses
1,207,852
1,174,122
1,176,813
1,178,232
1,167,850
Loans held for sale
—
835
828
1,441
136
Premises and equipment, net
13,563
13,497
13,397
13,427
13,189
Federal Home Loan Bank stock
13,907
13,907
13,907
13,907
13,907
Other assets
31,511
31,365
30,982
31,072
32,886
Deposits
1,146,643
1,106,365
1,114,893
1,118,258
1,096,389
Borrowings
244,000
256,000
252,000
254,000
267,000
Total stockholder’s equity
148,273
144,910
145,781
140,035
132,322
Book value (GAAP)
$ 148,273
$ 144,910
$ 145,781
$ 140,035
$ 132,322
Tangible book value (non-GAAP)
148,273
144,910
145,781
140,035
132,322
Book value per share (GAAP)
14.11
13.80
13.88
13.43
12.74
Tangible book value per share (non-GAAP)
14.11
13.80
13.88
13.43
12.74
The following table summarizes information relating to the Company’s loan and lease portfolio at the dates indicated:
(In thousands)
June 30,
2026
March 31,
2026
December 31,
2025
September 30,
2025
June 30,
2025
Commercial mortgage
$ 419,123
$ 414,875
$ 414,316
$ 420,680
$ 393,632
Commercial and industrial
158,075
145,214
142,508
138,333
140,700
Construction and development
86,201
74,315
71,705
67,446
102,367
Multi-family
207,760
208,034
208,894
216,982
191,750
Residential mortgage
170,149
166,260
171,063
166,594
168,956
Home equity
22,398
21,398
20,147
18,816
19,449
Direct financing leases
143,602
142,979
145,806
146,413
147,193
Consumer
17,951
18,179
19,280
19,914
20,596
Total loans and leases
$ 1,225,259
$ 1,191,254
$ 1,193,719
$ 1,195,178
$ 1,184,643
The following table summarizes information relating to the Company’s deposits at the dates indicated:
(In thousands)
June 30,
2026
March 31,
2026
December 31,
2025
September 30,
2025
June 30,
2025
Noninterest-bearing demand
$ 100,071
$ 99,400
$ 100,091
$ 110,815
$ 106,216
Interest-bearing demand
154,055
152,469
143,863
145,705
147,318
Savings and money market
330,361
316,255
319,337
307,667
303,241
Non-brokered time deposits
297,881
301,725
315,655
305,821
300,143
Brokered time deposits
264,275
236,516
235,947
248,250
239,471
Total deposits
$ 1,146,643
$ 1,106,365
$ 1,114,893
$ 1,118,258
$ 1,096,389
Average Balances, Interest and Average Yields/Cost. The following tables set forth for the periods indicated, information regarding average balances of assets and liabilities as well as the total dollar amounts of interest income from average interest-earning assets and interest expense on average interest-bearing liabilities, resultant yields, interest rate spread, net interest margin (otherwise known as net yield on interest-earning assets), and the ratio of average interest-earning assets to average interest-bearing liabilities. Average balances have been calculated using daily balances. Non-accruing loans have been included in the table as loans carrying a zero yield. Loan fees are included in interest income on loans and are not material.
Three Months Ended June 30,
2026
2025
Average
Balance
Outstanding
Interest
Earned/
Paid
Yield/
Rate
Average
Balance
Outstanding
Interest
Earned/
Paid
Yield/
Rate
(Dollars in thousands)
Interest-earning assets:
Loans and leases receivable
$ 1,207,815
$ 19,790
6.55 %
$ 1,178,026
$ 19,183
6.51 %
Securities
250,647
1,580
2.52 %
251,717
1,611
2.56 %
FHLB stock
13,907
301
8.66 %
13,907
309
8.89 %
Cash and cash equivalents and other
25,214
228
3.62 %
24,156
243
4.02 %
Total interest-earning assets
1,497,583
21,899
5.85 %
1,467,806
21,346
5.82 %
Non-earning assets
40,111
40,536
Total assets
1,537,694
1,508,342
Interest-bearing liabilities:
Savings and money market accounts
343,151
1,845
2.15 %
316,419
1,833
2.32 %
Interest-bearing checking accounts
147,925
401
1.08 %
140,977
373
1.06 %
Certificate accounts
533,159
4,967
3.73 %
538,026
5,606
4.17 %
Borrowings
253,637
2,612
4.12 %
262,088
2,775
4.24 %
Total interest-bearing liabilities
1,277,872
9,825
3.08 %
1,257,510
10,587
3.37 %
Noninterest-bearing demand deposits
100,108
107,351
Other liabilities
13,522
13,222
Stockholders’ equity
146,192
130,259
Total liabilities and stockholders’ equity
1,537,694
1,508,342
Net interest income
$ 12,074
$ 10,759
Net earning assets
$ 219,711
$ 210,296
Net interest rate spread(1)
2.77 %
2.45 %
Net interest margin(2)
3.22 %
2.93 %
Average interest-earning assets to average interest-bearing
liabilities
117.19 %
116.72 %
____________________________________
(1)
Net interest rate spread represents the difference between the weighted average yield earned on interest-earning assets and the weighted average rate paid on interest bearing liabilities.
(2)
Net interest margin represents net interest income divided by average total interest-earning assets.
Six Months Ended June 30,
2026
2025
Average
Balance
Outstanding
Interest
Earned/
Paid
Yield/
Rate
Average
Balance
Outstanding
Interest
Earned/
Paid
Yield/
Rate
(Dollars in thousands)
Interest-earning assets:
Loans and leases receivable
$ 1,195,543
$ 38,901
6.51 %
$ 1,179,329
$ 37,956
6.44 %
Securities
253,649
3,162
2.49 %
256,866
3,264
2.54 %
FHLB stock
13,907
592
8.51 %
13,907
620
8.92 %
Cash and cash equivalents and other
23,064
406
3.52 %
19,177
374
3.90 %
Total interest-earning assets
1,486,163
43,061
5.79 %
1,469,279
42,214
5.75 %
Non-earning assets
39,243
40,278
Total assets
1,525,406
1,509,557
Interest-bearing liabilities:
Savings and money market accounts
331,888
3,505
2.11 %
310,484
3,556
2.29 %
Interest-bearing checking accounts
147,308
798
1.08 %
137,737
697
1.01 %
Certificate accounts
538,356
10,208
3.79 %
544,192
11,403
4.19 %
Borrowings
247,398
5,029
4.07 %
268,343
5,540
4.13 %
Total interest-bearing liabilities
1,264,950
19,540
3.09 %
1,260,756
21,196
3.36 %
Noninterest-bearing demand deposits
99,240
103,316
Other liabilities
13,916
13,477
Stockholders’ equity
147,300
132,008
Total liabilities and stockholders’ equity
1,525,406
1,509,557
Net interest income
$ 23,521
$ 21,018
Net earning assets
$ 221,213
$ 208,523
Net interest rate spread(1)
2.70 %
2.39 %
Net interest margin(2)
3.17 %
2.86 %
Average interest-earning assets to average interest-bearing
liabilities
117.49 %
116.54 %
____________________________________
(1)
Net interest rate spread represents the difference between the weighted average yield earned on interest-earning assets and the weighted average rate paid on interest bearing liabilities.
(2)
Net interest margin represents net interest income divided by average total interest-earning assets.
At and for the Three Months Ended
Selected Financial Ratios and Other Data:
June 30,
2026
March 31,
2026
December 31,
2025
September 30,
2025
June 30,
2025
Performance ratios:
Return on average assets(1)
0.58 %
0.74 %
0.89 %
0.95 %
0.69 %
Return on average equity(1)
6.09 %
7.51 %
9.55 %
10.78 %
7.99 %
Yield on interest-earning assets
5.85 %
5.74 %
5.89 %
5.93 %
5.82 %
Rate paid on interest-bearing liabilities
3.08 %
3.10 %
3.28 %
3.35 %
3.37 %
Average interest rate spread
2.77 %
2.64 %
2.61 %
2.58 %
2.45 %
Net interest margin(1)(2)
3.22 %
3.10 %
3.11 %
3.07 %
2.93 %
Operating expense to average total assets(1)
2.64 %
2.30 %
2.24 %
2.14 %
2.15 %
Efficiency ratio(3)
74.47 %
68.29 %
65.39 %
64.18 %
68.50 %
Average interest-earning assets to average
interest-bearing liabilities
117.19 %
117.79 %
117.86 %
117.25 %
116.72 %
Asset quality ratios:
Non-performing assets to total assets(4)
1.41 %
1.16 %
1.14 %
0.71 %
0.54 %
Non-performing loans and leases to total gross
loans and leases(5)
1.78 %
1.48 %
1.46 %
0.90 %
0.68 %
Allowance for credit losses to non-performing
loans and leases(5)
77.91 %
95.02 %
94.64 %
151.64 %
201.14 %
Allowance for credit losses to total loans and leases
1.39 %
1.41 %
1.38 %
1.37 %
1.37 %
Net charge-offs to average outstanding loans
and leases during the period(1)
0.18 %
0.12 %
0.12 %
0.11 %
0.21 %
Capital ratios:
Equity to total assets at end of period
9.55 %
9.54 %
9.55 %
9.18 %
8.78 %
Average equity to average assets
9.51 %
9.81 %
9.36 %
8.84 %
8.64 %
Common equity tier 1 capital (to risk weighted
assets)(6)
12.99 %
13.37 %
13.38 %
13.11 %
12.99 %
Tier 1 leverage (core) capital (to adjusted
tangible assets)(6)
10.90 %
11.10 %
10.95 %
10.85 %
10.75 %
Tier 1 risk-based capital (to risk weighted
assets)(6)
12.99 %
13.37 %
13.38 %
13.11 %
12.99 %
Total risk-based capital (to risk weighted
assets)(6)
14.24 %
14.62 %
14.64 %
14.36 %
14.24 %
Other data:
Number of full-service offices
13
13
13
12
12
Full-time equivalent employees
174
173
180
179
176
(1)
Annualized
(2)
Net interest income divided by average interest-earning assets.
(3)
Total noninterest expenses as a percentage of net interest income and total noninterest income.
(4)
Non-performing assets consist of nonaccrual loans and leases, accruing loans and leases more than 90 days past due and foreclosed assets.
(5)
Non-performing loans and leases consist of nonaccrual loans and leases and accruing loans and leases more than 90 days past due.
(6)
Capital ratios are for First Bank Richmond.
View original content:https://www.prnewswire.com/news-releases/richmond-mutual-bancorporation-inc-announces-2026-second-quarter-financial-results-302835676.html
SOURCE Richmond Mutual Bancorporation, Inc.

You may like
Technology
World Young Scientist Summit 2026 Opens in Wenzhou, Zhejiang
Published
32 minutes agoon
October 24, 2026By
WENZHOU, China, Oct. 24, 2026 /PRNewswire/ — This is a report by China Daily:
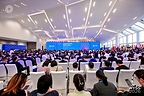
On October 24, the World Young Scientist Summit 2026 opened in Wenzhou, Zhejiang. The event is hosted by the China Association for Science and Technology (CAST), the Zhejiang Provincial People’s Government, and the World Association of Young Scientists. Nearly 800 representatives, including scientists, educators, and entrepreneurs from more than 60 countries and regions, are attending the summit.
He Junke, Vice President of CAST in charge of daily work and First Secretary of its Secretariat; Lian Yimin, Chairman and Party Group Secretary of the Zhejiang Provincial Committee of the Chinese People’s Political Consultative Conference; Marcelo Knobel, Executive Director of The World Academy of Sciences; and Zhang Zhenfeng, Member of the Standing Committee of the CPC Zhejiang Provincial Committee and Secretary of the CPC Wenzhou Municipal Committee, attended the summit and delivered remarks. Yao Gaoyuan, Vice Governor of the Zhejiang Provincial People’s Government, presided over the first segment of the plenary session.
With the theme “Gathering Talents Worldwide to Create a Better Future,” the summit’s annual agenda is “Global Youth Action in the AI Era: Building a Sustainable Future.” It aims to draw on the insights of young people around the world, deepen international sci-tech cooperation, and jointly address questions about young people, science, the world and the future.
Efim Zelmanov, Fields Medalist and Foreign Member of the Chinese Academy of Sciences; Chen Yunji, Deputy Director of the Institute of Computing Technology, CAS, and Director of the National Key Laboratory of Processor Chips; Mary Garson, President of the International Union of Pure and Applied Chemistry; and Lu Chaoyang, Member of the Standing Committee of CAST, Executive Dean of the Shanghai Institute of Advanced Study, University of Science and Technology of China, and Chairman of the Council of the World Association of Young Scientists, delivered keynote speeches respectively on education reform in the AI era, AI and processor chips, young women scientists’ participation in science, and quantum computing. They explored new opportunities for scientific research, talent cultivation, and international cooperation in the AI era.
This year’s summit placed greater emphasis on the growth needs of young scientists, with young talents under the age of 45 accounting for 88 percent of participants. It aimed to build a cluster of international journals, bring together young scientific talent, facilitate a batch of international collaborative projects and advance the application and commercialization of scientific and technological achievements. The summit released the Report on the Distribution and Mobility of Young Scientists in the Field of Embodied Intelligence, launched the World Young Scientist Summit Partner Journal Program and the 2026 World Young Scientist Innovation and Entrepreneurship Growth Support Program. It also published the “Young Scientist Pioneers 2035” list and announced the 2026 Sustainable Development Young Scientist Award. The awards were presented to four Chinese and foreign scientists.
Chen Tianrun, Founder of Hangzhou Moxin Technology Co., Ltd.; Yuan Yang, Assistant to the Dean of the Institute for Interdisciplinary Information Sciences at Tsinghua University; and two of the 2026 Sustainable Development Young Scientist Award winners, César de la Fuente and Nicola Segata, among other Chinese and foreign young scientist representatives, spoke at the flash-talk session to share their research practices and reflections.
In addition, the conference focused on fields such as future manufacturing, quantum information, embodied intelligence, brain-computer intelligence, environmental science, deep-sea resources, and life and health, and held 12 parallel forums. It also included the “Gravitation π” Future Technology and Concept Products Exhibition and Exchange, local thematic side events, and sci-tech and humanities study visits, further building an interdisciplinary, cross-regional and cross-sector platform for youth sci-tech exchange and cooperation.
View original content to download multimedia:https://www.prnewswire.com/news-releases/world-young-scientist-summit-2026-opens-in-wenzhou-zhejiang-302918664.html
SOURCE China Daily
Technology
The Ultimate Send-off to Summer: CSTS Debuts Global Entertainment IP PremierX at New York’s Pier 17, Ushering in a New Era of Live Entertainment
Published
3 hours agoon
October 24, 2026By
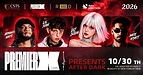
NEW YORK, Oct. 24, 2026 /PRNewswire/ — CSTS Enterprises (‘CSTS’), a New York-based sports, entertainment, integrated media and travel technology group, today announced the official launch of PremierXTM, its flagship live entertainment brand, with a landmark Halloween Weekend event “AFTER DARK” at The Rooftop at Pier 17 in New York on October 30, 2026.
Capping off Seaport’s 2026 Summer Season in unforgettable fashion, the grand finale brings a powerhouse lineup of stars to the PremierXTM stage at Pier 17, featuring Lil Xan, Armani White, DJ Soda, Nate Wyatt, and surprise A-list guest headliners. Set against the iconic Manhattan skyline, the landmark eventing unites chart-topping hip-hop and high-octane electronic music for a festival-grade experience as The Rooftop at Pier 17 transforms into the city’s premier live music destination.
Building on the momentum of the PremierXTM After Party for the 2026 World Cup Final that took place in New York on July 19th, “AFTER DARK” signals the official debut of PremierXTM, a proprietary, New York – born global entertainment IP created by CSTS to deliver defining cultural experiences at the intersection of music, sport, art and lifestyle. Centred on the power of cultural crossover, PremierXTM serves as an international bridge connecting East and West, modern innovation and timeless classical, while uniting world-class artists, creators, performers and audiences through the universal language of entertainment and premium live experiences.
The launch also marks the beginning of a promising relationship with Pier 17, providing a world-class stage for PremierXTM to accelerate its growth in the U.S. and engage international audiences over the long term. By combining PremierXTM’s global entertainment vision with Pier 17’s iconic waterfront setting, the partnership aims to create a premier destination for live experiences, empowering both platforms to expand their global reach, deepen audience engagement, and drive sustainable growth.
As a key pillar of CSTS’ integrated ecosystem spanning entertainment, sports, travel, integrated media and marketing solutions, PremierXTM further strengthens the Group’s ability to create high-impact experiences that connect audiences, destinations and brand partners. With the global live entertainment market projected to grow from approximately US$203 billion in 2025 to US$270 billion by 2030[1], PremierXTM is well-positioned to capitalize on the growing demand for premium, experience-led entertainment while creating long-term value to the Group through recurring audience engagement, tourism and brand partnerships.
“PremierX TM represents a significant milestone in CSTS’ evolution from a leading operator of global sports and hospitality platforms into a creator of world-class entertainment experiences,” said Abel Zhao, Group CEO and Executive Director at CSTS Enterprises. “The season finale at Pier17 marks the beginning of an exciting new chapter for CSTS as we expand our entertainment footprint and introduce a platform designed to deliver iconic live experiences and bring together artists and audiences from across the globe.”
“PremierXTM was built from the ground up as a bespoke platform to champion multicultural talent and visionary creative performers.” said Jason Liu, Regional Director of CSTS USA. “Starting from New York, we are building a scalable global brand that brings iconic live experiences to audiences worldwide while expanding our presence across key entertainment hubs in North America, Asia and Europe.”
Following its New York launch, PremierXTM plans to expand through a broader international rollout across North America, Asia and Europe, with future editions planned as part of a growing network of recurring live entertainment properties and flagship cultural events.
For ticket information on PremierXTM: “AFTER DARK”, visit
https://www.axs.com/events/1644912/after-dark-tickets
About CSTS Enterprises
CSTS Enterprises is an integrated media, entertainment, sports, and travel technology group. Headquartered in New York City, the company develops and partners with intellectual properties and brands to deliver compelling experiences that connect with audiences across the world. In addition to its own initiatives, including Generation CTM and PremierXTM, it collaborates with international IPs including FIFA World Cup, UEFA European Championship, and Formula 1.
CSTS integrates experiential marketing, travel, data, and technology to deliver seamless end-to-end audience experiences. The company engages consumers across physical events and digital channels, executing at scale worldwide, turning complex activations into co-ordinated, measurable outcomes.
[1] Source: Industry research by Markets and Markets, Live Entertainment Market Size, Share, Latest Trends & Growth Analysis, 2025-2030, Live Entertainment Market Size, Share, Latest Trends & Growth Analysis, 2025-2030.
View original content to download multimedia:https://www.prnewswire.com/news-releases/the-ultimate-send-off-to-summer-csts-debuts-global-entertainment-ip-premierx-at-new-yorks-pier-17-ushering-in-a-new-era-of-live-entertainment-302918645.html
SOURCE CSTS Enterprises
Technology
Swanson Vitamins Launches Swanson Vitamins Nexus Pro to Champion Registered Dietitians and Licensed Nutritionists at Every Stage of Their Careers
Published
3 hours agoon
October 24, 2026By
New network for health and nutrition professionals offers CPEU-accredited continuing education, profession-wide promotion, practicum support and exam scholarships
FARGO, N.D., Oct. 24, 2026 /PRNewswire/ — Swanson Vitamins today launched Swanson Vitamins Nexus Pro, a network for health and nutrition professionals. The new initiative champions registered dietitians and licensed nutritionists through every stage of their careers, from students to providers with decades of experience. Created by nutrition professionals for nutrition professionals, Swanson Vitamins Nexus Pro offers educational resources, incentives and investments to support practitioners who share Swanson’s commitment to uncompromising integrity.
Swanson Vitamins Nexus Pro offers tailored resources for both practicing professionals and students. For practicing registered dietitians and licensed nutritionists, the program provides CPEU-accredited continuing education, along with profession-wide promotion of the experts who guide consumers’ wellness decisions. For dietetics and nutrition students, Swanson is investing in the next generation of the profession through practicum support and scholarships toward licensing or credentialing exam fees.
As consumers take a more active role in their health, they are increasingly turning to registered dietitians and licensed nutritionists for accurate, science-backed guidance. Through Swanson Vitamins Nexus Pro, Swanson aims to help nutrition professionals strengthen their credentials and build expertise in areas where consumers are seeking trusted nutritional support.
“Since 1969, we have been committed to uncompromising integrity in service of everyone’s journey to real wellness, and we believe real wellness starts with the experts who guide it,” said Erin Del Ponte, EVP Brand Marketing at Swanson Vitamins. “Registered dietitians and licensed nutritionists translate nutrition science into practical, personalized guidance that helps people make informed decisions about their health. With Swanson Vitamins Nexus Pro, we are proud to support these professionals at every stage of their careers, from students preparing for their credentialing exams to seasoned providers building expertise in the areas that matter most to consumers today.”
Swanson Nexus Pro program highlights
CPEU-accredited continuing education for registered dietitians and licensed nutritionistsProfession-wide promotion of registered dietitians and licensed nutritionistsPracticum support for dietetics and nutrition studentsScholarships to help offset licensing or credentialing exam fees
Applications for Swanson Vitamins Nexus Pro are open and can be submitted HERE. Additional details, including scholarship award amounts and practicum support details, will be announced in the coming weeks.
Swanson Vitamins Nexus Pro was introduced at the Food & Nutrition Conference & Expo, the Academy of Nutrition and Dietetics’ annual conference, held Oct. 24-27 in San Antonio. This initiative builds on Swanson’s longstanding commitment to the nutrition and dietetics community and reflects the company’s continued investment in the professionals who help consumers make informed choices on their journey to real wellness.
Media Assets
Photos HERE
About Swanson Vitamins
Since 1969, Swanson Vitamins has offered high-quality, science-backed vitamins and supplements rooted in one simple belief: proof over promise. Nearly six decades before “wellness” became an industry, Swanson was pioneering trustworthy supplement offerings and upholding uncompromising quality standards through intentional sourcing, rigorous in-house and third-party testing and Good Manufacturing Practices (GMP).
Today, Swanson is a Certified GMP Facility recognized by NSF, backed by an in-house team of nutritionists, dietitians, scientists, chemists and pharmacists with a combined 250-plus years of experience. With more than 1,300 products across 36 categories, Swanson doesn’t chase trends. It sets standards for integrity, quality and clarity in the supplement industry.
Swanson products are available at SwansonVitamins.com, Amazon and iHerb.com. Learn more at SwansonVitamins.com or follow @swansonvitamins on Instagram.
MEDIA CONTACT
Lauren Torrez, Crowe PR
ltorrez@crowepr.com
View original content to download multimedia:https://www.prnewswire.com/news-releases/swanson-vitamins-launches-swanson-vitamins-nexus-pro-to-champion-registered-dietitians-and-licensed-nutritionists-at-every-stage-of-their-careers-302918428.html
SOURCE Swanson Vitamins


World Young Scientist Summit 2026 Opens in Wenzhou, Zhejiang

The Ultimate Send-off to Summer: CSTS Debuts Global Entertainment IP PremierX at New York’s Pier 17, Ushering in a New Era of Live Entertainment

Swanson Vitamins Launches Swanson Vitamins Nexus Pro to Champion Registered Dietitians and Licensed Nutritionists at Every Stage of Their Careers

Send Rakhi to UK swiftly with UK Gifts Portal

Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

Nullmax and Renesas Forge Strategic Partnership to Deliver Competitive ADAS Solutions for the Global Market

Why You Should Build on #NEAR – Co-founder Illia Polosukhin at CV Labs
Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

NEAR End of Year Town Hall 2021: The Open Web World, MetaBUILD 2 Hackathon and 2021 recap
Trending
-
 Technology4 days ago
Sophont Launches Holon-S1 to Reveal Tumor Biology from Routine Pathology Slides
-
 Technology4 days ago
NC AI Officially Releases VARCO Sound, the Generative AI Sound Production Service
-
 Technology5 days ago
OppFi Announces its Third Quarter 2026 Earnings Conference Call
-
 Technology4 days ago
Trinity Acquires Verix, Adding AI-Powered Next-Best-Action and Omnichannel Orchestration to the TrinityEDGE Platform
-
 Coin Market4 days ago
Stablecoin transfers quadruple to $891B as US banks expand adoption: Report
-
 Technology4 days ago
Workato Launches Self-Serve Platform in Singapore, Opening Enterprise AI to a Broader Community of Builders
-
 Technology24 hours ago
Miami Startup BOB Raises $5.5M To Build An AI-Powered Banking Platform
-
 Technology4 days ago
Findem Takes on Candidate Fraud With Authenticity Suite Pro