On October 26, FFR will hold its listing ceremony and first Investor Day at the Nasdaq Tower in New York, where management will share more about FFR’s strategy and business plans, with more details to follow soon.Two new EAI Devices launched including FF Nova—America’s first entry-level EAI humanoid robot under $2,500, and the second is Nova Mini, a humanoid robot for foundational Physical AI education, priced at $299, with the accompanying curriculum at $499.FF EAI launched two new education and developer training initiatives, the Physical AI Spark Program Curriculum and the Nova Reinforcement Learning Developer Program, while also opening enrollment for its developer community to help expand participation in its embodied AI ecosystem.
LOS ANGELES, Oct. 18, 2026 /PRNewswire/ — FF EAI Robotics Ecosystem Inc. (NASDAQ: FFR) (“FFR” or the “Company”), a U.S.-based Embodied AI (EAI) robotics company, today highlighted a weekly business update from YT Jia, Founder and Global CEO of Faraday Future Intelligent Electric Inc. (NASDAQ: FFAI) (“Faraday Future” or “FF”). For purposes of attribution, references to “we,” “our,” and “FF” in the following transcript refer to FFAI and its robotics business, except where FFR named.
“Welcome to Weekly Report 77. This week, let’s start with some big news from FFR. On October 26, we will hold FFR’s listing ceremony and first Investor Day at the Nasdaq Tower in New York. Our management team will share more about our strategy and business plans. We’ll also have the chance to talk with investors face to face. To our stockholders and partners, we hope you can join us and help open this new chapter for FFR. Formal invitations to the event will go out tomorrow! Now, let me share what we’ve been working on this week.
This week, FFR and FFAI jointly launched three new offerings.
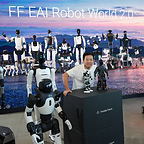
1. Two new EAI Devices. The first is FF Nova—America’s first entry-level EAI humanoid robot under $2,500. Your Physical AI lab in a backpack. The Nova device costs $2,490, and the Developer Skills Package is $390. The second is Nova Mini, our humanoid robot for foundational Physical AI education. The robot is priced at $299, and the accompanying curriculum is $499. With these additions, the “One-Brain Multi-Form Multi-Capability” FF EAI Robot World 2.0 we are building now includes more than 20 EAI Devices across 11 models, seven series, and three robot forms.
2. A new FF EAI Education Skills product—the “Physical AI Spark Program Curriculum.”
3. The Nova Reinforcement Learning Developer Program. We also opened enrollment in our developer community.
Our EAI Brain and Developer Platform Cores also made two breakthroughs this week.
Regarding the EAI brain, The All-New Futurist now fully supports SONIC. That opens up more room for development and applications on more advanced robotics platforms. This is how our approach of combining in-house development with open collaboration is starting to deliver more value.
On the Developer Platform side, we’ve made the NVIDIA SONIC data, models, and deployment solutions based on FF Master fully open source through GitHub and Hugging Face. What does that mean for developers? You now have a complete path from open-source research and testing algorithms to deploying robots and building solutions. And that path is open to universities, research institutions, and industry partners around the world, too.
Over the past few days, we’ve received some questions from stockholders about FFR’s acquisition of FFAI’s robotics business and its independent public listing. Let me take a moment to clarify a few points and explain what this means. Giving the robotics business its own operations, financing, and public listing is much more than moving assets within FFAI. It fundamentally reshapes FFR and unlocks its value. We see this as the starting point for a major breakthrough in business value and a faster release of value in the capital markets. Let me explain this in four areas.
One is a sharper strategic focus. We will concentrate our resources on delivering our “Four-Core Full-Stack AI” robotics strategy. Every dollar we invest, every decision we make, and every financing round will serve that goal. This focus will help us refine what we do, deepen our expertise, expand our scale, and strengthen our business.
Another is a clearer basis for valuation. With its own public listing as a pure-play robotics business, FFR can be valued directly against its industry peers. Its valuation will no longer be held back by other factors affecting FFAI. Combined with continued deliveries at positive contribution margins, this gives FFR significant room to unlock value.
We will also have more transparent business results and cleaner financial statements. You will be able to see how each financing round translates into business performance. That transparency can help attract strategic investors and long-term capital. After closing, FFR will have almost no debt. Its balance sheet, income statement, and cash flow statement will be cleaner, making the company’s value easier to see.
The fourth area is lower funding needs and financing costs. FFR has seven unique advantages, including our “Four-Core Full-Stack AI” EAI technology and asset-light operating model. Building on these strengths, we aim to achieve positive operating cash flow no later than the third quarter of 2028. Until then, we expect to need no more than $150 million in total financing.
For FFAI, once the transaction closes, we will remain FFR’s controlling and majority stockholder and continue to share in its potential future growth in value. As a Physical AI investment company following a Berkshire-style model, FFAI will share further business updates soon. We want to reward our stockholders for your continued support.
Over the years, we’ve received encouragement, faced ridicule, and taken harsh criticism, yet we’ve seldom felt the need to explain ourselves. Our passion for building a business is still there. It comes from working alongside people who share our vision, and driving change in the industry together. Failure itself doesn’t stop us. What stops us is losing the belief that we can try again. “Try again.” A message to myself, and to every entrepreneur who keeps going. Thank you for being part of this journey. See you next week.”
About FF EAI Robotics Ecosystem Inc.
FF EAI Robotics Ecosystem Inc. (NASDAQ: FFR) (renamed from AIxCrypto Holdings, Inc. and AIXC, effective September 30, 2026) is a U.S.-based Embodied AI (EAI) robotics company that is in the process of acquiring the FF EAI Robotics business. Upon completion of the acquisition, the Company will focus on the research and development, manufacturing, commercialization, and deployment of intelligent robotic technologies, products, and industry solutions.
The Company is committed to building a “Four-Core Full-Stack” AI ecosystem covering the full lifecycle of robotics, consisting of EAI Brain & Developer Platform, EAI Devices, Industry Productivity Solutions, and EAI Data Factory. Guided by the technology and product philosophy of “One Brain, Multi-forms, Multi-capabilities,” the Company aims to empower humanoid, biomimetic, and other robotic form factors through a unified EAI Brain, while continuously expanding their multi-task and multi-scenario capabilities. The ecosystem is designed to support the full robotics lifecycle, including R&D, deployment, data collection and training, operations, and commercial applications.
The FF EAI Robotics business has already achieved commercial deliveries of humanoid and biomimetic robotic products. Through its multi-form-factor robotic products, EAI technology platform, closed-loop data capabilities, and industry solutions, the business continues to advance the scaled adoption of robotics across real-world applications. The Company also operates RoboShare, a robot-sharing and services platform designed to connect robotic assets, service capabilities, customer demand, and ecosystem partners, further strengthening its robotics commercialization and service ecosystem.
For more information, visit www.ff.com.
About Faraday Future
Founded in 2014, Faraday Future (FF) is a U.S.-based Physical AI ecosystem company dedicated to reshaping the future of robotics and mobility solutions through AI innovation and technologies. FF focuses on two major product strategies within the Embodied AI (EAI) robotics business: EAI humanoid and bionic robots, and EAI automotive-focused robots. By building a “Four-Core Full-Stack AI” ecosystem of EAI Brain and Developer Platform, EAI Devices, Industry Productivity Solutions and EAI Data Factory, FF aims to create an evolutionary flywheel: scaled device delivery, data collection and training, continuous evolution of the EAI Brain, stronger product capability, and even larger-scale delivery and deployment. Through this flywheel, FF seeks to maximize its commercial value and lead to the advancement of Physical AI. For more information, please visit Faraday Future’s official website: https://www.ff.com/
FFR Forward-Looking Statements
This communication, including any presentation, press release, investor materials or other document of which it forms a part (this “Communication”), contains “forward-looking statements” within the meaning of the “safe harbor” provisions of the Private Securities Litigation Reform Act of 1995, as amended, and other securities laws, regarding FF EAI Robotics Ecosystem Inc. (“FFR,” the “Company,” “us,” “our,” or “we”) and our industry. All statements, whether written or oral, other than statements of historical fact, including any financial projections and any statements regarding future events, our strategy, our transition to robotics operations, our plans for RoboShare, our digital asset disposition plans, the proposed acquisition of the FF EAI Robotics business, the projections referenced in this communication, our name and ticker change, any related financing, and the anticipated benefits and timing of the foregoing, our objectives, expectations, or anticipated actions or results, are forward-looking statements. You can often identify forward-looking statements by words such as “may,” “might,” “will,” “shall,” “should,” “expects,” “plans,” “anticipates,” “could,” “intends,” “targets,” “projects,” “contemplates,” “believes,” “estimates,” “predicts,” “potential,” “goal,” “objective,” “seeks,” “likely,” or “continue,” or the negative of these terms or other similar expressions; the absence of these words does not mean a statement is not forward-looking. These statements reflect our current expectations and projections about future events as of the date of this Communication and are necessarily based on estimates and assumptions that, while considered reasonable by management, are inherently uncertain. FFR can give no assurance that such forward-looking statements or financial projections will prove to be correct.
Actual results may differ materially from those expressed or implied by these forward-looking statements as a result of numerous risks and uncertainties, both general and specific, including, but not limited to:
The proposed acquisition transaction and PIPE. The definitive agreements may be terminated in accordance with their terms, and the proposed transactions may not be completed on the terms described or at all; the conditions to closing, including the completion of FFAI’s internal restructuring of the robotics business, the execution of key employee agreements and other customary conditions, and the parties’ ability to satisfy them; the risk that the stockholder approval required under Nasdaq listing rules for the conversion of the preferred stock issued as consideration is not obtained or is delayed, and the effect of the conversion restrictions and the information statement process on the timing of conversion; the timing of the transaction and the costs of pursuing it; the issuance of a substantial number of shares as consideration and the resulting dilution to existing stockholders; the fact that the counterparty is our controlling stockholder, that it will hold a substantial majority of our outstanding shares following closing, that certain members of management serve both companies, and the conflicts of interest inherent in the transaction; the risk that the agreed valuations do not reflect the market value of our shares or of the acquired business; our dependence on the counterparty for transition, supply and support following any closing; the scope and enforceability of the non-competition and governance arrangements; the consequences of the transaction under Nasdaq listing rules, including the possibility that Nasdaq determines that the transaction requires us to satisfy initial listing requirements in connection with a business combination, change of control or change in the nature of our business; the risk that the PIPE financing, on which the transaction is not conditioned, is not completed on the anticipated terms or at all; the risk of litigation relating to the transaction; our ability to integrate and operate the acquired business; and the risk that the acquired business performs differently than anticipated.
Projections. The projections referenced in this communication were prepared by FFAI management for the FF EAI Robotics business on a standalone basis and do not reflect our existing business, transaction-related expenses or the combined company. We have not independently verified them or adopted them as guidance. They were not prepared with a view toward public disclosure or toward compliance with the published guidelines of the Securities and Exchange Commission or the American Institute of Certified Public Accountants regarding prospective financial information, and no independent registered public accounting firm has examined, compiled or performed any procedures with respect to them, and none expresses an opinion or any other form of assurance with respect to them. The projections reflect estimates and assumptions that are inherently uncertain and subject to change, including through due diligence and the review of our special committee and its financial advisor. Actual results are likely to differ, and may differ materially.
Liquidity, capital and going concern. Our limited cash and liquidity position and our history of operating losses and negative operating cash flow; substantial doubt regarding our ability to continue as a going concern, as described in our periodic reports; our need to obtain additional financing on acceptable terms or at all, and the substantial dilution to existing stockholders that additional financing may cause, including any financing completed in connection with the proposed transaction, which may not be completed or may be on less favorable terms than anticipated; our ability to fund operations pending and following the disposition of our digital asset positions; and our ability to satisfy the continued listing requirements of The Nasdaq Stock Market, including stockholders’ equity, minimum bid price and other applicable standards.
Our strategic transition and the disposition of digital assets. Risks associated with a fundamental shift in our business strategy and the redeployment of resources from a digital asset treasury strategy to robotics operations; our ability to execute the disposition of our digital asset positions in an orderly manner and on acceptable terms; the risk that amounts realized on disposition are materially less than carrying value as a result of price volatility, market depth, execution timing, custody or transfer constraints, or other limitations; tax, accounting and regulatory consequences of the dispositions; the continued volatility and regulatory uncertainty associated with digital assets and cryptocurrencies during the wind-down period; the concentration of a substantial portion of our assets in a single equity investment, including an investment in a related party, and the illiquidity, valuation uncertainty, holding-period and transfer restrictions associated with that investment; and risks arising from our relationships and agreements with related parties and significant stockholders.
Our robotics operations business. Our limited operating history in robotics operations and commercialization and the absence of a meaningful revenue history; the early stage of RoboShare and the risk that customer demand, repeat demand, pricing, utilization or unit economics do not develop as anticipated; our dependence on a small number of customers, on a single initial geographic market, and on individual events or engagements, and the risk that the loss of, or a change in the terms of, any such relationship has a disproportionate effect; our dependence on third-party robot owners, operators, suppliers, original equipment manufacturers and local partners, and on their willingness to make robots available on our platform; risks relating to the availability, cost, quality, maintenance, transport, insurance and technological obsolescence of robots and related equipment, and to supply chains, tariffs and trade measures affecting them; and our ability to expand into additional markets and to attract and retain participants on both sides of our marketplace.
Operations, safety and liability. Risks of property damage, personal injury or death arising from the operation of humanoid robots, quadrupeds and other autonomous or semi-autonomous machines in proximity to performers, employees, guests and the public, including at live events and in uncontrolled environments; product liability, premises liability, negligence and related claims and the adequacy, scope, availability and cost of our insurance coverage and of contractual indemnities from customers, owners and suppliers; the allocation of responsibility among us, robot owners, venues, event producers and customers; permitting, licensing, occupational safety and event-specific regulatory requirements; and the reputational consequences of any safety incident.
Technology, data and intellectual property. Systems, network, telecommunications or service disruptions, failures, defects or cyber-attacks; the performance, reliability and autonomy limitations of robotic systems and of the software, models and networks that support them; our collection, use, storage, transmission and protection of personal information, including images and any biometric or biometric-adjacent data captured in the course of robot deployments, and evolving privacy, biometric and artificial intelligence laws and regulations across the jurisdictions in which we operate or intend to operate; our ability to obtain, maintain, protect and enforce our intellectual property rights and to defend against third-party claims of infringement or misappropriation; and our reliance on third-party technology, platforms and licenses.
Legal, regulatory and general. The regulated industries and jurisdictions in which we operate; current or future laws or regulations and new interpretations of existing laws or regulations, including those applicable to digital assets, robotics, autonomous systems, consumer protection, advertising and endorsements; the risk that our marketplace arrangements, or the manner in which they are described, are characterized differently than we intend by regulators or courts; the failure of counterparties to perform their contractual obligations; litigation, regulatory inquiries, investigations and enforcement actions, and their costs and outcomes; business, economic, market and capital-market conditions; competition in our industry; changes in market demand for, and the pricing of, our products and services; our ability to define, design and release new products and services in a timely manner that meet customer needs; our ability to attract, retain and motivate qualified personnel, including key management; our ability to manage our growth and our transition; and our ability to maintain effective internal control over financial reporting and disclosure controls and procedures.
This list of factors is not exhaustive. Additional risks and uncertainties are described more fully in our filings with the U.S. Securities and Exchange Commission (the “SEC”), including our Annual Report on Form 10-K for the year ended December 31, 2025, our Quarterly Reports on Form 10-Q, and our subsequent filings, which are available on the SEC’s website at www.sec.gov. Investors are urged to review the liquidity, capital resources and going concern disclosures contained in those reports.
The forward-looking statements in this Communication speak only as of the date hereof. Except as required by law, neither FFR nor any other person undertakes any obligation to update or revise any forward-looking statement or financial projection set out herein, whether as a result of new information, future events or otherwise. This Communication is provided for informational purposes only, does not constitute an offer to sell or the solicitation of an offer to buy any security, and does not constitute investment, tax or legal advice or any investment recommendation, and does not take into account the investment objectives or financial situation of any person. FFR reserves the right to amend or replace the information contained herein, in whole or in part, at any time, and undertakes no obligation to notify any recipient thereof. Readers are cautioned not to place undue reliance on these forward-looking statements. This caution is made under, and these forward-looking statements are intended to be covered by, the safe-harbor provisions of the Private Securities Litigation Reform Act of 1995.
FFAI FORWARD LOOKING STATEMENTS
Important factors that may affect actual results or outcomes include, among others: the Company’s ability to continue as a going concern and improve its liquidity and financial position; the Company’s ability to pay its outstanding obligations, which it currently lacks; the availability of sufficient share capital to meet its current obligations and execute on its strategy; the willingness of convertible debt investors to fund the Company; demand for the Company’s robotics products; competition in the robotics industry, which includes companies with far superior experience, funding and name recognition; the ability of the Company to build an EAI education ecosystem that serves both the B2C consumer market and the B2B institutional education market; the acceptance by teachers and students of the Company’s robotics products in the education market; the ability of the Company to expand into additional markets for its robotics products; the Company’s reliance on a single OEM for most of its robotics products; the Company’s reliance on Chinese OEMs for all of its robotics products; the possibility of the federal government banning imports of Chinese robotics products; the Company’s ability to get the planned robotics products to comply with all applicable U.S. rules and regulations; the ability of the robotics OEM to timely supply robotics to the Company; tariff uncertainty for imported products, particularly from China; the ability of the Company to close its transaction with FF EAI Robotics Ecosystem Inc. (FFR) for the sale of its robotics business; demand from automobile dealers for robotics products; the Company’s ability to homologate FX vehicles for sale; the Company’s ability to secure the necessary funding to execute on the FX strategy, which is substantial; the Company’s ability to secure an occupancy certificate covering all of its Hanford facility; the Company’s ability to remediate its material weaknesses in internal control over financial reporting and the risks related to the restatement of previously issued consolidated financial statements; the Company’s limited operating history and the significant barriers to growth it faces; the Company’s history of substantial losses and expectation of continued losses; the success of the Company’s payroll expense reduction plan; the Company’s ability to execute on its plans to develop and market its vehicles and the timing of these development programs; the Company’s ability to execute on its plans to enter the robotaxi and cybercab industries; the Company’s estimates of the size of the markets for its vehicles and cost to bring those vehicles to market; the rate and degree of market acceptance of the Company’s vehicles; the Company’s ability to cover future warranty claims; the success of other competing manufacturers; the performance and security of the Company’s vehicles; current and potential litigation involving the Company; the Company’s ability to receive funds from, satisfy the conditions precedent of and close on the various financings described elsewhere by the Company; the result of future financing efforts, the failure of any of which could result in the Company seeking protection under the Bankruptcy Code; the Company’s indebtedness; the Company’s ability to use its “at-the-market” program; insurance coverage; general economic and market conditions impacting demand for the Company’s products; potential negative impacts of a reverse stock split; potential cost, headcount and salary reduction actions may not be sufficient or may not achieve their expected results; circumstances outside of the Company’s control, such as natural disasters, climate change, health epidemics and pandemics, terrorist attacks, and civil unrest; risks related to the Company’s operations in China; the success of the Company’s remedial measures taken in response to the Special Committee findings; the Company’s dependence on its suppliers and contract manufacturer; the Company’s ability to develop and protect its technologies; the Company’s ability to protect against cybersecurity risks; and the ability of the Company to attract and retain employees, any adverse developments in existing legal proceedings or the initiation of new legal proceedings; the volatility of the Company’s stock price; the ability of the Company to maintain its stock price above $1.00; and the ability of the Company to maintain compliance with Nasdaq regulations for continued listing. You should carefully consider the foregoing factors and the other risks and uncertainties described in the “Risk Factors” section of the Company’s Form 10-Q for the quarter ended June 30, 2026, filed with the SEC on August 13, 2026; the quarter ended March 31, 2026, filed with the SEC on May 14, 2026; and Form 10-K filed with the SEC on March 31, 2026, and other documents filed by the Company from time to time with the SEC.
View original content to download multimedia:https://www.prnewswire.com/news-releases/ff-eai-robotics-ecosystem-inc-ffr-highlights-faraday-future-founder-and-global-ceo-yt-jias-weekly-investor-update-three-new-product-offerings-launched-more-details-on-ffrs-acquisition-of-ffais-robotics-business-and-indepen-302912061.html
SOURCE FF EAI Robotics Ecosystem Inc.






 Technology5 days ago

 Technology4 days ago

 Technology3 days ago

 Coin Market3 days ago


 Technology4 days ago

 Technology3 days ago