Connect with us

Technology

ECARX Announces Third Quarter 2026 Unaudited Financial Results

Published

on

LONDON, Nov. 4, 2026 /PRNewswire/ — ECARX Holdings Inc. (Nasdaq: ECX) (“ECARX” or the “Company”), a leading global automotive intelligence company, today announced unaudited financial results for the quarter ended September 30, 2026.

Ziyu Shen, ECARX CEO, commented, “The third quarter was defined by disciplined execution across our product pipeline and financial results. Our continued shift toward higher-end Antora® and Pikes® solutions, together with the careful management of our supply chain and higher memory costs, are directly supporting revenue growth.

Strategically, we continue to move up the value chain by owning more of our technology stack. At the end of the quarter, we completed the acquisition of the Flyme software business, giving us ownership of the application layer that drivers use every day and opening up new recurring software revenue opportunities. We have entered into a non-binding MOU with Arm to co-develop next-generation AI compute systems that can be applied in automotive and beyond. And, we are also finalizing a partnership with a leading European luxury automaker on a Joint Cockpit AI Innovation Lab built on Flyme OS to further drive growth up the value chain.

Our technology is proven in more than 12 million vehicles, and the same stack can now bring AI from the cloud to the edge across a much wider range of intelligent devices. By expanding our product portfolio, growing our partner ecosystem and accelerating global market penetration, we are building ECARX into a technology partner for a substantially larger market.”

Third Quarter 2026 Financial Results:

During the quarter, ECARX acquired 100% equity interest in Hubei Qiguang Technology Co., Ltd. (“Qiguang”), an entity under common control. Comparative financial information is restated by combining assets, liabilities, revenues, expenses and equity of ECARX and Qiguang using the pooling-of interests method. All intercompany transactions and balances between the combining entities have been eliminated.

During this quarter, the Company identified errors in its previously issued consolidated financial statements relating to the accounting for certain government subsidies recognized in 2021 and 2022. Management evaluated the errors and concluded that they were not material to the previously issued financial statements, but would be material to the current-period financial statements if left uncorrected. Accordingly, to correct these errors and enhance the comparability of the financial information presented, the Company has made correcting adjustments to other current liabilities and equity as of the beginning of the earliest comparative period presented.

Total revenue was US$240.8 million, up 10% year-over-year (“YoY”).Sales of goods revenue was US$222.7 million, up 23% YoY. The increase was mainly attributable to the pricing adjustment implemented to offset the impact of elevated memory costs, as well as the sales volume increase compared to the third quarter last year.Software license revenue was US$0.4 million, down 56% YoY, primarily due to a decrease of sales volume for software licenses compared to the third quarter last year.Service revenue was US$17.7 million, down 53% YoY. The decline is attributable to the seasonal nature of vehicle model launches by our partners. While new model launches peaked in the second quarter of 2026, the pace of project launches subsequently experienced a notable deceleration in the third quarter.Total cost of revenue was US$223.9 million, up 30% YoY, driven primarily by rising memory costs associated with the sales of goods.Gross profit was US$16.9 million, down 65% YoY, resulting in a gross margin of 7.0%. Cost escalation in the third quarter exceeded what our current pricing was able to offset. Consequently, passing on further cost increases proved more challenging, with a larger portion being absorbed internally to support volume growth and maintain partnership commitments, and therefore memory costs remain a drag on profitability. In addition, the decrease in service revenue also led to a decline in service margin. As a result, gross margin decreased from 21.9% to 7.0% YoY.Research and development expenses were US$27.5 million, down 12% YoY, primarily driven by the continued resource prioritization that enhanced operational efficiencies and synergies from R&D integration and the internal deployment of AI across our business to reduce structural costs.Selling, general and administrative expenses and others, net were US$25.6 million, up 11% YoY, reflecting a US$6.7 million impairment recorded in the third quarter of 2026 against the convertible bonds previously issued by DreamSmart. Excluding this amount, the remaining expenses declined by US$4.2 million, or down 18% YoY, primarily driven by the continued improvement in global operating efficiencies and lower share-based compensation expenses incurred during the quarter.Net loss was US$48.6 million, compared with US$8.4 million during the same period last year. The change was mainly driven by the decrease of gross margin, as well as an increase in fair value losses of an equity security and finance expenses.Adjusted EBITDA (non-GAAP) loss was US$37.7 million, compared with adjusted EBITDA (non-GAAP) loss of US$0.9 million in the same period last year. See “Non-GAAP Financial Measure.”Total cash as of September 30, 2026 was US$53.7 million, compared with $165.5 million at June 30, 2026. During the quarter, we paid $191.5 million for the acquisition of Flyme software business, funded by a combination of cash reserves and $67.8 million of bank financing drawn in the quarter. The remaining change primarily reflects changes in operating cash outflow and working capital to support new program launches, funded through $30.5 million in bank financing.Looking ahead, our visibility into the remainder of the year gives us the confidence around our strategic trajectory:Based on our current backlog and accelerating commercial pipeline, we are reiterating our full-year 2026 guidance of US$1.0-US$1.1 billion in total revenue.We expect global memory costs to continue to weigh on our gross margin and operating profitability over the next few quarters, including the fourth quarter of 2026. However, we have been proactive in managing this environment, as demonstrated in the prior quarters and again now. We continue to work with customers and suppliers to mitigate the impact through pricing adjustments, operational efficiencies, and product mix optimization. We continue to view these pressures as manageable and remain focused on protecting the long-term profitability profile of the business.

Recent Business Development Highlights and Updates:

Expanding Global Footprint and Automaker Partnerships

More than 12 million vehicles on the road globally with ECARX technologies as of September 30, 2026, spanning across 18 OEMs, 28 brands, and 159 markets, with multiple additional partnership discussions advancing.Flyme Auto recorded more than 1.2 million vehicle deployments from January to September 2026, bringing total cumulative deployments of Flyme Auto by ECARX to over 3.5 million vehicles.Finalizing partnership with a leading European luxury automaker to establish a Joint Cockpit AI Innovation Lab based on Flyme OS, developing next-generation intelligent cockpit systems customized for the automaker’s vehicles in China.Continued industrialization of the Volkswagen Group program, remaining firmly on track with engineering, supply chain and support infrastructure build-out across Latin America ahead of the expected 2027 launch.

Deepening Innovation-Driven R&D Ecosystem

Completed the acquisition of the Flyme software business on September 30, 2026, expanding capabilities beyond hardware into higher-value software ecosystem services, with Flyme operating as an independent software division.Tencent Cloud’s WorkBuddy AI-powered smart work assistant will be integrated with Flyme AIOS, expanding AI capabilities across the Flyme ecosystem.Signed a non-binding memorandum of understanding with Arm to co-develop AI compute platforms for automotive applications. The partnership builds upon the years-long relationship with Arm China, with whom ECARX co-incubated SiEngine.

Technological Advancements and Product Launches

Shipped approximately 721,000 units during the quarter, with high-end Antora® solutions accounting for 30% of shipments, compared to 25% in the same period last year.Initiated mass production for 21 new vehicle models across 5 brands, 6 of which are designated for markets outside of China, such as Korea.Secured 23 vehicle design wins during the quarter, further strengthening the Company’s commercial pipeline and long-term revenue momentum.

Conference Call and Webcast Details

ECARX will host a webcast of its earnings conference call today, Wednesday, November 4, 2026, at 8:00 a.m. EST. To access the webcast, visit the News and Events section of the ECARX Investor Relations website, or visit the following link – https://edge.media-server.com/mmc/p/e4i8peb6/lan/en

To join the earnings call by telephone, participants must preregister at https://register-conf.media-server.com/register/BI9ffd14a76c2a4f01aa0a3d8d55eed7b0 to receive dial-in information.

A replay of the webcast and presentation materials will be available on the Company’s Investor Relations website under the results and reports section following the event.

About ECARX

ECARX (Nasdaq: ECX), headquartered in London, is a leading global automotive intelligence company. ECARX provides the intelligent brain that powers the next generation of software-defined and AI defined vehicles. The company delivers end-to-end, full-stack solutions spanning advanced system-on-chip hardware, high-performance central computing platforms, intelligent cockpit technology, Advanced Driver Assistance Systems, cloud connectivity and physical AI, alongside bespoke vehicle software and intelligent operating systems.

As automakers transition to software-first and AI-first vehicle architectures, ECARX empowers automakers to streamline integration, reduce systemic complexity and optimize long-term cost efficiency. ECARX’s proven technology is deployed in around 12 million vehicles worldwide, and is currently partnered with 18 global automakers and 28 vehicle brands to shape the future of automotive intelligence.

Founded in 2017 and listed on Nasdaq in 2022, ECARX operates from 15 major international locations across Europe, the Americas and Asia, with a global team of over 1,400 employees.

Forward-Looking Statements

This release contains statements that are forward-looking statements within the meaning of the U.S. Private Securities Litigation Reform Act of 1995. These statements are based on management’s beliefs and expectations as well as on assumptions made by and data currently available to management, appear in a number of places throughout this document and include statements regarding, amongst other things, results of operations, financial condition, liquidity, prospects, growth, strategies and the industry in which we operate. The use of words “expects”, “intends”, “anticipates”, “estimates”, “predicts”, “believes”, “should”, “potential”, “may”, “preliminary”, “forecast”, “objective”, “plan”, or “target”, and other similar expressions are intended to identify forward-looking statements. Forward-looking statements, including statements regarding our intentions, beliefs or current expectations concerning, among other things, results of operations, financial condition, liquidity, prospects, growth, strategies, future market conditions or economic performance and developments in the capital and credit markets and expected future financial performance, and the markets in which we operate, are not guarantees of future performance and are subject to a number of risks and uncertainties that could cause actual results to differ materially.

For a discussion of these and other risks and uncertainties that could cause actual results to differ materially from those expressed in any forward-looking statement, see ECARX’s filings with the U.S. Securities and Exchange Commission. ECARX undertakes no obligation to update or revise forward-looking statements to reflect subsequent events or circumstances, except as required by applicable law.

Non-GAAP Financial Measure

The Company uses adjusted EBITDA (non-GAAP) in evaluating its operating results and for financial and operational decision-making purposes. Adjusted EBITDA is defined as net loss excluding interest income, interest expense, income tax expense, depreciation of property and equipment, amortization of intangible assets, and share-based compensation expenses.

The Company presents this non-GAAP financial measure because it is used by the management to evaluate the Company’s operating performance and formulate business plans. The Company believes that the non-GAAP measure helps identify underlying trends in its business that could otherwise be distorted by the effects of certain expenses that are included in net loss. The Company also believes that the use of the non-GAAP measure facilitates investors’ assessment of its operating performance.

Adjusted EBITDA (non-GAAP) should not be considered in isolation or construed as alternatives to net loss or any other measures of performance or as indicators of the Company’s operating performance. Investors are encouraged to compare the Company’s historical adjusted EBITDA (non-GAAP) to the most directly comparable GAAP measure, net loss. Adjusted EBITDA (non-GAAP) presented here may not be comparable to similarly titled measures presented by other companies. Other companies may calculate similarly titled measures differently, limiting their usefulness as comparative measures to the Company’s data. The Company encourages investors and others to review the financial information in its entirety and not rely on a single financial measure.

For more information on the non-GAAP financial measure, please see the table captioned “Unaudited Reconciliation of GAAP and Non-GAAP Results” set forth at the end of this press release.


ECARX Holdings Inc.

Unaudited Condensed Consolidated Balance Sheets

As of

December 31,
2025

As of

September 30,
2026

Millions, except otherwise noted

US$

US$

ASSETS

Current assets

Cash

87.1

42.2

Restricted cash

6.1

11.5

Short-term investments

31.2

47.2

Accounts receivable – third parties, net

14.8

55.8

Accounts receivable – related parties, net

190.0

221.9

Notes receivable

6.0

3.3

Inventories

62.3

244.5

Amounts due from related parties

53.7

24.2

Prepayments and other current assets

36.3

70.3

Total current assets

487.5

720.9

Non-current assets

Long-term investments

61.5

50.8

Property and equipment, net

28.2

41.8

Intangible assets, net

45.6

45.8

Operating lease right-of-use assets

16.8

15.4

Goodwill

16.5

17.2

Other non-current assets – third parties

30.2

46.1

Other non-current assets – related parties

—

9.5

Total non-current assets

198.8

226.6

Total assets

686.3

947.5

LIABILITIES

Current liabilities

Short-term borrowings

310.7

366.7

Accounts payable – third parties

194.2

390.5

Accounts payable – related parties

102.6

106.1

Notes payable

19.3

28.1

Amounts due to related parties

54.6

115.1

Contract liabilities, current – third parties

0.1

0.1

Contract liabilities, current – related parties

7.3

3.1

Operating lease liabilities – current

5.0

5.4

Convertible notes payable-current

38.8

16.7

Accrued expenses and other current liabilities

99.9

100.1

Income tax payable

1.0

0.7

Total current liabilities

833.5

1,132.6

Non-current liabilities

Long-term borrowings

5.6

181.8

Convertible notes payable, non-current

60.3

116.6

Operating lease liabilities, non-current

15.7

14.0

Warrant liabilities, non-current

1.1

0.5

Provisions

17.8

19.7

Other non-current liabilities – third parties

20.7

29.4

Deferred tax liabilities

5.2

4.8

Total non-current liabilities

126.4

366.8

Total liabilities

959.9

1,499.4

Mezzanine equity

Redeemable non-controlling interests

—

15.0

Total mezzanine equity

—

15.0

SHAREHOLDERS’ DEFICIT

Ordinary shares

—

—

Additional paid-in capital

1,018.0

831.6

Treasury shares, at cost

(30.0)

(39.9)

Accumulated deficit

(1,237.1)

(1,321.4)

Accumulated other comprehensive loss

(21.1)

(33.6)

Total deficit attributable to ordinary shareholders

(270.2)

(563.3)

Noncontrolling interests

(3.4)

(3.6)

Total shareholders’ deficit

(273.6)

(566.9)

Liabilities and shareholders’ deficit

686.3

947.5


ECARX Holdings Inc.

Unaudited Condensed Consolidated Statements of Comprehensive Loss

Nine Months Ended

September 30

Three Months Ended

September 30

2025

2026

2025

2026

Millions, except share data and per share data, or otherwise noted

US$

US$

US$

US$

Revenue

Sales of goods revenue

433.6

532.9

181.7

222.7

Software license revenue

27.7

2.7

0.9

0.4

Service revenue

82.0

61.9

37.3

17.7

Total revenue

543.3

597.5

219.9

240.8

Cost of goods sold

(380.2)

(477.7)

(153.3)

(213.2)

Cost of software licenses

(1.1)

(1.1)

(0.3)

(0.3)

Cost of services

(48.2)

(28.2)

(18.1)

(10.4)

Total cost of revenue

(429.5)

(507.0)

(171.7)

(223.9)

Gross profit

113.8

90.5

48.2

16.9

Research and development expenses

(116.1)

(88.2)

(31.4)

(27.5)

Selling, general and administrative expenses and others, net

(75.6)

(70.2)

(23.1)

(25.6)

Total operating expenses

(191.7)

(158.4)

(54.5)

(53.1)

Loss from operation

(77.9)

(67.9)

(6.3)

(36.2)

Interest income

3.2

3.4

1.6

0.9

Interest expense

(13.6)

(26.0)

(3.5)

(8.0)

Share of results of equity method investments

0.4

13.7

0.3

(0.5)

Others, net

3.3

(6.7)

(0.6)

(5.2)

Loss before income taxes

(84.6)

(83.5)

(8.5)

(49.0)

Income tax expense

(2.0)

(0.6)

0.1

0.4

Net loss

(86.6)

(84.1)

(8.4)

(48.6)

Net loss (income) attributable to nonredeemable noncontrolling interests

3.1

0.1

(0.5)

(0.2)

Net loss attributable to redeemable noncontrolling interests

—

2.1

—

0.4

Net loss attributable to ECARX Holdings Inc.

(83.5)

(81.9)

(8.9)

(48.4)

Accretion of redeemable noncontrolling interests

—

(2.4)

—

(0.6)

Net loss attributable to ECARX Holdings Inc. ordinary shareholders

(83.5)

(84.3)

(8.9)

(49.0)

Net loss

(86.6)

(84.1)

(8.4)

(48.6)

Other comprehensive loss (income):

Fair value change of available-for-sale debt investment, net of nil income
taxes

—

(1.9)

—

0.9

Foreign currency translation adjustments, net of nil income taxes

(4.9)

(10.7)

0.2

(2.5)

Comprehensive loss

(91.5)

(96.7)

(8.2)

(50.2)

Comprehensive loss (income) attributable to nonredeemable noncontrolling
interests

3.0

0.2

(0.7)

(0.1)

Comprehensive loss attributable to redeemable noncontrolling interests

—

2.1

—

0.4

Accretion of redeemable noncontrolling interests

—

(2.4)

—

(0.6)

Comprehensive loss attributable to ECARX Holdings Inc.

(88.5)

(96.8)

(8.9)

(50.5)

Loss per ordinary share

 – Basic loss  per share, ordinary shares

(0.25)

(0.22)

(0.03)

(0.13)

 – Diluted loss per share, ordinary shares

(0.25)

(0.22)

(0.03)

(0.13)

Weighted average number of ordinary shares used in computing loss per
ordinary share

 – Weighted average number of ordinary shares – Basic

337,824,547

375,154,378

339,033,301

388,748,348

 – Weighted average number of ordinary shares – Diluted 

337,824,547

375,154,378

339,033,301

388,748,348

Unaudited Reconciliation of GAAP and Non-GAAP Results

We use adjusted EBITDA in evaluating our operating results and for financial and operational decision-making purposes. Adjusted EBITDA is defined as net loss excluding interest income, interest expense, income tax expense, depreciation of property and equipment, amortization of intangible assets, and share-based compensation expenses.

Adjusted EBITDA should not be considered in isolation or construed as alternatives to net loss or any other measures of performance or as indicators of our operating performance. Investors are encouraged to compare our historical adjusted EBITDA to the most directly comparable GAAP measure, net loss. Adjusted EBITDA presented here may not be comparable to similarly titled measures presented by other companies. Other companies may calculate similarly titled measures differently, limiting their usefulness as comparative measures to our data. We encourage investors and others to review our financial information in its entirety and not rely on a single financial measure.

Nine Months Ended

September 30

Three Months Ended

September 30

2025

2026

2025

2026

Millions, except otherwise noted

US$

US$

US$

US$

Net Loss

(86.6)

(84.1)

(8.4)

(48.6)

Interest income

(3.2)

(3.4)

(1.6)

(0.9)

Interest expense

13.6

26.0

3.5

8.0

Income tax expense

2.0

0.6

(0.1)

(0.4)

Depreciation of property and equipment

6.3

5.6

2.1

1.5

Amortization of intangible assets

6.6

7.2

2.2

2.0

EBITDA

(61.3)

(48.1)

(2.3)

(38.4)

Share-based compensation expenses

7.9

2.2

1.4

0.7

Adjusted EBITDA

(53.4)

(45.9)

(0.9)

(37.7)


View original content:https://www.prnewswire.com/news-releases/ecarx-announces-third-quarter-2026-unaudited-financial-results-302928981.html

SOURCE ECARX Holdings Inc.

Continue Reading

Technology

LONGWELL Releases Axial Fan Selection Set for Heat Rejection in Liquid-Cooled Data Centers

Published

on

By

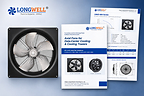
Performance curves, dimensional drawings and electrical data for LWAE3G EC and LWAA AC axial fans — consolidated so OEM engineers can move from thermal duty to a shortlisted model in one pass.

NINGBO, China, Nov. 16, 2026 /PRNewswire/ — LONGWELL (Ningbo Longwell Electric Technology Co., Ltd.) today released a 12-page axial fan selection brochure for manufacturers of dry coolers, air-cooled condensers and outdoor heat-rejection units serving liquid-cooled data centers.

As direct liquid cooling moves heat from processors into liquid circuits, systems using air-side outdoor heat rejection still depend on airflow through heat exchangers. Fan selection therefore needs to account for the resistance of the coil and other equipment components, as well as design ambient conditions and operating requirements.

The brochure covers LWAE3G EC axial fans in 710, 800 and 900 mm sizes, with suction and blowing versions, and LWAA AC axial fans in 500, 630 and 800 mm sizes. EC models support 0–10 VDC or PWM speed control, while AC models provide fixed-speed options. Engineers can review the corresponding curves and mounting drawings against their target airflow, static pressure, power supply and installation space.

Transformer cooling is another part of LONGWELL’s product portfolio. The company already supplies fans and components to transformer-cooling customers. Its LWF cross-flow fan range is designed for forced-air cooling of dry-type transformers, directing airflow along winding cooling passages. This product line provides a further component option for transformer manufacturers and power-equipment integrators serving data center infrastructure.

Related application reviews also cover air-handling equipment, battery energy storage systems (BESS) and power conversion systems (PCS), with a fan selection guide.

OEMs developing new equipment or evaluating a second source can contact LONGWELL with their application, target airflow and static pressure, and power supply requirements. Existing fan nameplates or equipment drawings can support model review, sample discussions and project quotations.

The brochure is available for direct download. Further product information and engineering inquiry access are available on LONGWELL’s data center cooling page.

About LONGWELL

Based in Ningbo, China, LONGWELL designs and manufactures EC, AC and DC fans, blowers and motors for HVACR and industrial equipment. Its portfolio includes axial fans, centrifugal and plug fans, cross-flow fans and fan-motor assemblies for equipment manufacturers and system integrators.

Website: www.longwellfans.com 

View original content to download multimedia:https://www.prnewswire.co.uk/news-releases/longwell-releases-axial-fan-selection-set-for-heat-rejection-in-liquid-cooled-data-centers-302940199.html

Continue Reading

Technology

Certis puts people, robots and AI on the same shift in “Built for What’s Next” campaign

Published

on

By

Certis’s latest brand push draws on close to 70 years of running critical operations to show how robots and AI can take on routine work while officers make the calls that matter

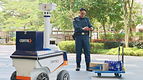
SINGAPORE, Nov. 16, 2026 /PRNewswire/ — For most of its 68-year history, Certis has been known for the officer on patrol. Its latest brand campaign keeps that officer at the centre of the picture, but gives them two new colleagues: a robot that can take on the long patrol rounds, and an AI platform that pulls everything happening on a site into a single view.

“Built for What’s Next”, a three-month campaign that Singapore-headquartered intelligent operations company Certis launched in November 2026, sets out how it is bringing people, robots and AI together as one workforce to keep critical operations running. Premised on a 90-second video, the pitch speaks to the organisations that rely on Certis to keep airports, hospitals, malls and critical infrastructure running: sites that are growing larger and busier, where expectations of safety and service keep rising, and where frontline teams are asked to notice more and respond faster with every shift.

Built from the operator’s seat

Certis has been on that ground since 1958, through day duties and night shifts, quiet hours and critical incidents, and the campaign argues that this experience shapes its approach to technology. Having run the operations itself, the company says it knows where they come under strain and where technology genuinely helps. Its answer is technology designed from the operator’s seat.

“For close to 70 years now, our people have kept critical operations running, whenever the hour and whatever the situation,” said Robin Goh, Senior Vice President and Head, Group Communications & Marketing, Certis. “Built for What’s Next is about carrying that experience into the future.”

Handing the routine to Wallace

For Certis, much of the frontline work its officers carry is repetitive. On a large site, a single patrol round can stretch across car parks, corridors and perimeter fences, and it has to be repeated day and night. The work is essential, but when incidents happen, the officer’s judgement matters most.

That repetitive work is what Certis is now giving to robots such as Wallace, its AI-powered autonomous patrol robot, which is being deployed across several sites in Singapore to patrol and monitor large indoor and outdoor spaces with steady consistency. While Wallace keeps watch on the routine, officers are freed for the moments that need a person: reading a situation, reassuring a member of the public, deciding what happens next.

Robots such as Wallace build on a line of Certis robots that has operated in public spaces since 2019, and join a fleet the company says now numbers more than 60 robots across over 30 customer sites.

Certis is also exploring what comes after. Its humanoid robot, Max, already greets visitors at the company’s Paya Lebar Green headquarters, and a new model is now on trial, learning to take on roles that involve interacting with people rather than only observing spaces. Certis says those lessons will shape how humanoid robots join the workforce in the years ahead.

One view of the whole site

Robots, sensors and officers each play a different role at a site, and each picks up part of the picture. The challenge is bringing those insights together fast enough to act on them.

That is the job of Mozart™, the company’s AI-powered operations orchestration platform. Mozart connects data, systems and workflows into a single view of what is happening on the ground, and helps teams coordinate the response. With AI, analytics and automation working together, Certis says, operations can move from spotting an issue to acting on it with more certainty and efficiency, while human judgement stays in charge of the decisions that matter most. The platform now supports more than 20,000 users across over 30 sites.

The emphasis is deliberate. Certis positions itself not as a robot vendor but as the operator that integrates robots, officers, command centres and building systems, and runs them as one.

One test

The campaign’s message comes down to an expanded workforce, with an optimised division of labour. “Robots take on the repetitive roles, AI helps us act sooner, and our people stay at the core of decision-making and judgement only they can bring,” Goh said.

“Whether it is a robot on patrol, a platform connecting a site or a new AI-powered workflow we developed, we measure every advance by one test: does it make operations better on the ground?” he added. “That is how we help our customers stay ready for what comes next.”

Find out more about “Built for What’s Next” at go.certisgroup.com/builtforwhatsnext

View original content to download multimedia:https://www.prnewswire.com/apac/news-releases/certis-puts-people-robots-and-ai-on-the-same-shift-in-built-for-whats-next-campaign-302940201.html

SOURCE Certis Group

Continue Reading

Technology

Bank Hapoalim Announces 2026 Third Quarter Results

Published

on

By

Net profit in 3Q26 totaled NIS 2,364 million; return on equity 14.0%. Net profit in the first nine months of 2026 totaled NIS 6,976 million; return on equity 14.0%.The annual impact of the special tax on banks is 1.3%–1.4%. Excluding the tax impact, ROE for both 3Q26 and 9M26 was approximately 15.4%.Total income decreased 6.7% vs. the previous quarter, mainly due to less favorable macroeconomic factors and softer capital-market activity. However, income from regular financing activity excluding the CPI impact increased by 1.7% in the nine-month period.Total expenses were down 1.8% QoQ and 3.4% YoY; the cost-income ratio was 32.2% in the quarter and 32.9% in the nine-month period.Credit growth was strong and diversified across all segments of operation, at 3.2% QoQ and 15.4% YoY.Credit quality metrics remained strong: the NPL ratio was 0.49% and the NPL coverage ratio was 292%. The credit-loss ratio decreased to 0.12% in the quarter, reflecting a lower collective provision driven by improved risk parameters and more favorable macroeconomic forecasts.Shareholders’ equity continued to grow organically, up 5.9% over the last twelve months, despite the impact of the increase in U.S. and Israel government yield curves. The CET-1 capital ratio was 11.62%, vs. a minimum internal target of 11.0%.The board of directors declared a total distribution of 50% of net profit, of which a cash dividend of NIS 946 million, with the remainder through the execution of the first tranche of a newly launched share buyback plan (NIS 236 million).

TEL AVIV, Israel, Nov. 16, 2026 /PRNewswire/ — Bank Hapoalim (TASE: POLI) today announced its financial results for the third quarter ended September 30, 2026.

Income statement 

Net profit in the third quarter of 2026 totaled NIS 2,364 million, compared with NIS 2,488 million in the preceding quarter and NIS 2,758 million in the same quarter last year. Net profit in the corresponding quarter included one-time income of NIS 380 million, net, from an insurance reimbursement. Excluding this income, 2025 third-quarter net profit amounted to NIS 2,378 million. 
The decrease in 3Q26 net profit vs. the comparable quarters was mainly driven by a less favorable interest-rate and inflation environment and a decrease in non-regular financing activity, partially offset by continued growth in business activity, higher fees, lower operating expenses, and lower credit-loss provisions.Income from regular financing activity in 3Q26 (NIS 4,819 million vs. NIS 5,109 million in 2Q26) was negatively impacted by lower interest rates (3.45% vs. 3.91%, on average) and CPI (1.0% vs. 1.3% known CPI), and lower income from regular non-interest financing activity, due to lower volatility and trading volumes in capital markets.The financial margin from regular activity was 2.55% in the third quarter, vs. 2.70% in the preceding quarter, reflecting lower interest rates and CPI, as well as lower regular capital-market activity. Income from non-regular financing activity totaled NIS 28 million in the third quarter, vs. NIS 325 million in the preceding quarter. The decrease was driven by substantially lower income from equity investments, amid softer equity markets, as well as realized losses on AFS bonds.Fee income totaled NIS 1,277 million in the third quarter, compared with NIS 1,145 million in the previous quarter and NIS 1,117 million in the same quarter last year. Third-quarter fees benefited from financing-related fee income recognized following a reimbursement from insurers in respect of Sale Law guarantee insurance. Credit-handling fees also grew, reflecting the recognition of syndication fees from infrastructure transactions, as the bank led the financing of one of Israel’s largest energy infrastructure projects in recent years during the quarter.
Fees for the nine-month period grew 6.5% to NIS 3.5 billion. Excluding one-time income recorded in both periods, growth was broadly similar and distributed across all fee types.Operating and other expenses totaled NIS 1,982 million in the third quarter, compared with NIS 2,019 million in the previous quarter and NIS 2,052 million in the same quarter last year, a decrease of 1.8% QoQ and 3.4% YoY. On the longer view of the nine-month period, operating and other expenses declined by 2.2%, due to a decline in both other expenses and salary expenses. Salary expenses declined by 3.1% due to lower bonus provisions, while base salary expenses remained stable, supported by efficiency measures and employee retirements.The cost-income ratio remained low at 32.2% in the third quarter of 2026 and was 32.9% for the first nine months of 2026.The provision for credit losses in the third quarter of 2026 totaled NIS 167 million (a credit-loss ratio of 0.12%). The low provision for credit losses is due to a decrease in the collective provision, which reflects improved risk parameters and more favorable macroeconomic forecasts. The individual provision remained low at NIS 31 million, with no exceptional recoveries during the quarter.Profit before tax for the nine-month period remained stable at NIS 11.8 billion, and even grew by 3.7% excluding the aforementioned one-time income in the corresponding period, despite a decline of approximately 70 basis points in interest rates and lower CPI (2.1% in the first nine months of 2026, vs. 3.0% in the corresponding period last year). This reflects continued growth in the bank’s business activity, lower credit loss provisions, and a 2.2% reduction in operating expenses. Profit after tax for the nine-month period was negatively impacted by the special tax imposed on Israeli banks. The special tax on the banking industry increased from NIS 1.3 billion in 2025 to approximately NIS 3.0 billion in 2026. For Bank Hapoalim, the special tax is approximately NIS 950 million in 2026 and approximately NIS 40 million in 2027.

Balance sheet

Net credit to the public in the third quarter of 2026 totaled NIS 553.2 billion, compared with NIS 536.2 billion in the preceding quarter, an increase of 3.2%. Compared with the corresponding quarter, net credit to the public increased by 15.4%. The growth in the credit portfolio was broad-based across all segments of operation and diversified across several economic sectors. Corporate credit increased by 3.4% in comparison to the preceding quarter, and by 27.5% in comparison to the corresponding quarter; commercial credit increased by 5.3% QoQ and 16.7% YoY. In the retail banking division, the housing loan portfolio grew by 1.8% QoQ and 6.3% YoY, small business credit increased by 2.0% and 8.9%, and consumer credit grew by 1.8% and 7.0%, respectively.Total deposits reached NIS 637.2 billion, an increase of 3.1% vs. the last quarter and 7.9% vs. the same quarter last year. Retail deposits stayed fairly flat vs. comparable periods, at NIS 318.1 billion, constituting 50% of total deposits.LCR and NSFR are at 126% and 115% respectively, vs. the minimum regulatory requirement of 100%. The allowance for credit losses stood at NIS 9.1 billion as at September 30, 2026, of which NIS 8.7 billion attributed to the collective allowance. The total allowance constitutes 1.61% of total credit.Credit quality indicators remained strong; the NPL ratio stood at 0.49% and the NPL coverage ratio (balance sheet allowance for credit losses/NPL) was 292%.Shareholders’ equity grew by 5.9% in the last year, to NIS 67.5 billion, supported by our strong organic capital generation, partially offset by a decrease in the balance of the capital reserve in respect of the AFS bond portfolio. The CET-1 capital ratio stood at 11.62%, vs. the 10.24% minimum regulatory requirement and 11.0% minimum internal target, as at September 30, 2026. The total capital ratio as at September 30, 2026, stood at 14.09%, vs. a 13.5% minimum regulatory requirement.Dividend distribution and share buyback: The board of directors declared a distribution at an overall rate of 50% of net profit, of which a cash dividend of NIS 946 million and the rest through the exercise of the first tranche of a new share buyback plan (NIS 236 million). The dividend will be paid on December 1, 2026.

Financial targets

Financial targets for 2026–2027, based on baseline assumptions as of March 5, 2026, and following the completion on March 30, 2026, of the legislation regarding a special bank tax in 2026 and 2027:

Net profit in the range of NIS 8.5–9.5 billion for 2026 and NIS 9.5–10.5 billion for 2027;Return on equity in the range of 13%–14% for 2026 and 14%–15% for 2027;Growth of the credit portfolio at an average annual rate of 8%–9%;Profit distribution at a rate of 50%–60% of net profit, through cash dividends or buybacks, subject to the guidelines of the Bank of Israel.

Recent developments

Annual general meeting of shareholders
On October 29, 2026, the bank held its annual general meeting of shareholders for 2026, at which the following resolutions were passed: (1) the Financial Statements and the Report of the Board of Directors and Board of Management of the Bank for 2025 were discussed; (2) the reappointment of Somekh Chaikin (KPMG), CPA, and Ziv Haft (BDO), CPA, as joint auditors of the bank until the end of the next annual general meeting was approved; (3) the appointment of Michal Halperin and Tamar Schechter as external directors pursuant to the Companies Law (for a second and first term of office, respectively) was approved; (4) the appointment of Israel Trau as an other (non-external) director (for a third term of office) was approved; (5) the remuneration policy for officers of the bank was approved; (6) updated terms of service for the bank’s directors, in connection with the grant of fixed equity compensation, were approved; and (7) updated terms of service and employment for the Bank’s CEO, Yadin Antebi, were approved.
As part of the approved remuneration resolutions (items 5 and 7), and as part of a bank-wide initiative to discontinue early retirement arrangements, the option for senior executives to convert their accrued retirement rights into bank shares was also approved.
The bank estimates that the conversion of the accrued retirement rights will result in a one-time expense of approximately NIS 8 million. At the same time, discontinuing the accrual of early retirement and enhanced severance rights and converting them into the bank’s shares is expected to reduce future expenses (service cost and interest) by approximately NIS 10 million per year.

Bank shares buyback plan
On November 19, 2025, the board of directors of the bank (after receiving the approval of the Banking Supervision Department) approved a plan for a buyback of shares of the bank, at a volume not to exceed NIS 1 billion, until November 5, 2026, or until the full amount of the plan was acquired, whichever was earlier. Within this plan, which was completed on September 17, 2026, the bank purchased a cumulative 13,128,375 ordinary shares of the bank, constituting approximately 0.98% of the issued and paid-up capital of the bank, at a total cost of approximately NIS 985 million.
On November 15, 2026, the board of directors of the bank approved a new plan for a buyback of shares of the bank at a volume not to exceed NIS 1 billion, from November 17, 2026, until November 1, 2027, or until the full amount of the plan is acquired, whichever is earlier.

Conference-call/webinar information

Bank Hapoalim will host a conference call/webinar today to discuss the results. The call will take place at 5:00 p.m. Israel time / 3:00 p.m. UK time / 10:00 a.m. Eastern time. Participation in the call/webinar is available via the following link: BankHapoalimQ3.2026 (pre-registration is also available via the link). No password or access code is required. The review will be conducted in listen-only mode, followed by a Q&A session.

The webinar will be accompanied by a presentation, which will be published on the day of the financial statements’ release on the distribution website of the Israel Securities Authority (MAGNA), the Tel Aviv Stock Exchange website, and the bank’s Investor Relations page (Financial Information section) at: https://www.bankhapoalim.com.

A recording of the conference call/webinar will be available one business day following the event, on the bank’s Investor Relations page at the above-mentioned address.

Please note: The conference call is not a substitute for the perusal of the immediate reports and the financial statements of the bank, including all forward-looking information included therein, in accordance with Section 32A of the Israeli Securities Law, 1968.

Contact info:

Tamar Koblenz
Head of Investor Relations
Investor.Relations@poalim.co.il

Dr. Sharona Mazalian-Levi
Spokesperson
sml@poalim.co.il

This press release contains forward-looking statements, as defined in the Israeli Securities Law, relating to future events or future performance.

This press release is provided for convenience purposes only and does not constitute a substitute for a full review of the Bank’s latest periodic/quarterly reports, as filed with the Israel Securities Authority.


View original content to download multimedia:https://www.prnewswire.com/news-releases/bank-hapoalim-announces-2026-third-quarter-results-302940204.html

SOURCE Bank Hapoalim

Continue Reading

Trending