Alkaline electrolyzers lead by technology, PEM is set to grow fastest, and Asia-Pacific dominates deployment and manufacturing as low-emissions hydrogen scales up
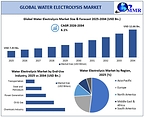
PUNE, India, Oct. 1, 2026 /PRNewswire/ — The global Water Electrolysis Market was valued at USD 7.43 billion in 2025 and is projected to reach USD 12.66 billion by 2034, growing at a CAGR of 6.1% during 2026–2034, according to a new report by MMR. The study points to a market moving from an emerging clean-hydrogen technology toward a broader industrial equipment market.
Global Water Electrolysis Market
The Global Water Electrolysis Market Report 2025 provides a detailed analysis of market trends, low-emissions hydrogen demand, electrolyzer technologies, industrial feedstock applications, renewable energy integration, competitive strategies, and forecasts through 2034. Water electrolysis is a hydrogen-production process in which electricity is used to split water into hydrogen and oxygen through an electrolyzer. It is particularly important for producing low-emissions hydrogen when the power comes from renewable or nuclear sources. Key technologies include Alkaline Electrolysis, Proton Exchange Membrane (PEM) Electrolysis, Solid Oxide Electrolysis, and Anion Exchange Membrane (AEM) Electrolyzers. Demand is increasing across refining, ammonia, methanol, steel, power generation, energy storage, sustainable fuels, and transportation as industries look to cut emissions from hydrogen production.
The Global Water Electrolysis Market was valued at USD 7.43 billion in 2025 and is projected to reach USD 12.66 billion by 2034, growing at a CAGR of 6.1% during 2026-2034. Growth is supported by rising hydrogen requirements, government support for clean hydrogen, falling equipment costs, and a larger pipeline of electrolysis projects. Global installed electrolysis capacity more than doubled in 2025 to above 4 GW, with more than 2.5 GW under construction. Alkaline electrolysis remained the largest technology segment because of its commercial maturity, lower capital requirements, and suitability for large-scale production, while PEM is expected to grow faster on its compact design and ability to work with variable solar and wind power. Industrial Feedstock was the leading application segment, and Asia-Pacific led the market, with China accounting for nearly three-quarters of new electrolysis installations in 2025.
A major shift in the Water Electrolysis Market is the move from small demonstration projects to larger commercial installations, along with a push for lower costs, higher efficiency, and regional manufacturing. Nel ASA entered a framework agreement with Hydrasun in September 2026 to build European assembly and integration capabilities for its modular PEM electrolyzers. thyssenkrupp nucera and BHEL signed a collaboration in July 2026 to localize alkaline electrolyzer module fabrication in India. BASF commissioned Germany’s largest green hydrogen production facility at Ludwigshafen in May 2026 using Siemens Energy PEM technology. ITM Power also received approval for a £46.5 million UK government grant in July 2026 to support its Chronos electrolyzer manufacturing capability. These developments reflect the industry’s broader move toward scalable, cost-efficient electrolysis solutions through 2034.
Get Full PDF Sample Copy of Report: (Including Full TOC, List of Tables & Figures, Chart) @ https://www.maximizemarketresearch.com/request-sample/221915/
The Global Water Electrolysis Market is entering a more commercial phase as low-emissions hydrogen demand, renewable energy integration, and industrial decarbonization drive investment in electrolyzer projects. Manufacturers are focusing on lower costs, higher efficiency, better durability, and larger system capacities. At the same time, regional manufacturing, PEM and alkaline technology advances, and large-scale hydrogen projects are reshaping the competitive landscape. Maximize Market Research highlights the key trends expected to shape the market through 2034.
Scope of the Water Electrolysis Market Report
Metric
Value
Market size, 2025
USD 7.43 Billion
Market size, 2034 (forecast)
USD 12.66 Billion
CAGR, 2026–2034
6.1 %
Base year / Historical period
2025 / 2020–2025
Forecast period
2026–2034
Largest technology segment
Alkaline electrolysis
Fastest-growing technology
PEM electrolysis
Largest application segment
Industrial feedstock
Leading region
Asia-Pacific
Key players profiled
40 companies, including Nel ASA, Siemens Energy AG, Cummins Inc., ITM Power plc, Plug Power Inc., thyssenkrupp nucera, John Cockerill, Sunfire GmbH, Bloom Energy, Topsoe A/S, Asahi Kasei Corporation, LONGi Hydrogen Technology, Sungrow Hydrogen, Electric Hydrogen Co., Air Liquide S.A. and others
Rising Demand for Low-Emissions Hydrogen Drives the Water Electrolysis Market
Water electrolysis uses electricity to split water into hydrogen and oxygen through an electrolyzer. It is a key route to low-emissions hydrogen when powered by renewable or nuclear electricity. Global hydrogen demand surpassed 100 million tonnes in 2025, yet low-emissions hydrogen production reached only almost 1 million tonnes, roughly 1% of the total. This leaves substantial room for electrolysis-based supply to expand, and production is expected to record strong growth in 2026.
Demand is established in refining, ammonia and methanol, and is building in green steel, sustainable fuels, power generation, energy storage and heavy transport. Buyers include hydrogen producers, refineries, chemical and fertilizer companies, steel manufacturers, utilities, renewable-energy developers and industrial gas companies.
Key Highlights & Insights – Water Electrolysis Market
Installed capacity more than doubled: Global installed electrolysis capacity rose above 4 GW in 2025, with more than 2.5 GW under construction and targeting operation in 2026.Investment nearly doubled: Capital spending on low-emissions hydrogen projects reached nearly USD 7 billion in 2025, almost double the 2024 level, with electrolysis-based projects attracting the larger share.Manufacturing capacity is far ahead of demand: Global electrolyzer manufacturing capacity reached nearly 38 GW per year in 2024, up 40% year on year, while actual production was only around 4 GW, implying utilization of roughly 10%.Large project pipeline: Around 26 GW of electrolysis capacity had reached final investment decision or was under construction with planned operation by 2030.Pipeline at risk: More than 100 GW of announced capacity could miss the 2030 operating target if investment decisions are not secured before the end of 2027.Production is expanding: Low-emissions hydrogen production reached almost 1 million tonnes in 2025.
Get Insightful Data on Regions, Market Segments, Customer Landscape, and Top Companies (Charts, Tables, Figures and More) https://www.maximizemarketresearch.com/request-sample/221915/
Market Segmentation Insights
By Technology Type: Alkaline electrolysis is the largest segment because of its commercial maturity, relatively lower capital requirements, proven reliability and suitability for steady, large-scale production. PEM electrolysis is expected to grow faster, driven by its compact design, rapid response and compatibility with variable solar and wind power. Solid oxide electrolysis targets higher efficiency where high-temperature heat is available, while anion exchange membrane (AEM) electrolyzers aim to combine alkaline and PEM advantages with reduced dependence on expensive catalyst materials.By Application: Industrial feedstock, including ammonia, methanol and petroleum refining, is the largest application segment. Power generation and energy storage, and power-to-gas, are gaining importance, while transportation, including fuel-cell vehicles and hydrogen refueling, is highlighted as an application with strong growth potential.By Capacity and End Use: The report segments the Water Electrolysis Market by capacity, covering systems below 500 kW, 500 kW–2 MW, and above 2 MW, reflecting differences in project scale and hydrogen production requirements. It also analyzes end-use industries, including chemicals, power generation, oil & gas, steel and petroleum, and transportation, highlighting how electrolyzers are being adopted for hydrogen production, industrial feedstock, energy storage, refining, and low-carbon fuel applications.By Region : The report segments the Water Electrolysis Market by region covering North America; Europe; Asia Pacific; Middle East & Africa; South America
Regional Analysis:
Asia-Pacific Leads the Global Water Electrolysis Market as China Accounts for Nearly Three-Quarters of New Installations in 2025
Asia-Pacific leads the market on strong manufacturing, large industrial hydrogen demand and government-backed programs. China accounted for nearly three-quarters of new electrolysis installations in 2025 and holds close to 60% of global electrolyzer manufacturing capacity. India is emerging as an important market, with a focus on green hydrogen for refining and fertilizers. Japan and South Korea are developing hydrogen for power generation and fuels, Australia is advancing large renewable-hydrogen projects, and Indonesia, Malaysia and Vietnam are targeting ammonia, methanol and steel.
Europe is driven by decarbonization policy, including the EU’s target of 40 GW of domestic electrolyzer capacity by 2030. More than 2 GW of European electrolysis projects reached final investment decision between September 2023 and August 2024. Germany, Spain, the Netherlands and France are leading project development across refining, chemicals, steel and renewable integration. The IEA expects much of the near-term additional capacity to come from Europe.
North America is advancing through hydrogen hubs, industrial decarbonization programs and financial incentives, with demand potential from refining, chemicals, steel and transportation. Canada is developing clean hydrogen using its low-carbon electricity.
Middle East & Africa is focused on very large export-oriented projects. Saudi Arabia’s NEOM Green Hydrogen Project targets approximately 2.2 GW of electrolyzer capacity by 2027, and Oman, the UAE and Egypt are also developing projects.
South America, led by Chile and Brazil, offers long-term potential based on strong renewable resources, though many projects remain at the development stage.
Challenges to Watch
High electrolyzer costs, electricity requirements, project delays, financing constraints and uncertain hydrogen offtake are slowing commercial deployment. New final investment decisions for low-emissions hydrogen production fell below 0.8 million tonnes per year in 2025, from around 1 million tonnes per year in each of the previous two years. Changing incentives, permitting requirements and infrastructure gaps can extend development timelines further, and competition from lower-cost fossil-based hydrogen continues to affect project development.
Opportunities Across the Value Chain
Large-scale hydrogen projects are creating opportunities for electrolyzer manufacturers, component suppliers, engineering companies, renewable-energy developers and hydrogen infrastructure providers. Integrating electrolyzers with solar and wind projects lets dedicated or surplus renewable power be converted to hydrogen. Industries such as steel, chemicals, refining and sustainable fuels are exploring hydrogen for hard-to-electrify processes. This supports demand for higher-efficiency electrolyzers, improved durability, lower manufacturing costs and integrated hydrogen production solutions.
Competitive Landscape of the Water Electrolysis Market
The Water Electrolysis Market is witnessing rising competition as companies expand electrolyzer production, improve system efficiency and take part in large-scale hydrogen projects. Key players include Nel ASA, thyssenkrupp nucera, ITM Power plc, Siemens Energy AG, Plug Power Inc., Cummins Inc., John Cockerill, Asahi Kasei Corporation, Sunfire GmbH, Bloom Energy, Enapter AG, McPhy Energy, Ohmium International and Topsoe A/S. Alkaline and PEM technologies dominate the competitive field, while solid oxide and AEM specialists are differentiating through high-temperature efficiency and modular system designs. Competition is shaped by technology capability, production capacity, project scale, cost reduction and regional presence, with companies offering complete, scalable and cost-efficient electrolysis solutions best placed to win large industrial and energy-sector contracts.
Immediate Delivery Available | Buy this Research Report (Insights, Charts, Tables, Figures and More) https://www.maximizemarketresearch.com/checkout/221915/
Water Electrolysis Market, Key Players
Nel ASASiemens Energy AGCummins Inc.ITM Power plcMcPhy Energy S.A.Plug Power Inc.Toshiba Energy Systems & Solutions CorporationEnapter AGGiner ELX Inc.Areva H2GenGreen Hydrogen Systems A/SKobelco Eco-Solutions Co., Ltd.Next Hydrogen CorporationERGOSUPCeres Power Holdings plcthyssenkrupp nucera AG & Co. KGaAJohn CockerillSunfire GmbHBloom Energy CorporationTopsoe A/SHydrogenPro ASAOhmium International, Inc.Asahi Kasei CorporationPERIC Hydrogen Technologies Co., Ltd.LONGi Hydrogen Technology Co., Ltd.Sungrow HydrogenHygreen EnergyH-TEC SYSTEMS GmbHElectric Hydrogen Co.H2B2 Electrolysis Technologies S.L.OxEon Energy, LLCErre Due S.p.A.Hysata Pty LtdHydrogen Optimized Inc.Elogen SASH2e Power Systems Pvt. Ltd.Shandong AUYAN New Energy Technology Co., Ltd.Beijing SinoHy Energy Co., Ltd.Horizon Fuel Cell Technologies Pte. Ltd.Air Liquide S.A.
Access Full Summary: https://www.maximizemarketresearch.com/market-report/water-electrolysis-market/221915/
FAQs:
1. What are the growth drivers for the Water Electrolysis market?
Ans: The primary growth drivers for the Water Electrolysis market include Increasing focus on renewable energy sources for hydrogen production. Government initiatives and policies promoting green hydrogen. Additionally, Growing demand for clean fuels in various industries like transportation and power generation.
2. What is the major restraint for the Water Electrolysis market growth?
Ans. One significant restraint for the Water Electrolysis market growth is the high initial capital investment required for establishing electrolysis facilities, hindering widespread adoption. Additionally, limitations in grid infrastructure for accommodating renewable energy sources can pose challenges in scaling up electrolysis operations. Regulatory complexities and the need for supportive policies also impede rapid market expansion.
3. Which region is expected to lead the global Water Electrolysis market during the forecast period?
Ans. Asia-Pacific is expected to lead the global Water Electrolysis market during the forecast period.
4. What is the projected market size & and growth rate of the Water Electrolysis Market?
Ans. The Water Electrolysis Market size was valued at USD 7.43 Billion in 2025 and the total Water Electrolysis revenue is expected to grow at a CAGR of 6.1% from 2026 to 2034, reaching USD 12.66 Billion by 2034.
5. What segments are covered in the Water Electrolysis Market report?
Ans. The segments covered in the Water Electrolysis market report are Technology Type, end user, and Region.
Analyst Perspective
The Global Water Electrolysis Market is moving from an emerging clean-hydrogen technology toward a broader industrial equipment market, with growth increasingly shaped by project economics. Installed capacity more than doubled to above 4 GW in 2025, yet manufacturing capacity of nearly 38 GW per year far exceeds actual output, putting pressure on manufacturers to convert announced projects into firm orders. Securing financing and long-term hydrogen offtake will be critical, as new final investment decisions fell below 0.8 million tonnes per year in 2025. Companies offering scalable, cost-efficient solutions with regional manufacturing and renewable power integration are best placed to benefit, with alkaline remaining the largest segment and PEM growing faster through 2034.
Related Reports:
Hydrogen Market by Type, Production Process, Technology, Application and Region– Global Forecast to 2034.
Merchant Hydrogen Market by Application, Type, Storage, and Region – Global Forecast to 2034.
Hydrogen Storage Tank Market by Product, Material Type, Storage Type, Application, End Use, and Region – Global Forecast to 2034.
Industrial Gases Market by Type, End Use Industry, and Region – Global Forecast to 2034.
Hydrogen Detection Market by Product, Technology, Application, Implementation, Detection Range, and Region – Global Forecast to 2034.
Oxygen Market Size by Form, Application, End User and Region– Global Forecast to 2034.
Green Ammonia Market by Technology, by Production Method, by Application,by End User,by Sales Channel,
About Maximize Market Research – Global Water Electrolysis Market
Maximize Market Research is a global market research and business consulting firm providing data-driven insights across the Chemical & Material, hydrogen and clean energy, electrolyzer technologies, renewable energy, industrial gases, power generation, and related sectors. Its Global Water Electrolysis Market research covers Alkaline Electrolysis, Proton Exchange Membrane (PEM) Electrolysis, Solid Oxide Electrolysis, Anion Exchange Membrane (AEM) Electrolyzers, industrial feedstock, power generation and energy storage, transportation, power-to-gas, low-emissions hydrogen production, electrolyzer manufacturing capacity, regional demand, competitive strategies, large-scale hydrogen projects, and emerging electrolysis technologies, helping businesses understand market changes and identify new growth opportunities through 2034.
Global Water and Wastewater Treatment Chemicals Market Size, by Region (2025–2032) – MMR Statistics
MMR Statistics is a part of Maximize Market Research, developed to provide quick access to market size, industry data, forecasts, trends, and statistical insights across a wide range of sectors. It presents research data in multiple formats, making it easier for businesses, analysts, and decision-makers to use market intelligence for presentations, strategy, benchmarking, and business planning.
U.S. Green Mining Equipment Market, 2025–2032: Mine Electrification, Autonomous Operations, and Critical Mineral Expansion Accelerating Sustainable Mining Transformation – Stellar Market Research
Stellar Market Research is a strategic partner of Maximize Market Research, providing global and region-wise market research reports across multiple industries. Its research focuses on market trends, competitive developments, regional opportunities, industry dynamics, and growth outlooks, complementing Maximize Market Research with broader market coverage and region-specific business intelligence.
Contact:
Lumawant Godage
MAXIMIZE MARKET RESEARCH PVT. LTD.
+91 96073 65656
Email: sales@maximizemarketresearch.com
Visit Our Web Site: https://www.maximizemarketresearch.com/
View original content to download multimedia:https://www.prnewswire.com/news-releases/water-electrolysis-market-to-reach-usd-12-66-billion-by-2034–growing-at-a-6-1-cagr-report-by-maximize-market-research-302895894.html
SOURCE Maximize Market Research Pvt. Ltd.





 Coin Market5 days ago
 Coin Market5 days ago
 Technology4 days ago
 Technology2 days ago
 Coin Market4 days ago
 Technology4 days ago
 Technology4 days ago
 Technology4 days ago