
Technology
Jack Henry & Associates, Inc. Reports First Quarter Fiscal 2027 Results

Published
2 hours agoon
By
First quarter summary:
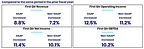
GAAP revenue increased 8.8% and GAAP operating income increased 12.5% for the fiscal three months ended September 30, 2026, compared to the prior fiscal year quarter.Non-GAAP adjusted revenue increased 7.2% and non-GAAP adjusted operating income increased 11.2% for the fiscal three months ended September 30, 2026, compared to the prior fiscal year quarter.1GAAP EPS was $2.28 per diluted share for the fiscal three months ended September 30, 2026, compared to $1.97 per diluted share in the prior fiscal year quarter, representing growth of 15.6%.Cash and cash equivalents were $25.4 million at September 30, 2026, and $36.2 million at September 30, 2025.Debt outstanding for credit facilities was $85 million at September 30, 2026, and $20 million at September 30, 2025.Stock repurchases for the fiscal three months ended September 30, 2026, were $71 million at an average price of $153.47 per share.
Full year fiscal 2027 guidance (Dollars in millions, other than per share amounts):3
Current
GAAP
Low
High
Revenue
$2,698
$2,718
Operating margin4
24.7 %
24.9 %
EPS
$7.47
$7.51
Non-GAAP5
Adjusted revenue
$2,667
$2,687
Adjusted operating margin
24.1 %
24.3 %
MONETT, Mo., Nov. 3, 2026 /PRNewswire/ — Jack Henry & Associates, Inc. (Nasdaq: JKHY), a leading financial technology provider, today announced results for fiscal first quarter ended September 30, 2026.
According to Greg Adelson, President and CEO, “We continued our positive momentum in the first quarter of fiscal 2027, delivering record financial results that exceeded the outlook we provided in August. The demand environment remains very strong, as reflected in our outstanding sales performance and robust pipeline. We are extremely pleased with the start of our fiscal year and based on improved revenue drivers, we again exceeded consensus expectations. We are confident in our ability to continue delivering consistent, long-term results through an unwavering commitment to culture, service, innovation, strategy, and execution.”
1 See tables below on page 4 reconciling non-GAAP financial measures to GAAP.
2See table below on page 13 reconciling net income to non-GAAP EBITDA.
3 The full fiscal year guidance assumes no acquisitions or dispositions will be made during fiscal year 2027.
4Operating margin is calculated by dividing operating income by revenue.
5See tables below on page 7 reconciling fiscal year 2027 GAAP to non-GAAP guidance.
Operating Results
Revenue, operating expenses, operating income, and net income for the fiscal three months ended September 30, 2026, compared to the fiscal three months ended September 30, 2025, were as follows:
Revenue
(Unaudited, dollars in thousands)
Three Months Ended
September 30,
% Change
2026
2025
Revenue
Services and Support
$ 404,961
$ 376,851
7.5 %
Percentage of Total Revenue
57.7 %
58.5 %
Processing
296,586
267,887
10.7 %
Percentage of Total Revenue
42.3 %
41.5 %
REVENUE
$ 701,547
$ 644,738
8.8 %
Services and support revenue increased for the fiscal three months ended September 30, 2026, compared to the fiscal three months ended September 30, 2025, primarily driven by growth in hosting revenue of 11.7% as new and existing clients continue to migrate to our private cloud and processing volumes expand, an increase in deconversion revenue of $9,292, as well as an increase in software usage revenue of 9.9%, partially offset by the decrease in revenue related to the timing of our Connect conference, which was held in the first quarter of fiscal 2026 and the second quarter of 2027. Processing revenue increased for the fiscal three months ended September 30, 2026, compared to the fiscal three months ended September 30, 2025, mainly driven by growth in card revenue of 9.4% from monthly service and risk management fees, improvement in digital and transaction revenue of 13.3% from a higher number of active users on our digital platform and from the ramping up of additional products, as well as a rise in faster payments revenue of 43.8% from expanding transactional volumes.For the fiscal three months ended September 30, 2026, compared to the fiscal three months ended September 30, 2025, core segment revenue increased 7.1%, payments segment revenue increased 9.2%, complementary segment revenue increased 10.4%, and corporate services segment revenue increased 6.2%. For the fiscal three months ended September 30, 2026, compared to the fiscal three months ended September 30, 2025, core segment non-GAAP adjusted revenue increased 4.9%, payments segment non-GAAP adjusted revenue increased 8.3%, complementary segment non-GAAP adjusted revenue increased 8.4%, and corporate services non-GAAP adjusted segment revenue increased 5.2%. Total non-GAAP adjusted revenue increased 7.2% for the same comparative periods (see revenue lines of segment break-out tables on pages 5 and 6 below for a reconciliation of GAAP segment revenue to non-GAAP adjusted segment revenue).
Operating Expenses and Operating Income
(Unaudited, dollars in thousands)
Three Months Ended
September 30,
% Change
2026
2025
Cost of Revenue
$ 376,046
$ 348,566
7.9 %
Percentage of Total Revenue6
53.6 %
54.1 %
Research and Development
45,781
39,278
16.6 %
Percentage of Total Revenue6
6.5 %
6.1 %
Selling, General, and Administrative
72,649
72,829
(0.2) %
Percentage of Total Revenue6
10.4 %
11.3 %
OPERATING EXPENSES
494,476
460,673
7.3 %
OPERATING INCOME
$ 207,071
$ 184,065
12.5 %
Operating Margin6
29.5 %
28.5 %
Cost of revenue increased for the fiscal three months ended September 30, 2026, compared to the fiscal three months ended September 30, 2025, primarily due to higher personnel costs, including compensation and benefit costs, partly related to trailing twelve month headcount growth, higher direct costs generally consistent with increases in related lines of revenue, higher cloud consumption costs, including artificial intelligence and security costs, increased licenses and fees, including infrastructure costs, as well as higher amortization of intangibles, partially offset by the increase in labor cost deferral.Research and development expense increased for the fiscal three months ended September 30, 2026, compared to the fiscal three months ended September 30, 2025, primarily due to higher personnel costs (net of capitalization), including compensation and benefit costs, partly related to trailing twelve month headcount growth.Selling, general, and administrative expense decreased for the fiscal three months ended September 30, 2026, compared to the fiscal three months ended September 30, 2025, mainly due to lower expenses related to the timing of our Connect conference.
Net Income
(Unaudited, dollars in thousands,
except per share data)
Three Months Ended
September 30,
% Change
2026
2025
Income Before Income Taxes
$ 210,635
$ 190,318
10.7 %
Provision for Income Taxes
50,223
46,332
8.4 %
NET INCOME
$ 160,412
$ 143,986
11.4 %
Diluted earnings per share
$ 2.28
$ 1.97
15.6 %
Effective tax rates for the fiscal three months ended September 30, 2026, and September 30, 2025, were 23.8% and 24.3%, respectively.
According to Mimi Carsley, CFO and Treasurer, “During the first quarter of the fiscal year, we delivered solid 7.2% non-GAAP revenue growth aided by key areas such as Cloud, Card, and Digital, with continued Faster Payments momentum. Revenue growth and leverage in our business model contributed to non-GAAP operating income margin of 28.2% and an outstanding ROIC of 23.2%”
6Operating margin is calculated by dividing operating income by revenue. Operating margin plus operating expense components as a percentage of total revenue may not equal 100% due to rounding.
Impact of Non-GAAP Adjustments
The tables below show our revenue, operating income, and net income for the fiscal three months ended September 30, 2026, compared to the fiscal three months ended September 30, 2025, excluding the impacts of deconversions and the effects of the prior fiscal year acquisition of Victor Technologies in the current fiscal quarter ended September 30, 2026, and the impacts of deconversions and the gain on assets, net, in the prior fiscal quarter ended September 30, 2025.
(Unaudited, dollars in thousands)
Three Months Ended September 30,
%
Change
2026
2025
GAAP Revenue*
$ 701,547
$ 644,738
8.8 %
Adjustments:
Deconversion revenue
(17,918)
(8,626)
Revenue from the acquisition
(1,451)
—
NON-GAAP ADJUSTED REVENUE*
$ 682,178
$ 636,112
7.2 %
GAAP Operating Income
$ 207,071
$ 184,065
12.5 %
Adjustments:
Operating income from deconversions
(15,199)
(7,101)
Gain on assets, net
—
(3,796)
Operating loss from the acquisition
759
—
NON-GAAP ADJUSTED OPERATING INCOME
$ 192,631
$ 173,168
11.2 %
Non-GAAP Adjusted Operating Margin**
28.2 %
27.2 %
GAAP Net Income
$ 160,412
$ 143,986
11.4 %
Adjustments:***
Net income from deconversions
(15,199)
(7,101)
Gain on assets, net
—
(3,796)
Net loss from the acquisition
759
—
Tax impact of adjustments
3,466
2,615
NON-GAAP ADJUSTED NET INCOME
$ 149,438
$ 135,704
10.1 %
*GAAP revenue is comprised of services and support and processing revenues (see page 2). Services and support revenue less deconversion revenue for the fiscal three months ended September 30, 2026, and 2025, which was $17,918 for the current fiscal year quarter and $8,626 for the prior fiscal year quarter, results in non-GAAP adjusted services and support revenue growth of 5.1% compared to the prior fiscal year quarter. Processing revenue less revenue excluding the effects of a prior year acquisition for the fiscal three months ended September 30, 2026, of $1,451, results in non-GAAP adjusted processing revenue growth of 10.2% compared to the prior fiscal year quarter.
**Non-GAAP adjusted operating margin is calculated by dividing non-GAAP adjusted operating income by non-GAAP adjusted revenue.
***The non-GAAP net income adjustments below are first listed before tax and then the tax impact is presented as a combined tax impact of all adjustments. The tax impact of adjustments is calculated using a tax rate of 24% for the fiscal three months ended September 30, 2026, and 2025. The tax rate for non-GAAP adjustment items takes a broad look at the Company’s recurring tax adjustments and applies them to non-GAAP revenue that does not have its own specific tax impacts.
The tables below show the segment break-out of revenue and cost of revenue for each period presented, as adjusted for the items above, and include a reconciliation to non-GAAP adjusted operating income presented above.
Three Months Ended September 30, 2026
(Unaudited, dollars in thousands)
Core
Payments
Complementary
Corporate
Services
Total
GAAP REVENUE
$ 203,411
$ 252,111
$ 220,176
$ 25,849
$ 701,547
Non-GAAP adjustments*
(7,411)
(5,764)
(5,905)
(289)
(19,369)
NON-GAAP ADJUSTED REVENUE
196,000
246,347
214,271
25,560
682,178
GAAP COST OF REVENUE
76,204
125,318
74,776
99,748
376,046
Non-GAAP adjustments*
(888)
(1,591)
(446)
(114)
(3,039)
NON-GAAP ADJUSTED COST OF REVENUE
75,316
123,727
74,330
99,634
373,007
GAAP SEGMENT INCOME
$ 127,207
$ 126,793
$ 145,400
$ (73,899)
Segment Income Margin**
62.5 %
50.3 %
66.0 %
(285.9) %
NON-GAAP ADJUSTED SEGMENT INCOME
$ 120,684
$ 122,620
$ 139,941
$ (74,074)
Non-GAAP Adjusted Segment Income Margin**
61.6 %
49.8 %
65.3 %
(289.8) %
Research and Development
45,781
Selling, General, and Administrative
72,649
Non-GAAP adjustments unassigned to a segment***
(1,890)
NON-GAAP TOTAL ADJUSTED OPERATING EXPENSES
489,547
NON-GAAP ADJUSTED OPERATING INCOME
$ 192,631
*Revenue non-GAAP adjustments for the Payments segment were ($1,451) of revenue related to the acquired company and ($4,313) of deconversion revenue. Revenue non-GAAP adjustments for the remainder of the segments were deconversion revenue. Cost of revenue non-GAAP adjustments for the Payments segment were ($1,427) of costs related to the acquired company and ($164) of deconversion costs. Cost of revenue non-GAAP adjustments for the Corporate Services segment were ($105) of costs related to the acquired company and ($9) of deconversion costs. Cost of revenue non-GAAP adjustments for the remainder of the segments were deconversion costs.
**Segment income margin is calculated by dividing segment income by revenue for each segment. Non-GAAP adjusted segment income margin is calculated by dividing non-GAAP adjusted segment income by non-GAAP adjusted revenue for each segment.
***Non-GAAP adjustments unassigned to a segment were deconversion costs of $1,212, research and development costs related to the acquired company of $658, and selling, general, and administrative costs related to the acquired company of $20.
Three Months Ended September 30, 2025
(Unaudited, dollars in thousands)
Core
Payments
Complementary
Corporate
Services
Total
GAAP REVENUE
$ 190,001
$ 230,894
$ 199,509
$ 24,334
$ 644,738
Non-GAAP adjustments*
(3,219)
(3,483)
(1,876)
(48)
(8,626)
NON-GAAP ADJUSTED REVENUE
186,782
227,411
197,633
24,286
636,112
GAAP COST OF REVENUE
71,634
118,660
73,006
85,266
348,566
Non-GAAP adjustments*
(443)
(151)
(308)
(2)
(904)
NON-GAAP ADJUSTED COST OF REVENUE
71,191
118,509
72,698
85,264
347,662
GAAP SEGMENT INCOME
$ 118,367
$ 112,234
$ 126,503
$ (60,932)
Segment Income Margin**
62.3 %
48.6 %
63.4 %
(250.4) %
NON-GAAP ADJUSTED SEGMENT INCOME
$ 115,591
$ 108,902
$ 124,935
$ (60,978)
Non-GAAP Adjusted Segment Income Margin
61.9 %
47.9 %
63.2 %
(251.1) %
Research and Development
39,278
Selling, General, and Administrative
72,829
Non-GAAP adjustments unassigned to a segment***
3,175
NON-GAAP TOTAL ADJUSTED OPERATING EXPENSES
462,944
NON-GAAP ADJUSTED OPERATING INCOME
$ 173,168
*Revenue non-GAAP adjustments for the segments were deconversion revenue. Cost of revenue non-GAAP adjustments for the segments were deconversion costs.
**Segment income margin is calculated by dividing segment income by revenue for each segment. Non-GAAP adjusted segment income margin is calculated by dividing non-GAAP adjusted segment income by non-GAAP adjusted revenue for each segment.
***Non-GAAP adjustments unassigned to a segment were a gain on assets, net, of $3,796 less deconversion costs of $621.
The table below shows our GAAP to non-GAAP guidance for the fiscal year ending June 30, 2027. Fiscal year 2027 non-GAAP guidance excludes the impacts of deconversion revenue and related operating expenses, acquisition revenues and related operating expenses, and the gain on assets, net, and assumes no additional acquisitions or dispositions will be made during the fiscal year.
GAAP to Non-GAAP GUIDANCE
(Dollars in millions, except per share data)
Annual FY’27
Adjusted for
FY’27
Comparison
Reported
Change
(Acquisition)
Low
High
FY26
FY26
FY26
GAAP REVENUE
$ 2,698
$ 2,718
$ 2,544
$ 2,544
$ —
Growth
6.0 %
6.8 %
Deconversions*
30
30
43
43
—
Acquisition
1
1
—
5
(5)
NON-GAAP ADJUSTED REVENUE**
$ 2,667
$ 2,687
$ 2,502
$ 2,496
$ 5
Non-GAAP Adjusted Growth
6.6 %
7.4 %
GAAP OPERATING EXPENSES
$ 2,033
$ 2,043
$ 1,909
$ 1,909
$ —
Growth
6.5 %
7.0 %
Deconversion costs*
7
7
13
13
—
Acquisition costs
2
2
—
8
(8)
Gain on assets, net
—
—
(7)
(7)
—
NON-GAAP ADJUSTED OPERATING
EXPENSES**
$ 2,024
$ 2,033
$ 1,903
$ 1,895
$ 8
Non-GAAP Adjusted Growth
6.3 %
6.8 %
GAAP OPERATING INCOME
$ 665
$ 676
$ 635
$ 635
$ —
Growth
4.8 %
6.4 %
GAAP OPERATING MARGIN
24.7 %
24.9 %
25.0 %
25.0 %
NON-GAAP ADJUSTED OPERATING INCOME**
$ 643
$ 653
$ 598
$ 601
$ (3)
Non-GAAP Adjusted Growth
7.5 %
9.2 %
NON-GAAP ADJUSTED OPERATING MARGIN
24.1 %
24.3 %
23.9 %
24.1 %
GAAP EPS
$ 7.47
$ 7.51
$ 6.98
$ 6.98
$ —
Growth
7.1 %
7.6 %
*Deconversion revenue and related operating expenses are based on actual results for the fiscal three months ended September 30, 2026, and estimates for the remainder of the fiscal year 2027. See the Company’s Form 8-K filed with the Securities and Exchange Commission on October 29, 2026.
**GAAP to Non-GAAP revenue, operating expenses, and operating income may not foot due to rounding.
Balance Sheet and Cash Flow Review
Cash and cash equivalents were $25 million at September 30, 2026, compared to $36 million at September 30, 2025.Trade receivables were $346 million at September 30, 2026, and $308 million at September 30, 2025. The Company had $85 million of borrowings at September 30, 2026, compared to $20 million of borrowings at September 30, 2025.Deferred revenue was $333 million at September 30, 2026, compared to $321 million at September 30, 2025.Stockholders’ equity decreased to $2,100 million at September 30, 2026, compared to $2,173 million at September 30, 2025.
*See table below for Net Cash From Operating Activities and on page 13 for Return on Average Stockholders’ Equity. Tables reconciling the non-GAAP measures Free Cash Flow and Net Operating Profit After Tax Return on Invested Capital (NOPAT ROIC) to GAAP measures are on pages 13 and 14. See the Use of Non-GAAP Financial Information section below for the definitions of Free Cash Flow and NOPAT ROIC.
The following table summarizes net cash from operating activities:
(Unaudited, dollars in thousands)
Three Months Ended September 30,
2026
2025
Net income
$ 160,412
$ 143,986
Depreciation
11,245
10,434
Amortization
44,593
41,458
Change in deferred income taxes
11,354
38,987
Other non-cash expenses
4,578
2,510
Change in receivables
3,288
12,196
Change in deferred revenue
(39,724)
(42,291)
Change in other assets and liabilities*
(34,493)
(86,690)
NET CASH FROM OPERATING ACTIVITIES
$ 161,253
$ 120,590
*For the fiscal three months ended September 30, 2026, the change in other assets and liabilities includes the change in accrued expenses of $(34,551), the change in prepaid expenses, deferred costs and other of $(31,640), and the change in accounts payable of $(4,123), partially offset by the change in income taxes of $35,821. For the fiscal three months ended September 30, 2025, the change in other assets and liabilities includes the change in accrued expenses of $(36,567), the change in prepaid expenses, deferred costs and other of $(34,336), the change in income taxes of $(9,150), and the change in accounts payable of $(6,637).
The following table summarizes net cash from investing activities:
(Unaudited, dollars in thousands)
Three Months Ended September 30,
2026
2025
Payment for acquisitions
$ —
$ (42,390)
Capital expenditures
(26,960)
(8,880)
Proceeds from sale of assets
—
7,479
Purchased software
(1,577)
(1,509)
Computer software developed
(49,784)
(48,203)
Purchase of investments
(1,000)
(6,000)
Proceeds from investments
4,000
1,000
NET CASH FROM INVESTING ACTIVITIES
$ (75,321)
$ (98,503)
The following table summarizes net cash from financing activities:
(Unaudited, dollars in thousands)
Three Months Ended September 30,
2026
2025
Borrowings on credit facilities
$ 188,000
$ 20,000
Repayments on credit facilities
(143,000)
—
Purchase of treasury stock
(70,903)
(62,045)
Dividends paid
(42,768)
(42,145)
Net cash from issuance of stock and tax related to stock-based
compensation
(3,961)
(3,611)
NET CASH FROM FINANCING ACTIVITIES
$ (72,632)
$ (87,801)
Use of Non-GAAP Financial Information
Generally Accepted Accounting Principles (GAAP) is the term used to refer to the standard framework of guidelines for financial accounting in the United States. GAAP includes the standards, conventions, and rules accountants follow in recording and summarizing transactions in the preparation of financial statements. In addition to reporting financial results in accordance with GAAP, we have provided certain non-GAAP financial measures, including adjusted revenue, adjusted segment revenue, adjusted operating income, adjusted segment income, adjusted cost of revenue, adjusted segment cost of revenue, adjusted operating expenses, adjusted operating margin, adjusted segment income margin, non-GAAP earnings before interest, taxes, depreciation, and amortization (non-GAAP EBITDA), free cash flow, free cash flow conversion, net operating profit after tax return on invested capital (NOPAT ROIC), and non-GAAP adjusted net income. We also present key revenue, which is the sum of cloud services revenue and processing revenue, and non-key revenue, which is all other GAAP revenue. Key revenue and non-key revenue are components of GAAP revenue and are presented because management views key revenue as the strategic recurring revenue of the business most important for long-term growth.
We believe non-GAAP financial measures help investors better understand the underlying fundamentals and operating performance of our business. Adjusted revenue, adjusted segment revenue, adjusted operating income, adjusted operating margin, adjusted segment income, adjusted segment income margin, adjusted cost of revenue, adjusted segment cost of revenue, adjusted operating expenses, and adjusted net income eliminate deconversion revenue and associated costs, the gain on assets, net, and an acquisition, which management believes are not indicative of the Company’s operating performance. Such adjustments give investors further insight into our performance. Non-GAAP EBITDA is defined as net income attributable to the Company before the effect of interest income, net, taxes, depreciation, and amortization, adjusted for net income before the effect of interest income, net, taxes, depreciation, and amortization attributable to eliminated deconversions, the gain on assets, net, and an acquisition. Free cash flow is defined as net cash from operating activities, less capitalized expenditures, internal use software, and capitalized software, plus proceeds from the sale of assets. NOPAT ROIC is defined as operating income for the trailing four quarters multiplied by one minus the average effective tax rate (ETR) for the trailing four quarters, with the result divided by average invested capital (average of the beginning and ending period balances). Free cash flow conversion is defined as free cash flow, less proceeds from sale of assets, divided by net income. Management believes that non-GAAP EBITDA is an important measure of the Company’s overall operating performance and excludes certain costs and other transactions that management does not consider indicative of the Company’s ongoing operating performance; free cash flow is useful to measure the funds generated in a given period that are available for debt service requirements and strategic capital decisions; free cash flow conversion is useful to measure the efficiency with which operating results are converted into free cash flow; and NOPAT ROIC is a measure of the Company’s allocation efficiency and effectiveness of its invested capital. For these reasons, management also uses these non-GAAP financial measures in its assessment and management of the Company’s performance.
Non-GAAP financial measures used by the Company may not be comparable to similarly titled non-GAAP measures used by other companies. Non-GAAP financial measures have no standardized meaning prescribed by GAAP and therefore, are unlikely to be comparable with calculations of similar measures for other companies.
Any non-GAAP financial measures should be considered in context with the GAAP financial presentation and should not be considered in isolation or as a substitute for GAAP measures. Reconciliations of the non-GAAP financial measures to related GAAP measures are included.
About Jack Henry & Associates, Inc.®
Jack Henry® (Nasdaq: JKHY) is a well-rounded financial technology company that strengthens connections between financial institutions and the people and businesses they serve. We are an S&P 500 company that prioritizes openness, collaboration, and user centricity — offering banks and credit unions a vibrant ecosystem of internally developed modern capabilities as well as the ability to integrate with leading fintechs. For 50 years, Jack Henry has provided technology solutions to enable clients to innovate faster, strategically differentiate, and successfully compete while serving the evolving needs of their accountholders. We empower approximately 7,200 clients with people-inspired innovation, personal service, and insight-driven solutions that help reduce the barriers to financial health. Additional information is available at www.jackhenry.com.
Quarterly Conference Call
The Company will hold a conference call on November 4, 2026, at 7:45 a.m. Central Time, and investors are invited to listen at www.jackhenry.com. A webcast replay will be available approximately one hour after the event at ir.jackhenry.com/corporate-events-and-presentations and will remain available for one year.
Statements made in this news release that are not historical facts, including the Company’s fiscal 2027 guidance and statements regarding future performance, are “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995, Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934. Because forward-looking statements relate to the future, they are subject to inherent risks and uncertainties that could cause actual results to differ materially from those expressed or implied by such statements. Such risks and uncertainties include, but are not limited to, those discussed in the Company’s Securities and Exchange Commission filings, including the Company’s most recent reports on Form 10-K and Form 10-Q, particularly under the heading Risk Factors. Any forward-looking statement made in this news release speaks only as of the date of the news release, and the Company expressly disclaims any obligation to publicly update or revise any forward-looking statement, whether because of new information, future events or otherwise.
Consolidated Statements of Income (Unaudited)
(Dollars in thousands, except per share data)
Three Months Ended September 30,
%
Change
2026
2025
REVENUE
$ 701,547
$ 644,738
8.8 %
Cost of Revenue
376,046
348,566
7.9 %
Research and Development
45,781
39,278
16.6 %
Selling, General, and Administrative
72,649
72,829
(0.2) %
EXPENSES
494,476
460,673
7.3 %
OPERATING INCOME
207,071
184,065
12.5 %
Interest income
5,092
7,139
(28.7) %
Interest expense
(1,528)
(886)
72.5 %
Interest Income, net
3,564
6,253
(43.0) %
INCOME BEFORE INCOME TAXES
210,635
190,318
10.7 %
Provision for Income Taxes
50,223
46,332
8.4 %
NET INCOME
$ 160,412
$ 143,986
11.4 %
Diluted net income per share
$ 2.28
$ 1.97
Diluted weighted average shares outstanding
70,262
72,909
Consolidated Balance Sheet Highlights (Unaudited)
(Dollars in thousands)
September 30,
%
Change
2026
2025
Cash and cash equivalents
$ 25,356
$ 36,239
(30.0) %
Receivables
345,823
307,647
12.4 %
Total assets
3,194,748
3,047,572
4.8 %
Accounts payable and accrued expenses
$ 247,007
$ 190,667
29.5 %
Debt
85,000
20,000
325.0 %
Deferred revenue
332,747
321,082
3.6 %
Stockholders’ equity
2,099,643
2,173,334
(3.4) %
Calculation of Non-GAAP Earnings Before Interest Income, Net, Income Taxes, Depreciation and Amortization
(Non-GAAP EBITDA)
Three Months Ended September 30,
%
Change
(Dollars in thousands)
2026
2025
Net income
$ 160,412
$ 143,986
Net interest
(3,564)
(6,253)
Taxes
50,223
46,331
Depreciation and amortization
55,839
51,892
Less: Net income before interest expense, taxes, depreciation and
amortization attributable to eliminated non-GAAP adjustments*
(14,925)
(10,897)
NON-GAAP EBITDA
$ 247,985
$ 225,059
10.2 %
*The fiscal first quarter 2027 and 2026 adjustments for net income before interest expense, taxes, depreciation and amortization were for deconversions of ($15,199) and an acquisition of $274, and were for deconversions of ($7,101) and a gain on assets, net, of ($3,796), respectively.
Calculation of Free Cash Flow (Non-GAAP)
Three Months Ended
September 30,
(Dollars in thousands)
2026
2025
Net cash from operating activities
$ 161,253
$ 120,590
Capitalized expenditures
(26,960)
(8,880)
Internal use software
(1,577)
(1,509)
Proceeds from sale of assets
—
7,479
Capitalized software
(49,784)
(48,203)
FREE CASH FLOW
$ 82,932
$ 69,477
Net income
$ 160,412
$ 143,986
Operating cash conversion*
100.5 %
83.8 %
Free cash flow conversion (excluding proceeds from sale of assets)*
51.7 %
43.1 %
*Operating cash conversion is net cash from operating activities divided by net income. Free cash flow conversion is free cash flow less proceeds from sale of assets of $0 for the fiscal three months ended September 30, 2026, and $7,479 for the three months ended September 30, 2025, divided by net income.
Calculation of the Return on Average Stockholders’ Equity
September 30,
(Dollars in thousands)
2026
2025
Net income (trailing four quarters)
$ 519,202
$ 480,543
Average stockholders’ equity (period beginning and ending balances)
2,136,489
2,049,181
RETURN ON AVERAGE STOCKHOLDERS’ EQUITY
24.3 %
23.5 %
Calculation of NOPAT ROIC (Non-GAAP)
September 30,
(Dollars in thousands)
2026
2025
Operating income (trailing four quarters)
$ 658,039
$ 601,504
Average Effective Tax Rate (trailing four quarters)
22.7 %
22.4 %
NOPAT operating income (trailing four quarters)*
508,664
466,767
Average stockholders’ equity (period beginning and ending balances)
2,136,489
2,049,181
Average current maturities of long-term debt (period beginning and
ending balances)
—
45,000
Average long-term debt (period beginning and ending balances)
52,500
35,000
Average invested capital (period beginning and ending balances)
2,188,989
2,129,181
NOPAT ROIC
23.2 %
21.9 %
*NOPAT operating income is calculated by multiplying the trailing four quarters operating income by one minus the average ETR. NOPAT ROIC is calculated by dividing NOPAT operating income by average invested capital (period beginning and ending balances).
Reconciliation of Key and Non-Key Revenue
Three Months Ended
September 30,
%
Change
(Dollars in thousands)
2026
2025
GAAP REVENUE
$ 701,547
$ 644,738
8.8 %
Cloud Services
217,701
195,609
11.3 %
Percentage of Total Revenue*
31.0 %
30.3 %
Processing
296,586
267,887
10.7 %
Percentage of Total Revenue*
42.3 %
41.5 %
KEY REVENUE
$ 514,287
$ 463,496
11.0 %
Percentage of Total Revenue*
73.3 %
71.9 %
NON-KEY REVENUE
$ 187,260
$ 181,242
3.3 %
Percentage of Total Revenue*
26.7 %
28.1 %
*Key and non-key revenue components as a percentage of total revenue may not equal 100% due to rounding.
FAQ for Analysts / Investors
(Dollars in thousands)
1. Why does Core segment revenue growth appear to have moderated this quarter?
The current quarter is being compared against a prior year period that included elevated one-time revenues from on-premise implementations and consulting engagements. Excluding those one-time items, growth in key recurring areas of the Core segment grew 8.6%, which is a positive indicator of the ongoing strength of the segment.
2. Why did the Company rename “Public and Private Cloud” revenue to “Cloud Services”?
The Company made this change beginning in the first quarter of fiscal 2027 to simplify presentation and improve clarity. This does not represent any change to the products or services we offer or to previously reported financial results, and prior period amounts are presented on a consistent basis.
3. What were the first quarter of fiscal 2026 segment reclassifications?
During the first quarter of fiscal 2027, the Company transferred a product from the Core segment to the Complementary segment for better alignment. Therefore, first quarter of fiscal 2026 results were recast. Revenue of $5,292 and cost of revenue of $746 were reclassified. Other reclassifications unrelated to the product transfer noted above were $757 of cost of revenue reclassified from Core to Corporate Services to align with current allocation of cost of revenue by segment. These changes are segment-level only and do not affect consolidated results.
4. What is the timing of the Connect Conference?
The Connect Conference is Jack Henry’s annual client conference. The revenue and expenses associated with the conference are included in the Corporate Services segment. The event was held in the first quarter of fiscal 2026 and is in the the second quarter of fiscal 2027. The event will be held in the second quarter for the next four years.
View original content to download multimedia:https://www.prnewswire.com/news-releases/jack-henry–associates-inc-reports-first-quarter-fiscal-2027-results-302928417.html
SOURCE Jack Henry & Associates, Inc.

You may like
Technology
Propel Reports Third Quarter Results and Announces Dividend Increase
Published
55 minutes agoon
November 3, 2026By
TORONTO, Nov. 3, 2026 /CNW/ — Propel Holdings Inc. (“Propel” or the “Company”) (TSX: PRL), the fintech facilitating access to credit for underserved consumers, today reported financial results for the three months ended September 30, 2026 (“Q3 2026”). Propel also announced that its Board of Directors has approved a further increase to its dividend from C$1.02 to C$1.08 per share on an annualized basis, effective Q4 2026. This represents an increase of 6% and the Company’s thirteenth consecutive quarterly dividend increase. All amounts are expressed in U.S. dollars unless otherwise stated.
Financial and Operational Highlights for Q3 2026 (Shown in U.S. Dollars unless otherwise stated)
Comparable metrics relative to Q3 2025, unless otherwise stated
Revenue: increased by 32% to $201.5 million, representing a recordAdjusted EBITDA1: increased by 39% to $44.8 million, representing a recordNet Income: increased by 23% to $18.4 millionAdjusted Net Income1: increased by 54% to $24.9 million, representing a recordDiluted EPS2: increased by 22% to $0.43 (C$0.61)Adjusted Diluted EPS1,2: increased by 53% to $0.59 (C$0.82), representing a recordReturn on Equity3: achieved 25% on an annualized basisAdjusted Return on Equity1: achieved 34% on an annualized basisLoans and Advances Receivable: increased by 22% to $529.0 million, a record ending balanceEnding Combined Loan and Advance Balances (“CLAB”)1: increased by 24% to $690.5 million, a record ending balanceDividend: paid a Q3 2026 dividend of C$0.255 per common share on September 3, 2026, representing a 6% increase to our Q2 2026 dividend
Management Commentary
“Propel delivered another strong quarter, with record revenue, Total Originations Funded1, Ending CLAB1, Adjusted EBITDA1 and Adjusted Net Income1, while generating an Adjusted Return on Equity1 of 34%. For the first time in our history, quarterly revenue surpassed $200 million, marking another significant milestone in our growth.
Our results reflect the strength and resilience of our business model against an evolving economic environment. Consumer demand remains strong, while credit performance is consistent with our seasonal expectations. Importantly, we achieved this growth while maintaining a disciplined approach to underwriting with our Bank Partners.
Our expanding geographic presence and diversified marketing channels are enabling us to reach more consumers than ever before. New customer originations increased 55% year-over-year, including Lending as a Service. At the same time, our investments in AI, automation and operating infrastructure are driving greater efficiencies and enabling continued profitable growth.
These results demonstrate the scalability of our platform, the strength of our execution and the significant opportunity that remains ahead of us. Fifteen years into our journey, and five years since going public, we remain as ambitious as ever to expand access to credit for underserved consumers while delivering profitable growth in 2026 and beyond,” said Clive Kinross, Chief Executive Officer.
Discussion of Financial Results and Business Strategy
Platform expansion and strong demand drove record Total Originations Funded1 and Ending CLAB1Propel and its Bank Partners delivered record quarterly Total Originations Funded1, supported by strong demand from new, returning and existing customersTotal Originations Funded1 increased by 27% year-over-year to a quarterly record of $260.7 million, driving Ending CLAB1 to a record of $690.5 million, up 24% from Q3 2025New customer Total Originations Funded1 grew by 37% year-over-year and by 55% when including Lending-as-a-Service, reflecting continued success in expanding the Company’s customer baseNew customers represented 47% of Total Originations Funded1, compared to 44% in Q3 2025, marking the highest proportion since Q4 2024. This reflects strong demand and the Company’s expanding geographic footprint and distribution channelsAnnualized Revenue Yield1 increased to 121% in Q3 2026 from 113% in Q3 2025, primarily reflecting the growth in new customer originations, the continued scaling of Lending-as-a-Service (“LaaS”), and a greater contribution from higher yielding segmentsThe combination of higher Average CLAB1 and an improved Annualized Revenue Yield1 contributed to record quarterly revenue of $201.5 million, an increase of 32% compared to Q3 2025, marking the first time quarterly revenue surpassed $200 millionDisciplined underwriting and a resilient consumer supported credit performance consistent with seasonal expectationsProvision for loan losses and other liabilities was 53% of revenue, compared to 52% in Q3 2025, driven mainly by a higher proportion of new customer originations. Net Charge-Offs as a percentage of Average CLAB1 remained at approximately 12%, consistent with the prior year, reflecting disciplined underwriting and credit performance consistent with seasonal expectations while achieving record Total Originations Funded1Net income and record Adjusted Net Income1 reflect disciplined execution and operating efficiencyNet income increased by 23% to $18.4 million, while Adjusted Net Income1 increased by 54% to a record $24.9 million in Q3 2026Strong profitability was supported by record revenue and growing efficiencies from investments in technology, AI, automation and operating infrastructure, which are helping support the Company’s ability to scaleAcquisition and data expenses decreased sequentially despite record originations, while the Cost Per New Customer Funded Origination1 declined by 23% since Q1 2026, reflecting improving acquisition efficiencies as the Company’s distribution channels continue to scaleContinued growth across Propel’s expanding platformLaaS delivered record revenue of $13.5 million in Q3 2026, an increase of 170% year-over-yearLaaS growth was enabled by geographic and product expansion and committed long-term capital partners. Through a capital-light model this program generates fee-based revenue without corresponding balance-sheet funding requirementsPropel UK delivered record revenue of $22.0 million, an increase of 69% year-over-year, reflecting disciplined underwriting, expanded marketing channels and strong consumer demandApproaching the second anniversary of the QuidMarket acquisition, the business continued to deliver strong growth, supported by Propel’s capital, expertise and operational capabilities, reinforcing the opportunity in the UK marketPropel Bank contributed to Propel’s growth through its U.S. servicing activities, while continuing to expand its capabilities and create additional opportunities for long-term growthStrong financial position supports continued growth, increasing dividends and disciplined capital managementThe Company maintained a strong financial position at quarter end, with approximately $71 million of undrawn credit commitment capacity and a Debt-to-Equity3 ratio of 1.2xDespite significant portfolio growth, the Debt-to-Equity3 ratio improved from 1.3x at the end of Q4 2025, reflecting strong internal capital generation and disciplined balance sheet managementThe Company’s cost of debt decreased to 10.2% in Q3 2026 from 11.0% in Q3 2025, primarily reflecting lower interest ratesThe Company’s strong financial position and continued earnings generation supported a 6% increase in the quarterly dividend to C$0.27 per common share beginning in Q4 2026, representing the thirteenth consecutive quarterly dividend increase
Notes:
(1)
See “Non-IFRS Financial Measures and Industry Metrics” and “Reconciliation of Non-IFRS Financial Measures” below. See also “Key Components of Results of Operations” in the accompanying Q3 2026 MD&A for further details concerning the non-IFRS financial measures and industry metrics used in this press release including definitions and reconciliations to the relevant reported IFRS measure.
(2)
Results converted from USD to CAD assuming an exchange rate of USD/CAD $1.3993 for the three-month period ending September 30, 2026.
(3)
See “Supplemental Financial Measures” in the accompanying Q3 2026 MD&A for further details concerning certain financial metrics used in this press release including definitions.
Dividend Increase
Propel also announced today that its Board of Directors has approved an increase in the quarterly dividend from C$0.255 to C$0.27 per common share, or from C$1.02 to C$1.08 per common share on an annualized basis. This represents an increase of 6% and the Company’s thirteenth consecutive quarterly dividend increase. The Board declared a dividend of C$0.27 per common share, payable on December 3, 2026 to shareholders of record as of the close of business on November 26, 2026. The Company has designated this dividend as an eligible dividend within the meaning of the Income Tax Act (Canada).
Conference Call Details
The Company will be hosting a conference call and webcast tomorrow morning with a presentation by Clive Kinross, Chief Executive Officer, and Sheldon Saidakovsky, Chief Financial Officer.
Conference call details are as follows:
Date:
Wednesday, November 4, 2026
Time:
8:30 a.m. EST
Toll-free North America:
1-888-699-1199
Local Toronto:
1-416-945-7677
Rapid Connect:
Webcast:
Replay:
1-289-819-1450 or 1-888-660-6345 (PIN: 63773#)
About Propel
Propel Holdings (TSX: PRL) the fintech building a new world of financial opportunity for consumers, partners, and investors. Propel’s operating brands — Fora Credit, CreditFresh, MoneyKey and QuidMarket — together with Propel Bank facilitate access to credit for consumers underserved by traditional financial institutions. Through its AI-powered platform, Propel evaluates customers in a more comprehensive way than traditional credit scores can. The result is better products and an expanded credit market for consumers while creating sustainable, profitable growth for Propel. The revolutionary fintech platform has already helped consumers access over 2 million loans and lines of credit and over 3 billion dollars in credit. At Propel, we are here to change the way customers, partners and investors succeed together. Learn more at propelholdings.com.
Non-IFRS Financial Measures and Industry Metrics
This press release makes reference to certain non-IFRS financial measures and industry metrics. These measures are not recognized measures under IFRS and do not have a standardized meaning prescribed by IFRS and are therefore unlikely to be comparable to similar measures presented by other companies. Rather, these measures are provided as additional information to complement those IFRS measures by providing further understanding of our results of operations from management’s perspective. Accordingly, these measures should not be considered in isolation nor as a substitute for analysis of our financial information reported under IFRS. Such measures include “Adjusted Diluted EPS”, “Adjusted EBITDA”, “Adjusted EBITDA Margin”, “Adjusted Net Income”, “Adjusted Net Income Margin”, “Adjusted Return on Equity”, “Average CLAB”, “Cost Per New Customer Funded Origination”, “EBITDA”, “EBITDA Margin”, “Ending CLAB”, “Net Charge-Offs as a percentage of Average CLAB” and “Total Originations Funded”. This press release also includes references to industry metrics such as “Annualized Revenue Yield”, “Return on Equity” and “Total Originations Funded” which are supplementary measures under applicable securities laws.
These non-IFRS financial measures and industry metrics are used to provide investors with supplemental measures of our operating performance and thus highlight trends in our core business that may not otherwise be apparent when relying solely on IFRS measures. We believe that securities analysts, investors and other interested parties frequently use non-IFRS financial measures and industry metrics in the evaluation of issuers. The Company’s management also uses non-IFRS financial measures and industry metrics in order to facilitate operating performance comparisons from period to period, to prepare annual operating budgets and forecasts, and to determine components of management and executive compensation. The key performance indicators used by the Company may be calculated in a manner different than similar key performance indicators used by other similar companies.
Definitions and reconciliations of non-IFRS financial measures to the relevant reported measures can be found in our accompanying MD&A available on SEDAR+. Such reconciliations can also be found in this press release under the heading “Reconciliation of Non-IFRS Financial Measures” below.
Forward-Looking Information
Certain statements made in this press release may constitute forward-looking information under applicable securities laws. These statements may relate to our declared dividend payable on December 3, 2026, our ability to advance our mission of expanding access to credit for underserved consumers while delivering profitable growth in 2026 and beyond, the continued scaling of LaaS, our ability to balance strong growth with prudent risk management and the growth of LaaS becoming an increasingly meaningful contributor to our revenue and profitability. Often but not always, forward-looking statements can be identified by the use of forward-looking terminology such as “may”, “will”, “expect”, “believe”, “estimate”, “plan”, “could”, “should”, “would”, “outlook”, “forecast”, “anticipate”, “foresee”, “continue” or the negative of these terms or variations of them or similar terminology.
Many factors could cause our actual results, level of activity, performance or achievements or future events or developments to differ materially from those expressed or implied by the forward-looking statements, including, without limitation, the factors discussed in the “Risk Factors” section of the Company’s annual information form dated March 2, 2026 for the year ended December 31, 2025 (the “AIF”). A copy of the AIF and the Company’s other publicly filed documents can be accessed under the Company’s profile on SEDAR+ at www.sedarplus.ca.
The Company cautions that the list of risk factors and uncertainties described in the AIF is not exhaustive and other factors could also adversely affect its results. Readers are urged to consider the risks, uncertainties and assumptions carefully in evaluating the forward-looking information and are cautioned not to place undue reliance on such information. The forward-looking information contained in this press release represents our expectations as of the date of this press release (or as the date they are otherwise stated to be made), and are subject to change after such date. However, we disclaim any intention or obligation or undertaking to update or revise any forward-looking information whether as a result of new information, future events or otherwise, except as required under applicable securities laws.
Selected Financial Information
Three months ended September 30,
Nine months ended September 30,
2026
2025
2026
2025
(US$ other than percentages)
Revenue
201,465,666
152,067,808
547,142,957
433,958,089
Provision for loan losses and other liabilities
107,566,480
78,996,521
272,323,411
208,863,235
Operating expenses
Acquisition and data
25,669,184
18,301,712
76,023,391
53,025,405
Salaries, wages and benefits
14,568,533
11,736,681
43,151,501
35,464,264
General and administrative
3,932,072
3,233,180
11,358,770
10,066,210
Processing, technology and program servicing
13,140,307
8,191,663
35,351,818
23,692,649
Total operating expenses
57,310,096
41,463,236
165,885,480
122,248,528
Operating income
36,589,090
31,608,051
108,934,066
102,846,326
Other (income) expenses
Interest and fees on credit facilities
9,098,032
8,600,196
26,196,725
25,402,713
Interest expense on lease liabilities
290,912
223,375
835,757
462,848
Depreciation and amortization
2,729,877
2,361,671
8,011,662
6,538,351
Foreign exchange (gain) loss
115,748
(21,299)
(31,702)
280,903
Unrealized (gain) loss on derivative financial
instruments
65,788
459,925
686,581
(626,601)
Total other (income) expenses
12,300,357
11,623,868
35,699,023
32,058,214
Income before income tax
24,288,733
19,984,183
73,235,043
70,788,112
Income tax expense (recovery)
Current
10,172,140
6,665,455
27,002,949
20,705,530
Deferred
(4,298,642)
(1,688,082)
(9,054,589)
(3,500,738)
Net income for the period
18,415,235
15,006,810
55,286,683
53,583,320
Earnings per share ($USD):
Basic
0.47
0.38
1.40
1.37
Diluted
0.43
0.36
1.30
1.27
Earnings per share ($CAD)(1):
Basic
0.65
0.53
1.94
1.92
Diluted
0.61
0.49
1.80
1.77
Return on equity(2)
25 %
24 %
26 %
30 %
Dividends:
Dividends
7,239,124
5,568,308
20,564,479
15,110,474
Dividend per share
0.184
0.142
0.522
0.387
Notes:
(1)
Results converted from USD to CAD assuming an exchange rate of USD/CAD $1.3993 and USD/CAD $1.3851 for the three-month and nine-month periods ending September 30, 2026, respectively, and assuming an exchange rate of USD/CAD $1.3773 and USD/CAD $1.3988 for the three-month and nine-month periods ending September 30, 2025, respectively.
(2)
See “Supplemental Financial Measures” in the accompanying Q3 2026 MD&A for further details concerning certain financial metrics used in this press release including definitions.
Reconciliation of Non-IFRS Financial Measures
The following table provides a reconciliation of Propel’s net income to EBITDA1 and Adjusted EBITDA1:
Three months ended September 30,
Nine months ended September 30,
2026
2025
2026
2025
(US$ other than percentages)
Net Income
18,415,235
15,006,810
55,286,683
53,583,320
Interest and fees on credit facilities
9,098,032
8,600,196
26,196,725
25,402,713
Interest expense on lease liabilities
290,912
223,375
835,757
462,848
Depreciation and amortization
2,729,877
2,361,671
8,011,662
6,538,351
Income Tax Expense (Recovery)
5,873,498
4,977,373
17,948,360
17,204,792
EBITDA(1)
36,407,554
31,169,425
108,279,187
103,192,024
EBITDA Margin(1)
18 %
20 %
20 %
24 %
Unrealized loss (gain) on derivative financial
instruments
65,788
459,925
686,581
(626,601)
Provision for credit losses on current
status accounts(2).
2,848,238
(384,820)
6,921,282
2,466,546
Non-cash change in accounting estimate(2)
—
—
—
1,357,245
Provisions for CSO Guarantee liabilities and
Bank Service Program liabilities
5,453,632
1,018,002
14,589,155
2,326,291
Adjusted EBITDA (1)
44,775,212
32,262,532
130,476,205
108,715,505
Adjusted EBITDA Margin(1).
22 %
21 %
24 %
25 %
Notes:
(1)
See “Non-IFRS Financial Measures and Industry Metrics”.
(2)
Provision and change in accounting estimate adjustments included for loan losses on good standing current principal (Stage 1 — Performing) balances (see “Material Accounting Policies and Estimates — Loans and advances receivable” in the accompanying Q3 2026 MD&A).
The following table provides a reconciliation of Propel’s Net Income to Adjusted Net Income1, Adjusted Return on Equity1 and Adjusted Net Income margin1:
Three months ended September 30,
Nine months ended September 30,
2026
2025
2026
2025
(US$ other than percentages)
Net Income
18,415,235
15,006,810
55,286,683
53,583,320
Unrealized loss (gain) on derivative financial
instruments, net of taxes(2)
48,354
338,045
504,637
(460,552)
Amortization of acquired intangible assets, net of
taxes(2)
360,787
360,787
1,082,361
1,082,361
Provision for credit losses on current status
accounts, net of taxes(2)(3)
2,093,455
(282,843)
5,087,142
1,812,911
Non-cash change in accounting estimate, net of
taxes(2)(3)
—
—
—
997,575
Provisions for CSO Guarantee liabilities and Bank
Service Program liabilities, net of taxes(2)
4,008,420
748,231
10,723,029
1,709,824
Adjusted Net Income(1)
24,926,251
16,171,030
72,683,852
58,725,439
Multiplied by number of periods in year
x4
x4
x1.33
x1.33
Divided by average shareholders’ equity for the
period
291,087,720
255,164,687
279,371,568
239,404,998
Adjusted Return on Equity(1)
34 %
25 %
35 %
33 %
Adjusted Net Income Margin(1)
12 %
11 %
13 %
14 %
Notes:
(1)
See “Non-IFRS Financial Measures and Industry Metrics”.
(2)
Each item is adjusted for after-tax impact, at an effective tax rate of 26.5% for the three and nine-months ended September 30, 2026 and comparative 2025 periods.
(3)
Provision and change in accounting estimate adjustments included for loan losses on good standing current principal (Stage 1 — Performing) balances (see “Material Accounting Policies and Estimates — Loans and advances receivable” in the accompanying Q3 2026 MD&A).
The following table provides a reconciliation of Propel’s Ending CLAB1 to loans and advances receivable:
As at September 30,
As at Dec 31
(US$ other than percentages)
2026
2025
2025
Ending Combined Loan and Advance balances1
690,454,432
557,694,435
589,548,106
Less: Loan and Advance balances owned by third party lenders
pursuant to CSO program
—
(5,590,553)
(3,087,349)
Less: Loan and Advance balances owned by a NBFI pursuant to
the MoneyKey Bank Service program
(127,188,747)
(68,835,979)
(78,702,887)
Loan and Advance owned by the Company
563,265,685
483,267,903
507,757,870
Less: Allowance for Credit Losses
(162,992,389)
(133,203,516)
(137,659,188)
Add: Fees and interest receivable
91,465,338
65,050,661
67,677,786
Add: Acquisition transaction costs
37,244,016
19,716,562
21,987,814
Loans and advances receivable
528,982,650
434,831,610
459,764,282
Note:
(1)
See “Non-IFRS Financial Measures and Industry Metrics”.
SOURCE Propel Holdings Inc.
Technology
WhiteFiber Completes Acquisition of Two North Carolina Data Center Development Sites and Provides NC-1 Update
Published
55 minutes agoon
November 3, 2026By
NEW YORK, Nov. 3, 2026 /PRNewswire/ — WhiteFiber, Inc. (Nasdaq: WYFI) (“WhiteFiber” or the “Company”), a provider of artificial intelligence infrastructure solutions, today announced that, through its wholly owned subsidiary Enovum Data Centers Corp., it has completed the previously announced acquisition of two industrial properties in Yadkin County, North Carolina, designated NC-2 and NC-3. The purchase price for the properties was $60 million, paid in cash.
Located approximately 55 miles from WhiteFiber’s NC-1 campus in Madison, North Carolina, the properties comprise approximately 120 acres of land and 500,000 square feet of existing warehouse space. The properties are expected to provide a combined minimum of 60 megawatts (“MW”) of initial gross utility capacity, with the potential to support up to approximately 200 MW within seven years following closing, subject to confirmation and power availability. WhiteFiber intends to retrofit the properties into data center campuses, building on its regional development experience and operating capabilities.
WhiteFiber has received non-binding letters of intent from a broad range of prospective customers for capacity at NC-2 and NC-3 and expansion capacity at NC-1. These include proposals from investment-grade counterparties and proposals incorporating investment-grade credit support. The Company is engaged in advanced discussions with prospective customers across these opportunities.
WhiteFiber is targeting initial ready-for-service capacity at NC-2 and NC-3 in late 2027, subject to customary development conditions. WhiteFiber’s development spending plans are expected to be aligned with definitive customer agreements and financing.
In connection with the acquisition, the seller will continue to occupy portions of the properties under occupancy and partial leaseback arrangements. These arrangements are expected to offset a portion of property carrying costs as WhiteFiber advances its development plans.
NC-1 Operational and Financing Update
Switchgear-related commissioning issues interrupted service and billing for the first 20 MW IT data hall and delayed NC-1’s ramp to full contracted run-rate billing beyond the previously anticipated August timeframe. Approximately 35 MW of the contracted 40 MW IT deployment is now operational, with work ongoing to bring the remaining 5 MW online.
Capital investment required to deliver the initial contracted deployment is substantially complete, with total development costs currently expected to remain within the Company’s initial budget.
WhiteFiber continues to advance financing for the initial contracted deployment at NC-1 with the previously disclosed prospective lending group. The parties are working through the remaining documentation and closing requirements. There can be no assurance that the financing will be completed.
“We are encouraged by the breadth of customer demand, including proposals from investment-grade counterparties and proposals with investment-grade credit support,” said Sam Tabar, Chief Executive Officer of WhiteFiber. “We are building on our development and operating experience in North Carolina to meet strong customer demand across our portfolio. Our priority is to turn that demand into long-term contracts and develop capacity with the right customer and financing commitments in place. We look forward to working closely with local stakeholders as we develop these sites and being a responsible long-term partner to the community.”
WhiteFiber will report its third-quarter 2026 financial results on November 10, 2026, and provide further financial and operating updates at that time.
About WhiteFiber, Inc.
WhiteFiber is a provider of artificial intelligence (“AI”) infrastructure solutions. WhiteFiber owns high-performance computing data centers and provides cloud services to customers. Our vertically integrated model combines specialized colocation, hosting, and cloud services engineered to maximize performance, efficiency, and margin for generative AI workloads. For more information, visit www.whitefiber.com. Follow us on LinkedIn and X @WhiteFiber.
Forward-Looking Statements
This press release may contain forward-looking statements within the meaning of applicable securities laws. Such statements include, but are not limited to, statements about the Company’s pursuit and potential completion of financing for the initial contracted deployment at NC-1, including the timing and satisfaction of closing requirements; the Company’s ability to bring the remaining MW online;the Company’s plans to develop the properties as data center campuses; expected utility capacity and targeted ready-for-service timelines; prospective customer interest and non-binding letters of intent; and the expected benefits of the Company’s retrofit-first development strategy, including with respect to time-to-market and capital efficiency. These statements may be identified by words such as “will likely result,” “are expected to,” “will continue,” “will allow us to,” “is anticipated,” “estimated,” “expected”, “believe,” “intend,” “plan,” “projection,” “outlook” or words of similar meaning. These forward-looking statements are based upon the current beliefs and expectations of the Company’s management and are inherently subject to significant business, economic and competitive uncertainties and contingencies, many of which are difficult to predict and generally beyond our control. Actual results and the timing of events may differ materially from the results anticipated in these forward-looking statements.
Actual results, performance or achievements may differ materially, and potentially adversely, from any projections and forward-looking statements and the assumptions on which those forward-looking statements are based. There can be no assurance that the forward-looking statements contained herein are reflective of future performance to any degree. You are cautioned not to place undue reliance on forward-looking statements as a predictor of future performance as projected financial information and other information are based on estimates and assumptions that are inherently subject to various significant risks, uncertainties and other factors, many of which are beyond our control. The Company undertakes no obligation to update any forward-looking statements except as required by law. All forward-looking statements speak only as of the date of this press release.
Investor Contact
WhiteFiber
IR@whitefiber.com
View original content to download multimedia:https://www.prnewswire.com/news-releases/whitefiber-completes-acquisition-of-two-north-carolina-data-center-development-sites-and-provides-nc-1-update-302928336.html
SOURCE WhiteFiber, Inc.
Technology
Verra Mobility Announces Inducement Grant under Nasdaq Listing Rule 5635(c)(4)
Published
55 minutes agoon
November 3, 2026By
MESA, Ariz., Nov. 3, 2026 /PRNewswire/ — Verra Mobility Corporation (NASDAQ: VRRM) (the “Company”), a leading provider of smart mobility technology solutions, announced today that it granted an inducement award to Jon Newhard on November 2, 2026, in connection with Mr. Newhard’s appointment as President and Chief Executive Officer of the Company, effective November 1, 2026 (the “CEO Commencement Date”), pursuant to the employment agreement entered into between the Company and Mr. Newhard on October 1, 2026. The award was granted as an inducement material to Mr. Newhard’s employment with the Company and was approved by the Company’s Compensation Committee, in accordance with Nasdaq Listing Rule 5635(c)(4).
The inducement award consists of a one-time grant of 1,583,333 time-vested restricted stock units covering shares of the Company’s Class A common stock, par value $0.0001 per share, valued at $4,750,000 on the date of grant, vesting in three (3) equal annual installments of one-third (1/3) each on each of the first three (3) anniversaries of the CEO Commencement Date, subject to Mr. Newhard’s continued service as the Company’s Chief Executive Officer through and including each such vesting date.
This award was granted pursuant to a stand-alone inducement award agreement outside of the Verra Mobility Corporation Amended and Restated 2018 Equity Incentive Plan, as amended, and is subject to the terms and conditions of the applicable award agreement.
About Verra Mobility
Verra Mobility Corporation (NASDAQ: VRRM) is a leading provider of smart mobility technology solutions that make transportation safer, smarter and more connected. The company sits at the center of the mobility ecosystem, bringing together vehicles, hardware, software, data and people to enable safe, efficient solutions for customers globally. Verra Mobility’s transportation safety systems and parking management solutions protect lives, improve urban and motorway mobility and support healthier communities. The company also solves complex payment, utilization and compliance challenges for fleet owners and rental car companies. Headquartered in Arizona, Verra Mobility operates in North America, Europe, and Australia. For more information, please visit www.verramobility.com.
Forward-Looking Statements
This press release contains “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended, Section 21E of the Securities Exchange Act of 1934, as amended, and the Private Securities Litigation Reform Act of 1995. All statements contained in this press release that are not historical facts, including those regarding the Company’s achievement of its priorities and its other plans, objectives, expectations, business strategies, future operations, financial performance, prospects, and other future events or developments, are forward-looking statements. These forward-looking statements are based on management’s current expectations, assumptions, and estimates as of the date of this press release and are subject to known and unknown risks, uncertainties, and other factors that could cause actual results to differ materially from those expressed or implied by such statements. These risks and uncertainties are described in greater detail under the caption “Risk Factors” in the Company’s Annual Report on Form 10-K, Quarterly Reports on Form 10-Q, and other filings with the U.S. Securities and Exchange Commission. These forward-looking statements speak only as of the date of this press release and except to the extent required by applicable law, the Company does not assume any obligation to update or revise any forward-looking statement, whether as a result of new information, future events and developments, or otherwise.
Media Relations:
Investor Relations:
Valerie Schneider
Mark Zindler
View original content to download multimedia:https://www.prnewswire.com/news-releases/verra-mobility-announces-inducement-grant-under-nasdaq-listing-rule-5635c4-302928432.html
SOURCE Verra Mobility


Propel Reports Third Quarter Results and Announces Dividend Increase

WhiteFiber Completes Acquisition of Two North Carolina Data Center Development Sites and Provides NC-1 Update

Verra Mobility Announces Inducement Grant under Nasdaq Listing Rule 5635(c)(4)

Send Rakhi to UK swiftly with UK Gifts Portal

Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

Nullmax and Renesas Forge Strategic Partnership to Deliver Competitive ADAS Solutions for the Global Market

Why You Should Build on #NEAR – Co-founder Illia Polosukhin at CV Labs
Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

NEAR End of Year Town Hall 2021: The Open Web World, MetaBUILD 2 Hackathon and 2021 recap
Trending
-

 Coin Market5 days ago
Binance hack may involve private key ‘misuse,’ not theft: Blockaid CEO
-

 Technology5 days ago
From Catapult to capital: NextFin Asia reaches first investment milestone with Indonesia’s Finfra
-
 Technology5 days ago
Thirty Weihai Companies Added to Shandong’s Green Factory List
-
Technology5 days ago
Thirty Weihai Companies Added to Shandong’s Green Factory List
-
Technology5 days ago
Bridge expert Darryl Matson, P.Eng., P.E., of COWI is one of the two winners of ACEC’s prestigious 2026 Beaubien Award
-
 Technology5 days ago
eCloudvalley Renews Strategic Collaboration Agreement with Amazon Web Services and Repositions as a Leader in Product-Led Enterprise AI Transformation Across Asia-Pacific
-
 Technology3 days ago
ModelBest and OpenBMB Open-Source MiniCPM-OCR Series, Delivering High-Performance Document Parsing and AI-Powered Quality Control
-
 Technology5 days ago
Trane Technologies Reports Strong Third-Quarter Results; Raises Full-Year Revenue Guidance, Reaffirms Full-Year EPS Guidance