
Technology
Charter Announces Third Quarter 2026 Results and Launches New Operating Model

Published
6 days agoon
By
New operating model designed to return Charter to growth and transform organization for speed and efficiency.
Will strengthen core Internet offerings and leverage differentiated mobile and video products to drive customer growth and maximize revenue per passing.
Announces new $2 billion in annualized expense savings plan, in addition to the over $1 billion in planned Cox Transactions synergies.
STAMFORD, Conn., Nov. 6, 2026 /PRNewswire/ — Charter Communications, Inc. (along with its subsidiaries, the “Company” or “Charter”) today reported financial and operating results for the three and nine months ended September 30, 2026, and announced a new operating model designed to return the Company to growth, unlock the full potential of its expanded scale following its acquisition of Cox Communications and capitalize on the market growth in demand for data.
“With the combination of Charter and Cox, we have the scale and network capabilities to connect more Americans than ever before,” said Chris Winfrey, President and CEO of Charter. “We are America’s Internet Company® and our purpose is Connecting Gigabit America. Today, we are announcing decisive steps to unlock our full potential.”
Winfrey continued, “We are fundamentally rethinking how we operate and compete, with a renewed focus on delivering the best products and services. We will return Charter to Internet customer growth and transform Charter into a simpler, faster, more agile organization – and reignite our culture to win. We have the assets and competitive advantages to succeed and are moving with urgency to deliver more value for our customers and stronger results for our investors.”
New Operating Model Centered on Growth and Efficiency
Charter is reformulating its go-to-market approach for its core Internet offering, marketing and distribution, and will further leverage its differentiated mobile and video products to drive growth and provide greater value for customers. This new operating model is focused on accelerating new customer connects as well as improving retention and customer satisfaction with improved execution of its service delivery. By delivering added value and improving its service reputation, Charter will deepen customer relationships and maximize revenue per passing over the long term.
In parallel, Charter is undertaking a fundamental redesign of how it operates, reducing complexity, accelerating decision-making and focusing resources on the activities that contribute most directly to growth and stronger performance. As part of this transformation, the Company is targeting $2 billion in annualized run-rate operating expense savings over the next 18 months, in addition to more than $1 billion in anticipated Cox Transactions synergies.
The savings program will focus on eliminating nonessential activities, simplifying organizational structures and driving greater efficiencies through vendor partnerships. Together, these initiatives are expected to strengthen Charter’s competitive position, drive improved financial performance and support significantly higher free cash flow generation over time.
Cox Transactions Completed, Adding Significant Opportunity for Charter’s Growth
On August 19, 2026, Charter completed its transactions between the Company and Cox Communications, Inc. (“Cox Communications”) (the “Cox Transactions”). The Cox Transactions added more than 11 million passings and over 5 million customer relationships, making Charter the nation’s leading Internet and video provider. The acquisition expands Charter’s presence in attractive, high-growth markets, including Phoenix and Las Vegas, and complementary markets across the country, creating significant opportunities to increase residential and small business customer penetration.
In this release, actual results reflect the operations of Charter for the three and nine months ended September 30, 2026 and Cox Communications for the period from August 20, 2026 through September 30, 2026.Pro forma results present the Cox Transactions as if they had closed on January 1, 2024 and include the operations of Charter and Cox Communications for the full three and nine months ended September 30, 2026.
On September 16, 2026, Charter launched Spectrum’s products, pricing and packaging across the legacy Cox footprint, bringing its Internet, mobile and video offerings to more than 11 million homes and businesses. Since launch, Charter has seen strong demand from consumers and an improvement in customer trends across the legacy Cox footprint.
Third Quarter 2026 Results and Highlights
On a pro forma basis, third quarter Spectrum MobileTM lines1 increased by 508,000 and by 1.8 million over the last twelve months. Legacy Charter added 440,000 mobile lines during the quarter. As of September 30, 2026, Charter served 13.5 million mobile lines.Spectrum Internet® customers declined by 233,000 on a pro forma basis during the third quarter, including a decline of 156,000 Internet customers at legacy Charter and 77,000 at legacy Cox. As of September 30, 2026, Charter served 34.3 million Internet customers.On a pro forma basis, video customers decreased by 77,000 in the third quarter compared to a decline of 121,000 in the prior-year period, and declined by 256,000, or 1.8%, over the last twelve months. During the third quarter, legacy Charter lost 38,000 video customers. As of September 30, 2026, Charter served 13.8 million video customers.As of September 30, 2026, Spectrum customer relationships totaled 36.7 million and connectivity customers totaled 35.4 million.Pro forma third quarter revenue of $16.5 billion declined 1.5% year-over-year, primarily driven by lower residential revenue. On an actual basis, third quarter revenue of $14.9 billion increased 9.1% year-over-year, primarily driven by the Cox Transactions.Pro forma third quarter net loss attributable to Charter shareholders totaled $2.1 billion, while on an actual basis, net loss attributable to Charter shareholders totaled $2.4 billion, with both results primarily driven by a $6.3 billion franchise impairment charge.Pro forma third quarter Adjusted EBITDA2 of $6.6 billion declined 4.0% year-over-year and 3.0% excluding transition expenses. On an actual basis, third quarter Adjusted EBITDA of $5.9 billion grew 6.9% year-over-year, primarily driven by the Cox Transactions.On a pro forma basis, third quarter capital expenditures declined to $3.2 billion from $3.6 billion in the prior-year period. On an actual basis, capital expenditures totaled $3.0 billion.Third quarter actual net cash flows from operating activities of $4.0 billion versus $4.5 billion in the prior year driven by timing of cash tax payments year-over-year and one-time cash costs related to the Cox Transactions.Third quarter actual free cash flow2 of $674 million declined $947 million versus the prior year, primarily due to lower net cash flows from operating activities and an unfavorable change in accrued expenses related to capital expenditures.During the quarter, Charter exchanged $5.5 billion in aggregate principal amount of secured notes for a combination of approximately $4.0 billion in cash and new secured notes, resulting in approximately $1.5 billion in deleveraging, and repaid $1.0 billion of legacy Cox notes at maturity.
1.
Unless otherwise specified, customer data represents residential and small business customers for legacy Charter and residential customers only for legacy Cox.
2.
Adjusted EBITDA and free cash flow are non-GAAP measures defined in the “Use of Adjusted EBITDA and Free Cash Flow Information” section and are reconciled to net income attributable to Charter shareholders and net cash flows from operating activities, respectively, in the addendum of this news release.
Key Operating Results
Approximate as of
Actual
Pro Forma
September 30, 2026 (e)
September 30, 2025 (e)
Y/Y Change
Footprint
Estimated Passings (f)
70,706
69,156
2.2 %
Customer Relationships (g)
Residential
34,476
35,419
(2.7) %
Small Business (h)
2,215
2,239
(1.1) %
Total Customer Relationships
36,691
37,658
(2.6) %
Residential
(230)
(152)
(78)
Small Business (h)
(8)
(2)
(6)
Pro forma total Customer Relationships Quarterly Net Additions
(238)
(154)
(84)
Total Customer Relationship Penetration of Estimated Passings (i)
51.9 %
54.5 %
(2.6) ppts
Pro forma Monthly Residential Revenue per Residential Customer (j)
$ 117.85
$ 119.71
(1.6) %
Monthly Small Business Revenue per Small Business Customer (h)(k)
$ 163.74
$ 161.97
1.1 %
Residential Customer Relationships Penetration (l)
One Product Penetration
50.8 %
52.0 %
(1.2) ppts
Two Product Penetration
33.1 %
31.9 %
1.2 ppts
Three or More Product Penetration
16.2 %
16.0 %
0.2 ppts
Connectivity (m)
Residential
33,294
34,084
(2.3) %
Small Business (h)
2,064
2,077
(0.6) %
Total Connectivity Customers
35,358
36,161
(2.2) %
Residential
(190)
(107)
(83)
Small Business (h)
(5)
1
(6)
Pro forma total Connectivity Quarterly Net Additions
(195)
(106)
(89)
Internet
Residential
32,289
33,173
(2.7) %
Small Business (h)
2,025
2,039
(0.7) %
Total Internet Customers
34,314
35,212
(2.5) %
Residential
(228)
(170)
(58)
Small Business (h)
(5)
(1)
(4)
Pro forma total Internet Quarterly Net Additions
(233)
(171)
(62)
Mobile Lines (n)
Residential
12,992
11,282
15.2 %
Small Business (h)
460
374
22.8 %
Total Mobile Lines
13,452
11,656
15.4 %
Residential
489
494
(5)
Small Business (h)
19
20
(1)
Pro forma total Mobile Lines Quarterly Net Additions
508
514
(6)
Video (o)
Residential
13,298
13,519
(1.6) %
Small Business (h)
503
538
(6.5) %
Total Video Customers
13,801
14,057
(1.8) %
Residential
(66)
(115)
49
Small Business (h)
(11)
(6)
(5)
Pro forma total Video Quarterly Net Additions
(77)
(121)
44
Voice
Residential
4,952
5,730
(13.6) %
Small Business (h)
1,191
1,219
(2.3) %
Total Voice Customers
6,143
6,949
(11.6) %
In thousands, except per customer and penetration data. See footnotes to unaudited summary of operating statistics on page 11 of the addendum of this news release. The footnotes contain important disclosures regarding the definitions used for these operating statistics. All percentages are calculated using whole numbers. Minor differences may exist due to rounding.
Third Quarter Performance Highlights
On September 16, 2026, Charter launched Spectrum Day across the legacy Cox footprint, introducing Spectrum’s products, pricing and packaging to more than 11 million homes and businesses. Customers in legacy Cox markets now have access to Internet with no data caps, a year of free Spectrum Mobile for eligible customers, a $1,000 Savings Guarantee for customers who bundle Internet and two Mobile lines and TV plans with up to $132 per month in streaming app value. Customers will also benefit from Spectrum’s Customer Commitment, supported by 100% U.S.-based employees, with Spectrum fully returning legacy Cox’s customer service function to the U.S. over the next 18 months. Since launch, Charter has seen strong demand from consumers and an improvement in customer trends across the legacy Cox footprint.
On a pro forma basis, third quarter Internet customers decreased by 233,000, compared to a decline of 171,000 during the third quarter of 2025. Legacy Charter lost 156,000 Internet customers versus a loss of 109,000 during the third quarter of 2025. Spectrum increasingly offers symmetrical and multi-gigabit Internet speeds across its entire footprint and has launched symmetrical Internet service in several markets. In February 2026, Spectrum launched its Invincible WiFiTM product, a tri-band advanced WiFi 7 router that integrates 5G cellular and battery backup to keep customers seamlessly and fully connected during a power outage or network disruption. In the first quarter of 2026, Spectrum launched its $1,000 savings guarantee; new or existing Spectrum Internet customers switching two or more mobile lines from Verizon, AT&T or T-Mobile are guaranteed $1,000 of savings in their first year, or Spectrum will cover the difference.
During the third quarter of 2026, Charter added 508,000 mobile lines on a pro forma basis, compared to an increase of 514,000 during the third quarter of 2025. Legacy Charter added 440,000 mobile lines versus an increase of 482,000 during the third quarter of 2025. Spectrum Mobile has faster wireless speeds than the competition (AT&T, T-Mobile, Verizon).1
Video customers decreased by 77,000 in the third quarter of 2026 on a pro forma basis, compared to a decline of 121,000 in the third quarter of 2025. Legacy Charter lost 38,000 video customers versus a loss of 70,000 during the third quarter of 2025, with the improvement driven by benefits from the inclusion of programmers’ streaming applications in Spectrum’s expanded basic video packages and simplified pricing and packaging.
Spectrum Stream TV video customers now receive up to approximately $132 per month of programmers’ streaming application retail value at no extra cost, including the ad-supported versions of Disney+, Hulu, ESPN Unlimited, HBO Max, Paramount+, Peacock, AMC+, ViX, Tennis Channel, Fox One and Discovery+. Beginning in June 2026, Spectrum customers can purchase ad-supported and ad-free versions of Netflix through Spectrum App Central. Spectrum App Central is an innovative digital marketplace where Spectrum TV customers can activate, manage and upgrade the streaming apps included with their video plans. Spectrum App Central also allows Spectrum customers without a traditional TV package to purchase and manage streaming apps à la carte.
Charter continues to work with federal, state and local governments to bring Spectrum Internet to unserved and underserved communities. During the third quarter of 2026, legacy Charter activated 116,000 subsidized rural passings. Within legacy Charter’s subsidized rural footprint, total customer relationships increased by 48,000 in the third quarter of 2026.
1.
Based on Download Speeds among top 5 national providers in Opensignal USA, Converged Experience, April 2026.
Third Quarter Financial Results
(in millions)
Three Months Ended September 30,
2026
2025
2026
2025
Pro Forma
Pro Forma
% Change
Actual
Actual
% Change
Revenues:
Internet
$ 7,097
$ 7,366
(3.7) %
$ 6,395
$ 5,971
7.1 %
Mobile service
1,158
987
17.3 %
1,134
954
18.9 %
Connectivity
8,255
8,353
(1.2) %
7,529
6,925
8.7 %
Video
3,609
4,003
(9.8) %
3,292
3,389
(2.9) %
Voice
366
393
(6.8) %
340
332
2.6 %
Residential revenue
12,230
12,749
(4.1) %
11,161
10,646
4.8 %
Legacy Charter small business
1,090
1,088
0.1 %
1,090
1,088
0.1 %
Legacy Charter mid-market & large business
762
747
2.1 %
762
747
2.1 %
Legacy Cox Communications business
839
848
(1.1) %
397
—
n/a
Commercial revenue
2,691
2,683
0.3 %
2,249
1,835
22.6 %
Advertising sales
487
403
21.0 %
460
356
29.2 %
Other
1,097
929
18.1 %
1,052
835
26.0 %
Total Revenues
$ 16,505
$ 16,764
(1.5) %
$ 14,922
$ 13,672
9.1 %
Net income (loss) attributable to Charter shareholders
$ (2,079)
$ 952
(318.4) %
$ (2,397)
$ 1,137
(310.8) %
Net income (loss) attributable to Charter shareholders margin
(12.6) %
5.7 %
(16.1) %
8.3 %
Adjusted EBITDA1
$ 6,587
$ 6,862
(4.0) %
$ 5,943
$ 5,561
6.9 %
Adjusted EBITDA margin
39.9 %
40.9 %
39.8 %
40.7 %
Capital expenditures
$ 3,235
$ 3,642
(11.2) %
$ 3,027
$ 3,051
(0.8) %
Net cash flows from operating activities
$ 4,027
$ 4,480
(10.1) %
Free cash flow1
$ 674
$ 1,621
(58.4) %
All percentages are calculated using whole numbers. Minor differences may exist due to rounding.
1.
Adjusted EBITDA and free cash flow are non-GAAP measures defined in the “Use of Adjusted EBITDA and Free Cash Flow Information” section and are reconciled to net income attributable to Charter shareholders and net cash flows from operating activities, respectively, in the addendum of this news release.
Revenues
On a pro forma basis, third quarter revenue decreased by 1.5% year-over-year to $16.5 billion, driven by lower residential video revenue mostly due to higher costs allocated to programmer streaming applications and netted within video revenue and lower residential Internet revenue, partly offset by higher mobile device revenue, an increase in residential mobile service revenue and higher advertising sales revenue. Excluding advertising sales revenue and costs allocated to programmer streaming applications and netted within video revenue, third quarter total revenue declined by 1.0% year-over-year on a pro forma basis. On an actual basis, third quarter revenue increased by 9.1% year-over-year to $14.9 billion, driven by the Cox Transactions.
Pro forma residential revenue totaled $12.2 billion in the third quarter, a decrease of 4.1% year-over-year, driven by a year-over-year decline in residential customers of 2.7% and a decrease in monthly residential revenue per residential customer of 1.6%. Excluding costs allocated to programmer streaming applications and netted within video revenue, residential revenue declined by 2.6% on a pro forma basis. On an actual basis, residential revenue totaled $11.2 billion in the third quarter, an increase of 4.8% year-over-year, driven by the Cox Transactions.
Third quarter pro forma 2026 monthly residential revenue per residential customer totaled $117.85, a decrease of 1.6% compared to the prior year period. The decline was driven by pricing and packaging mix within Charter’s customer base, $286 million of costs allocated to programmer streaming applications and netted within video revenue versus $106 million in the prior year period and a decline in video customers during the last year, partly offset by the growth of Spectrum Mobile. Excluding costs allocated to programmer streaming applications and netted within video revenue, monthly residential revenue per residential customer decreased 0.1% compared to the prior year period on a pro forma basis.
On a pro forma basis, Internet revenue declined 3.7% year-over-year to $7.1 billion, driven by a decline in Internet customers year-over-year and pricing and packaging mix within Charter’s customer base, partly offset by more favorable bundled revenue allocation year-over-year, promotional rate step-ups and rate adjustments. On an actual basis, Internet revenue increased 7.1% year-over-year to $6.4 billion, driven by the Cox Transactions.
Pro forma third quarter mobile service revenue totaled $1.2 billion, an increase of 17.3% year-over-year, driven by mobile line growth and rate adjustments. On an actual basis, third quarter mobile service revenue totaled $1.1 billion, an increase of 18.9% year-over-year, driven by the Cox Transactions.
Pro forma video revenue totaled $3.6 billion in the third quarter, a decrease of 9.8% compared to the prior year period, driven by $286 million of costs allocated to programmer streaming applications and netted within video revenue versus $106 million in the prior year period, more unfavorable bundled revenue allocation year-over-year, a higher mix of lower priced video packages within Charter’s video customer base and a decline in video customers during the last year, partly offset by promotional rate step-ups and video rate adjustments that pass through programmer rate increases. Excluding costs allocated to programmer streaming applications and netted within video revenue, video revenue declined 5.2% year-over-year. On an actual basis, video revenue totaled $3.3 billion in the third quarter, a decrease of 2.9% compared to the prior year period, with the Cox Transactions partly offsetting the decrease.
On a pro forma basis, voice revenue decreased by 6.8% year-over-year to $366 million, driven by a decline in wireline voice customers, partly offset by voice rate adjustments. On an actual basis, voice revenue increased by 2.6% year-over-year to $340 million, driven by the Cox Transactions.
On a pro forma basis, commercial revenue increased by 0.3% year-over-year to $2.7 billion, driven by legacy Charter mid-market and large business revenue growth of 2.1% year-over-year, partly offset by a decline in legacy Cox business revenue of 1.1%. On an actual basis, commercial revenue increased by 22.6% year-over-year to $2.2 billion, driven by the Cox Transactions.
Pro forma third quarter advertising sales revenue of $487 million increased by 21.0% compared to the year-ago quarter, primarily driven by higher political advertising revenue. On a pro forma basis, excluding political advertising revenue in both periods, advertising sales revenue decreased by 5.2% year-over-year driven by lower linear advertising revenue, partly offset by higher streaming advertising revenue. On an actual basis, third quarter advertising sales revenue of $460 million increased by 29.2% compared to the year-ago quarter, primarily driven by higher political advertising revenue and the Cox Transactions.
On a pro forma basis, other revenue totaled $1.1 billion in the third quarter, an increase of 18.1% compared to the third quarter of 2025, primarily driven by higher mobile device sales. On an actual basis, other revenue totaled $1.1 billion in the third quarter, an increase of 26.0% compared to the third quarter of 2025, primarily driven by higher mobile device sales and the Cox Transactions.
Operating Costs and Expenses
On a pro forma basis, third quarter total operating costs and expenses increased 0.2% year-over-year to $9.9 billion, primarily driven by higher other costs of revenue, offset by lower programming costs. On an actual basis, third quarter total operating costs and expenses increased by 10.7% year-over-year, primarily driven by the Cox Transactions.
On a pro forma basis, third quarter programming costs decreased by $271 million, or 10.3% as compared to the third quarter of 2025, reflecting $286 million of costs allocated to programmer streaming applications and netted within video revenue versus $106 million in the prior year period, fewer video customers and a higher mix of lower cost packages within Charter’s video customer base, partly offset by contractual programming rate increases and renewals.
Other costs of revenue increased by $295 million, or 15.0% year-over-year, on a pro forma basis, primarily driven by higher mobile device sales, higher mobile service direct costs and higher advertising sales costs given higher political revenue.
On a pro forma basis, field and technology operations expenses increased by $62 million, or 3.8% year-over-year, primarily driven by higher vehicle fuel costs, higher labor expense and higher pole rent.
Customer operations expenses decreased by $18 million, or 1.9% year-over-year, on a pro forma basis, driven by lower labor expense.
Marketing and residential sales expenses decreased by $21 million or 1.8% year-over-year, on a pro forma basis, due to lower marketing expenses from cost savings, despite higher marketing activity.
Transition expenses, which represent incremental costs incurred for the integration of the Cox Transactions, totaled $76 million.
On a pro forma basis, other expenses decreased by $103 million, or 6.3% as compared to the third quarter of 2025, primarily driven by lower labor expense.
Net Income (Loss) Attributable to Charter Shareholders
Pro forma net loss attributable to Charter shareholders totaled $2.1 billion in the third quarter of 2026 compared to net income of $1.0 billion in the third quarter of 2025. The year-over-year decline in pro forma net income was primarily driven by an impairment of franchises of $6.3 billion, partly offset by a gain on extinguishment of debt related to debt exchanges of $1.4 billion, lower net income attributable to noncontrolling interest and lower income tax expense. On an actual basis, net loss attributable to Charter shareholders totaled $2.4 billion in the third quarter of 2026 compared to net income of $1.1 billion in the third quarter of 2025, primarily driven by the aforementioned factors.
Actual net loss per basic common share attributable to Charter shareholders totaled $20.50 in the third quarter of 2026 compared to income of $8.50 during the same period last year. The change was primarily the result of the factors described above as well as a 12.6% decrease in basic weighted average common shares outstanding versus the prior year period.
Adjusted EBITDA
Third quarter pro forma Adjusted EBITDA of $6.6 billion declined by 4.0% year-over-year, reflecting a decline in revenue of 1.5% and an increase in operating costs and expenses of 0.2%. Excluding transition expenses, pro forma Adjusted EBITDA declined 3.0% year-over-year. On an actual basis, third quarter Adjusted EBITDA of $5.9 billion increased by 6.9% year-over-year due to the Cox Transactions.
Capital Expenditures
Pro forma capital expenditures totaled $3.2 billion in the third quarter of 2026, compared to $3.6 billion in the prior year period, given lower line extension spend and lower scalable infrastructure spend, partly offset by higher upgrade/rebuild (primarily network evolution). On an actual basis, capital expenditures totaled $3.0 billion in the third quarter of 2026, compared to $3.1 billion in the third quarter of 2025.
Charter expects pro forma full year 2026 capital expenditures, excluding transition capital expenditures, to total approximately $13.0 billion. The actual amount of capital expenditures in 2026 will depend on a number of factors including, but not limited to, the pace of Charter’s network evolution and expansion initiatives, supply chain timing and growth rates in Charter’s residential and commercial businesses.
Cash Flow and Free Cash Flow
During the third quarter of 2026, actual net cash flows from operating activities totaled $4.0 billion, a decrease from $4.5 billion in the prior year. The year-over-year decrease was driven by timing of cash tax payments and one-time cash costs related to the Cox Transactions.
Actual free cash flow in the third quarter of 2026 totaled $674 million, a decrease of $947 million compared to the third quarter of 2025. The year-over-year decrease in free cash flow was driven by lower net cash flows from operating activities and an unfavorable change in accrued expenses related to capital expenditures.
Liquidity & Financing
As of September 30, 2026, total principal amount of debt was $108.6 billion and Charter’s credit facilities provided approximately $2.4 billion of additional liquidity in excess of Charter’s $573 million cash position.
During the three months ended September 30, 2026, Charter Communications Operating, LLC (“Charter Operating”) and Charter Communications Operating Capital Corp. jointly issued $1.75 billion of 6.050% senior secured notes due February 2032 at a price of 99.839% of the aggregate principal amount, $1.0 billion of 6.600% senior secured notes due February 2034 at a price of 99.896% of the aggregate principal amount, $1.0 billion of 6.950% senior secured notes due August 2036 at a price of 99.937% of the aggregate principal amount and $1.0 billion of 7.850% senior secured notes due August 2056 at a price of 99.921% of the aggregate principal amount. The net proceeds were used to pay the cash consideration for the Cox Transactions and for general corporate purposes, including to repay certain indebtedness and to pay related fees and expenses.
During the three months ended September 30, 2026, Charter Operating, Charter Communications Operating Capital Corp. and Time Warner Cable, LLC exchanged approximately $5.5 billion in aggregate principal amount of various series of senior secured notes for a combination of $622 million in cash and approximately $1.7 billion of 7.087% senior secured notes due September 2038 issued at par and approximately $1.7 billion of 7.337% senior secured notes due September 2041 issued at par.
Share Repurchases
During the third quarter, Charter purchased 139,807 shares of Charter Class A common stock for $19 million.
Webcast
Charter will host a webcast on Friday, November 6, 2026 at 8:30 a.m. Eastern Time (ET) related to the contents of this release.
The webcast can be accessed live via the Company’s investor relations website at ir.charter.com. Participants should go to the webcast link no later than 10 minutes prior to the start time to register. The webcast will be archived at ir.charter.com two hours after completion of the webcast.
Additional Information Available on Website
The information in this press release should be read in conjunction with the financial statements and footnotes contained in the Company’s Quarterly Report on Form 10-Q for the three and nine months ended September 30, 2026, which will be posted on the “Results & SEC Filings” section of the Company’s investor relations website at ir.charter.com, when it is filed with the Securities and Exchange Commission (the “SEC”). A slide presentation to accompany the conference call and a trending schedule containing historical customer and financial data will also be available in the “Results & SEC Filings” section.
Use of Adjusted EBITDA and Free Cash Flow Information
The Company uses certain measures that are not defined by U.S. generally accepted accounting principles (“GAAP”) to evaluate various aspects of its business. Adjusted EBITDA and free cash flow are non-GAAP financial measures and should be considered in addition to, not as a substitute for, net income attributable to Charter shareholders and net cash flows from operating activities reported in accordance with GAAP. These terms, as defined by Charter, may not be comparable to similarly titled measures used by other companies. Adjusted EBITDA and free cash flow are reconciled to net income attributable to Charter shareholders and net cash flows from operating activities, respectively, in the Addendum to this release.
Adjusted EBITDA is defined as net income (loss) attributable to Charter shareholders plus net income (loss) attributable to noncontrolling interest, net interest expense, income taxes, depreciation and amortization, impairment of franchises, stock compensation expense, other income (expenses), net and other operating (income) expenses, net, such as restructuring costs, special charges, merger and acquisition costs and (gain) loss on sale or retirement of assets. As such, it eliminates the significant non-cash depreciation and amortization expense that results from the capital-intensive nature of the Company’s businesses as well as other non-cash or special items, and is unaffected by the Company’s capital structure or investment activities. However, this measure is limited in that it does not reflect the periodic costs of certain capitalized tangible and intangible assets used in generating revenues and the cash cost of financing. These costs are evaluated through other financial measures.
Free cash flow is defined as net cash flows from operating activities, less capital expenditures and changes in accrued expenses related to capital expenditures.
Management and Charter’s board of directors use Adjusted EBITDA and free cash flow to assess Charter’s performance and its ability to service its debt, fund operations and make additional investments with internally generated funds. In addition, Adjusted EBITDA generally correlates to the leverage ratio calculation under the Company’s credit facilities or outstanding notes to determine compliance with the covenants contained in the facilities and notes (all such documents have been previously filed with the SEC). For the purpose of calculating compliance with leverage covenants, the Company uses Adjusted EBITDA, as presented, excluding certain expenses paid by its operating subsidiaries to other Charter entities. The Company’s debt covenants refer to these expenses as management fees, which were $377 million and $1.1 billion for the three and nine months ended September 30, 2026, respectively, and $350 million and $1.1 billion for the three and nine months ended September 30, 2025, respectively.
About Charter
Charter Communications, Inc. (NASDAQ: CHTR, CHTRP), through its Spectrum brand, is the leading internet and video provider in the nation and the fastest growing mobile company in our footprint, with services available to more than 70 million homes and businesses across 45 states. Supported by our 100% U.S.-based employees,* we are America’s Internet Company®.
More information about Charter can be found at corporate.charter.com.
*At close of the Cox acquisition, Spectrum announced that over the next 18 months, it will fully return legacy Cox’s customer service function to the U.S.
CAUTIONARY STATEMENT REGARDING FORWARD-LOOKING STATEMENTS
This communication includes forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended, regarding, among other things, our plans, strategies and prospects, both business and financial. Although we believe that our plans, intentions and expectations as reflected in or suggested by these forward-looking statements are reasonable, we cannot assure you that we will achieve or realize these plans, intentions or expectations. Forward-looking statements are inherently subject to risks, uncertainties and assumptions including, without limitation, the factors described under “Risk Factors” from time to time in our filings with the SEC. Many of the forward-looking statements contained in this communication may be identified by the use of forward-looking words such as “believe,” “future,” “expect,” “anticipate,” “should,” “planned,” “will,” “may,” “intend,” “estimated,” “aim,” “on track,” “target,” “opportunity,” “tentative,” “positioning,” “designed,” “create,” “predict,” “project,” “initiatives,” “seek,” “would,” “could,” “continue,” “ongoing,” “upside,” “increases,” “grow,” “focused on” and “potential,” among others. Important factors that could cause actual results to differ materially from the forward-looking statements we make in this communication are set forth in our annual report on Form 10-K, and in other reports or documents that we file from time to time with the SEC, and include, but are not limited to:
our ability to sustain and grow revenues and cash flow from operations by offering Internet, mobile, video, voice, advertising and other services to residential and commercial customers, to adequately meet the customer experience demands in our service areas and to maintain and grow our customer base, particularly in the face of increasingly aggressive competition, the need for innovation and the related capital expenditures;the impact of competition from other market participants, including but not limited to incumbent telephone companies, direct broadcast satellite (“DBS”) operators, wireless and satellite broadband and telephone providers, digital subscriber line (“DSL”) providers, fiber to the home providers and providers of video content over broadband Internet connections;general business conditions, unemployment levels and the level of activity in the housing sector and economic uncertainty or downturn;our ability to develop and deploy new products and technologies including consumer services and service platforms;any events that disrupt our networks, information systems or properties and impair our operating activities or our reputation;the effects of governmental regulation on our business including subsidies to consumers, subsidies and incentives for competitors, costs, disruptions and possible limitations on operating flexibility related to, and our ability to comply with, regulatory conditions applicable to us;our ability to procure necessary services and equipment from our vendors in a timely manner and at reasonable costs including in connection with our network evolution and rural construction initiatives;our ability to obtain programming at reasonable prices or to raise prices to offset, in whole or in part, the effects of higher programming costs (including retransmission consents and distribution requirements);the ability to hire and retain key personnel;the availability and access, in general, of funds to meet our debt obligations prior to or when they become due and to fund our operations and necessary capital expenditures, either through (i) cash on hand, (ii) free cash flow, or (iii) access to the capital or credit markets;our ability to comply with all covenants in our indentures and credit facilities, any violation of which, if not cured in a timely manner, could trigger a default of our other obligations under cross-default provisions;our ability to achieve the cost synergies and growth opportunities contemplated by the Cox Transactions;our ability to promptly, efficiently and effectively integrate acquired operations;changes in our or legacy Cox Communications operations’ businesses, future cash requirements, capital requirements, results of operations, revenues, financial condition and/or cash flows;disruption in our business relationships as a result of the Cox Transactions; andthe increase in indebtedness as a result of the Cox Transactions and the Liberty Broadband Transaction, which will increase interest expense and may decrease our operating flexibility.
All forward-looking statements attributable to us or any person acting on our behalf are expressly qualified in their entirety by this cautionary statement. We are under no duty or obligation to update any of the forward-looking statements after the date of this communication.
CHARTER COMMUNICATIONS, INC. AND SUBSIDIARIES
UNAUDITED RECONCILIATION OF NON-GAAP MEASURES TO GAAP MEASURES
(dollars in millions)
Three Months Ended
September 30,
Nine Months Ended
September 30,
Last Twelve Months
Ended September 30,
2026
2025
2026
2025
2026
2025
Actual
Actual
Actual
Actual
Actual
Actual
Net income (loss) attributable to Charter shareholders
$ (2,397)
$ 1,137
$ 58
$ 3,655
$ 1,390
$ 5,121
Plus: Net income (loss) attributable to noncontrolling interest
(302)
179
130
565
344
775
Interest expense, net
1,341
1,268
3,873
3,772
5,143
5,046
Income tax (benefit) expense
(803)
418
137
1,277
552
1,647
Depreciation and amortization
2,621
2,160
7,029
6,517
9,223
8,685
Impairment of franchises
6,326
—
6,326
—
6,326
—
(Gain) loss on extinguishment of debt
(1,391)
28
(1,630)
28
(1,630)
36
Stock compensation expense
177
151
518
530
661
668
Other, net
371
220
588
673
711
799
Adjusted EBITDA (a)
$ 5,943
$ 5,561
$ 17,029
$ 17,017
$ 22,720
$ 22,777
Net cash flows from operating activities
$ 4,027
$ 4,480
$ 12,256
$ 12,316
$ 16,017
$ 15,776
Less: Purchases of property, plant and equipment
(3,027)
(3,051)
(8,753)
(8,324)
(12,088)
(11,386)
Change in accrued expenses related to capital expenditures
(326)
192
(488)
239
(141)
825
Free cash flow (a)
$ 674
$ 1,621
$ 3,015
$ 4,231
$ 3,788
$ 5,215
Three Months Ended
September 30,
Nine Months Ended
September 30,
Last Twelve Months
Ended September 30,
2026
2025
2026
2025
2026
2025
Pro Forma (b)
Pro Forma (b)
Pro Forma (b)
Pro Forma (b)
Pro Forma (b)
Pro Forma (b)
Net income (loss) attributable to Charter shareholders
$ (2,079)
$ 952
$ (5)
$ 3,039
$ (1,948)
$ 4,127
Plus: Net income (loss) attributable to noncontrolling interest
(634)
625
726
1,950
(218)
2,585
Interest expense, net
1,462
1,523
4,507
4,544
6,032
6,078
Income tax (benefit) expense
(697)
356
117
1,071
(560)
1,315
Depreciation and amortization
3,044
2,993
9,008
9,016
12,035
12,073
Impairment of franchises
6,326
—
6,326
—
11,930
—
(Gain) loss on extinguishment of debt
(1,391)
28
(1,630)
28
(1,630)
36
Stock compensation expense
177
151
518
530
661
668
Other, net
379
234
743
805
997
1,124
Adjusted EBITDA (a)
$ 6,587
$ 6,862
$ 20,310
$ 20,983
$ 27,299
$ 28,006
Plus: Transition expenses (c)
76
4
165
4
180
4
Adjusted EBITDA (a) excluding transition expenses (c)
$ 6,663
$ 6,866
$ 20,475
$ 20,987
$ 27,479
$ 28,010
The above schedules are presented in order to reconcile Adjusted EBITDA and free cash flow, non-GAAP measures, to the most directly comparable GAAP measures in accordance with Section 401(b) of the Sarbanes-Oxley Act.
See footnotes on page 11.
UNAUDITED ALTERNATIVE PRESENTATION OF ADJUSTED EBITDA
(dollars in millions)
Three Months Ended September 30,
Nine Months Ended September 30,
2026
2025
2026
2025
Actual
Actual
% Change
Actual
Actual
% Change
REVENUES:
Internet
$ 6,395
$ 5,971
7.1 %
$ 18,023
$ 17,870
0.9 %
Mobile service
1,134
954
18.9 %
3,281
2,789
17.6 %
Connectivity
7,529
6,925
8.7 %
21,304
20,659
3.1 %
Video
3,292
3,389
(2.9) %
9,693
10,457
(7.3) %
Voice
340
332
2.6 %
1,009
1,034
(2.4) %
Residential revenue
11,161
10,646
4.8 %
32,006
32,150
(0.4) %
Legacy Charter small business
1,090
1,088
0.1 %
3,284
3,272
0.3 %
Legacy Charter mid-market & large business
762
747
2.1 %
2,272
2,221
2.3 %
Legacy Cox Communications business
397
—
n/a
397
—
n/a
Commercial revenue
2,249
1,835
22.6 %
5,953
5,493
8.4 %
Advertising sales
460
356
29.2 %
1,234
1,067
15.7 %
Other
1,052
835
26.0 %
2,852
2,463
15.8 %
Total Revenues
14,922
13,672
9.1 %
42,045
41,173
2.1 %
COSTS AND EXPENSES:
Programming
2,129
2,184
(2.5) %
6,252
6,739
(7.2) %
Other costs of revenue
2,108
1,677
25.7 %
5,710
4,912
16.2 %
Field and technology operations
1,520
1,329
14.4 %
4,091
3,903
4.9 %
Customer operations
824
798
3.3 %
2,375
2,347
1.2 %
Marketing and residential sales
1,034
976
5.9 %
2,880
2,883
(0.1) %
Transition expenses (c)
76
4
n/a
165
4
n/a
Other expense (d)
1,288
1,143
12.7 %
3,543
3,368
5.1 %
Total operating costs and expenses (d)
8,979
8,111
10.7 %
25,016
24,156
3.6 %
Adjusted EBITDA (a)
$ 5,943
$ 5,561
6.9 %
$ 17,029
$ 17,017
0.1 %
All percentages are calculated using whole numbers. Minor differences may exist due to rounding. See footnotes on page 11.
UNAUDITED ALTERNATIVE PRESENTATION OF ADJUSTED EBITDA
(dollars in millions)
Three Months Ended September 30,
Nine Months Ended September 30,
2026
2025
2026
2025
Pro Forma (b)
Pro Forma (b)
% Change
Pro Forma (b)
Pro Forma (b)
% Change
REVENUES:
Internet
$ 7,097
$ 7,366
(3.7) %
$ 21,449
$ 22,168
(3.3) %
Mobile service
1,158
987
17.3 %
3,384
2,877
17.6 %
Connectivity
8,255
8,353
(1.2) %
24,833
25,045
(0.9) %
Video
3,609
4,003
(9.8) %
11,210
12,352
(9.2) %
Voice
366
393
(6.8) %
1,141
1,226
(6.9) %
Residential revenue
12,230
12,749
(4.1) %
37,184
38,623
(3.7) %
Legacy Charter small business
1,090
1,088
0.1 %
3,284
3,272
0.3 %
Legacy Charter mid-market & large business
762
747
2.1 %
2,272
2,221
2.3 %
Legacy Cox Communications business
839
848
(1.1) %
2,537
2,526
0.4 %
Commercial revenue
2,691
2,683
0.3 %
8,093
8,019
0.9 %
Advertising sales
487
403
21.0 %
1,376
1,218
13.0 %
Other
1,097
929
18.1 %
3,067
2,755
11.3 %
Total Revenues
16,505
16,764
(1.5) %
49,720
50,615
(1.8) %
COSTS AND EXPENSES:
Programming
2,346
2,617
(10.3) %
7,318
8,119
(9.9) %
Other costs of revenue
2,268
1,973
15.0 %
6,459
5,806
11.3 %
Field and technology operations
1,680
1,618
3.8 %
4,816
4,787
0.6 %
Customer operations
882
900
(1.9) %
2,628
2,653
(1.0) %
Marketing and residential sales
1,128
1,149
(1.8) %
3,301
3,402
(2.9) %
Transition expenses (c)
76
4
n/a
165
4
n/a
Other expense (d)
1,538
1,641
(6.3) %
4,723
4,861
(2.9) %
Total operating costs and expenses (d)
9,918
9,902
0.2 %
29,410
29,632
(0.7) %
Adjusted EBITDA (a)
$ 6,587
$ 6,862
(4.0) %
$ 20,310
$ 20,983
(3.2) %
All percentages are calculated using whole numbers. Minor differences may exist due to rounding. See footnotes on page 11.
CHARTER COMMUNICATIONS, INC. AND SUBSIDIARIES
UNAUDITED CONSOLIDATED STATEMENTS OF OPERATIONS
(dollars in millions, except per share data)
Three Months Ended
September 30,
Nine Months Ended
September 30,
2026
2025
2026
2025
Actual
Actual
Actual
Actual
REVENUES
$ 14,922
$ 13,672
$ 42,045
$ 41,173
COSTS AND EXPENSES:
Operating costs and expenses (exclusive of items shown separately below)
9,156
8,262
25,534
24,686
Depreciation and amortization
2,621
2,160
7,029
6,517
Impairment of franchises
6,326
—
6,326
—
Other operating expenses, net
345
119
411
323
18,448
10,541
39,300
31,526
Income (loss) from operations
(3,526)
3,131
2,745
9,647
OTHER INCOME (EXPENSES):
Interest expense, net
(1,341)
(1,268)
(3,873)
(3,772)
Other income (expenses), net
1,365
(129)
1,453
(378)
24
(1,397)
(2,420)
(4,150)
Income (loss) before income taxes
(3,502)
1,734
325
5,497
Income tax benefit (expense)
803
(418)
(137)
(1,277)
Consolidated net income (loss)
(2,699)
1,316
188
4,220
Less: Net (income) loss attributable to noncontrolling interests
302
(179)
(130)
(565)
Net income (loss) attributable to Charter shareholders
$ (2,397)
$ 1,137
$ 58
$ 3,655
EARNINGS (LOSS) PER COMMON SHARE ATTRIBUTABLE TO CHARTER
SHAREHOLDERS:
Basic
$ (20.50)
$ 8.50
$ 0.48
$ 26.52
Diluted
$ (20.50)
$ 8.34
$ 0.38
$ 25.95
Weighted average common shares outstanding, basic
116,944,459
133,763,886
120,820,024
137,825,025
Weighted average common shares outstanding, diluted
116,944,459
136,395,133
137,548,849
140,826,301
CHARTER COMMUNICATIONS, INC. AND SUBSIDIARIES
UNAUDITED CONSOLIDATED STATEMENTS OF OPERATIONS
(dollars in millions, except per share data)
Three Months Ended
September 30,
Nine Months Ended
September 30,
2026
2025
2026
2025
Pro Forma (b)
Pro Forma (b)
Pro Forma (b)
Pro Forma (b)
REVENUES
$ 16,505
$ 16,764
$ 49,720
$ 50,615
COSTS AND EXPENSES:
Operating costs and expenses (exclusive of items shown separately below)
10,095
10,053
29,928
30,162
Depreciation and amortization
3,044
2,993
9,008
9,016
Impairment of franchises
6,326
—
6,326
—
Other operating expenses, net
353
131
563
396
19,818
13,177
45,825
39,574
Income (loss) from operations
(3,313)
3,587
3,895
11,041
OTHER INCOME (EXPENSES):
Interest expense, net
(1,462)
(1,523)
(4,507)
(4,544)
Other income (expenses), net
1,365
(131)
1,450
(437)
(97)
(1,654)
(3,057)
(4,981)
Income (loss) before income taxes
(3,410)
1,933
838
6,060
Income tax benefit (expense)
697
(356)
(117)
(1,071)
Consolidated net income (loss)
(2,713)
1,577
721
4,989
Less: Net (income) loss attributable to noncontrolling interests
634
(625)
(726)
(1,950)
Net income (loss) attributable to Charter shareholders
$ (2,079)
$ 952
$ (5)
$ 3,039
EARNINGS (LOSS) PER COMMON SHARE ATTRIBUTABLE TO CHARTER
SHAREHOLDERS:
Basic
$ (17.78)
$ 7.12
$ (0.04)
$ 22.05
Diluted
$ (17.78)
$ 6.98
$ (0.04)
$ 21.58
Weighted average common shares outstanding, basic
116,944,459
133,763,886
120,820,024
137,825,025
Weighted average common shares outstanding, diluted
116,944,459
136,395,133
120,820,024
140,826,301
CHARTER COMMUNICATIONS, INC. AND SUBSIDIARIES
CONDENSED CONSOLIDATED BALANCE SHEETS
(dollars in millions)
September 30,
December 31
2026
2025
ASSETS
(unaudited)
CURRENT ASSETS:
Cash and cash equivalents
$ 573
$ 477
Accounts receivable, net
4,396
3,680
Prepaid expenses and other current assets
1,249
987
Total current assets
6,218
5,144
INVESTMENT IN CABLE PROPERTIES:
Property, plant and equipment, net
62,786
46,444
Customer relationships, net
6,091
440
Franchises
67,915
67,471
Goodwill
29,748
29,710
Total investment in cable properties, net
166,540
144,065
OTHER NONCURRENT ASSETS
5,707
5,004
Total assets
$ 178,465
$ 154,213
LIABILITIES AND SHAREHOLDERS’ EQUITY
CURRENT LIABILITIES:
Accounts payable, accrued and other current liabilities
$ 14,644
$ 12,556
Current portion of long-term debt
1,990
750
Total current liabilities
16,634
13,306
LONG-TERM DEBT
105,062
94,006
EQUIPMENT INSTALLMENT PLAN FINANCING FACILITY
1,696
1,447
DEFERRED INCOME TAXES
18,819
19,841
OTHER LONG-TERM LIABILITIES
6,434
5,094
SHAREHOLDERS’ EQUITY:
Controlling interest
10,983
16,054
Noncontrolling interests
18,837
4,465
Total shareholders’ equity
29,820
20,519
Total liabilities and shareholders’ equity
$ 178,465
$ 154,213
CHARTER COMMUNICATIONS, INC. AND SUBSIDIARIES
UNAUDITED CONSOLIDATED STATEMENTS OF CASH FLOWS
(dollars in millions)
Three Months Ended
September 30,
Nine Months Ended
September 30,
2026
2025
2026
2025
CASH FLOWS FROM OPERATING ACTIVITIES:
Consolidated net income (loss)
$ (2,699)
$ 1,316
$ 188
$ 4,220
Adjustments to reconcile consolidated net income (loss) to net cash flows from operating activities:
Depreciation and amortization
2,621
2,160
7,029
6,517
Impairment of franchises
6,326
—
6,326
—
(Gain) loss on extinguishment of debt
(1,391)
28
(1,630)
28
Stock compensation expense
177
151
518
530
Noncash interest, net
24
7
36
22
Deferred income taxes
(1,020)
852
(603)
772
Other, net
33
120
186
470
Changes in operating assets and liabilities, net of effects from acquisitions and dispositions:
Accounts receivable
(80)
(48)
(216)
(334)
Prepaid expenses and other assets
(288)
(186)
(284)
(355)
Accounts payable, accrued liabilities and other
324
80
706
446
Net cash flows from operating activities
4,027
4,480
12,256
12,316
CASH FLOWS FROM INVESTING ACTIVITIES:
Purchases of property, plant and equipment
(3,027)
(3,051)
(8,753)
(8,324)
Change in accrued expenses related to capital expenditures
(326)
192
(488)
239
Purchase of businesses and asset acquisitions
(4,158)
—
(4,158)
—
Other, net
(27)
(298)
(312)
(497)
Net cash flows from investing activities
(7,538)
(3,157)
(13,711)
(8,582)
CASH FLOWS FROM FINANCING ACTIVITIES:
Borrowings of long-term debt
13,400
6,903
25,010
12,019
Borrowings of equipment installment plan financing facility
99
59
247
292
Repayments of long-term debt
(9,041)
(6,128)
(21,149)
(10,921)
Payments for debt issuance costs
(53)
(16)
(83)
(17)
Purchase of treasury stock (including the Liberty Broadband Transaction)
(21)
(2,113)
(1,899)
(4,366)
Proceeds from exercise of stock options
—
1
13
20
Purchase of noncontrolling interest
—
(121)
—
(373)
Distributions to noncontrolling interest
(25)
—
(47)
(124)
Other, net
(831)
(36)
(619)
(249)
Net cash flows from financing activities
3,528
(1,451)
1,473
(3,719)
NET INCREASE (DECREASE) IN CASH, CASH EQUIVALENTS AND RESTRICTED CASH
17
(128)
18
15
CASH, CASH EQUIVALENTS AND RESTRICTED CASH, beginning of period
599
649
598
506
CASH, CASH EQUIVALENTS AND RESTRICTED CASH, end of period
$ 616
$ 521
$ 616
$ 521
CASH PAID FOR INTEREST
$ 1,294
$ 1,171
$ 3,800
$ 3,610
As of September 30, 2026, June 30, 2026, December 31, 2025, September 30, 2025, June 30, 2025 and December 31, 2024, cash, cash equivalents and restricted cash includes $43 million, $90 million, $121 million, $57 million, $43 million and $47 million of restricted cash included in prepaid expenses and other current assets in the consolidated balance sheets, respectively.
CHARTER COMMUNICATIONS, INC. AND SUBSIDIARIES
UNAUDITED SUMMARY OF OPERATING STATISTICS
(in thousands, except per customer and penetration data)
Approximate as of
September 30,
2026 (e)
June 30,
2026 (e)
December 31,
2025 (e)
September 30,
2025 (e)
Actual
Footprint
Estimated Passings (f)
70,706
58,981
58,399
57,940
Customer Relationships (g)
Residential
34,476
29,276
29,609
29,734
Small Business (h)
2,215
2,223
2,237
2,239
Total Customer Relationships
36,691
31,499
31,846
31,973
Residential
5,200
(176)
(125)
(85)
Small Business (h)
(8)
(8)
(2)
(2)
Total Customer Relationships Quarterly Net Additions
5,192
(184)
(127)
(87)
Total Customer Relationship Penetration of Estimated Passings (i)
51.9 %
53.4 %
54.5 %
55.2 %
Monthly Residential Revenue per Residential Customer (j)
$ 117.12
$ 117.52
$ 117.19
$ 119.16
Monthly Small Business Revenue per Small Business Customer (h)(k)
$ 163.74
$ 165.27
$ 159.85
$ 161.97
Residential Customer Relationships Penetration (l)
One Product Penetration
50.8 %
47.4 %
48.0 %
48.5 %
Two Product Penetration
33.1 %
35.1 %
34.5 %
34.1 %
Three or More Product Penetration
16.2 %
17.6 %
17.5 %
17.4 %
Connectivity (m)
Residential
33,294
28,306
28,563
28,658
Small Business (h)
2,064
2,069
2,077
2,077
Total Connectivity Customers
35,358
30,375
30,640
30,735
Residential
4,988
(140)
(95)
(47)
Small Business (h)
(5)
(5)
—
1
Total Connectivity Quarterly Net Additions
4,983
(145)
(95)
(46)
Internet
Residential
32,289
27,358
27,641
27,760
Small Business (h)
2,025
2,030
2,039
2,039
Total Internet Customers
34,314
29,388
29,680
29,799
Residential
4,931
(166)
(119)
(108)
Small Business (h)
(5)
(6)
—
(1)
Total Internet Quarterly Net Additions
4,926
(172)
(119)
(109)
Mobile Lines (n)
Residential
12,992
12,099
11,370
10,964
Small Business (h)
460
441
396
374
Total Mobile Lines
13,452
12,540
11,766
11,338
Residential
893
385
406
462
Small Business (h)
19
21
22
20
Total Mobile Lines Quarterly Net Additions
912
406
428
482
Video (o)
Residential
13,298
12,010
12,072
12,023
Small Business (h)
503
514
533
538
Total Video Customers
13,801
12,524
12,605
12,561
Residential
1,288
(11)
49
(64)
Small Business (h)
(11)
(10)
(5)
(6)
Total Video Quarterly Net Additions
1,277
(21)
44
(70)
Voice
Residential
4,952
4,494
4,832
4,967
Small Business (h)
1,191
1,200
1,214
1,219
Total Voice Customers
6,143
5,694
6,046
6,186
See footnotes on page 11.
CHARTER COMMUNICATIONS, INC. AND SUBSIDIARIES
UNAUDITED SUMMARY OF OPERATING STATISTICS
(in thousands, except per customer and penetration data)
Approximate as of
September 30,
2026
June 30,
2026
December 31,
2025
September 30,
2025
Pro Forma (b)
Footprint
Estimated Passings (f)
70,706
70,313
69,662
69,156
Customer Relationships (g)
Residential
34,476
34,706
35,225
35,419
Small Business (h)
2,215
2,223
2,237
2,239
Total Customer Relationships
36,691
36,929
37,462
37,658
Residential
(230)
(282)
(194)
(152)
Small Business (h)
(8)
(8)
(2)
(2)
Total Customer Relationships Quarterly Net Additions
(238)
(290)
(196)
(154)
Total Customer Relationship Penetration of Estimated Passings (i)
51.9 %
52.5 %
53.8 %
54.5 %
Monthly Residential Revenue per Residential Customer (j)
$ 117.85
$ 118.40
$ 118.06
$ 119.71
Residential Customer Relationships Penetration (l)
One Product Penetration
50.8 %
51.1 %
51.6 %
52.0 %
Two Product Penetration
33.1 %
32.8 %
32.3 %
31.9 %
Three or More Product Penetration
16.2 %
16.1 %
16.1 %
16.0 %
Connectivity (m)
Residential
33,294
33,484
33,924
34,084
Small Business (h)
2,064
2,069
2,077
2,077
Total Connectivity Customers
35,358
35,553
36,001
36,161
Residential
(190)
(241)
(160)
(107)
Small Business (h)
(5)
(5)
—
1
Total Connectivity Quarterly Net Additions
(195)
(246)
(160)
(106)
Internet
Residential
32,289
32,517
32,987
33,173
Small Business (h)
2,025
2,030
2,039
2,039
Total Internet Customers
34,314
34,547
35,026
35,212
Residential
(228)
(269)
(186)
(170)
Small Business (h)
(5)
(6)
—
(1)
Total Internet Quarterly Net Additions
(233)
(275)
(186)
(171)
Mobile Lines (n)
Residential
12,992
12,503
11,718
11,282
Small Business (h)
460
441
396
374
Total Mobile Lines
13,452
12,944
12,114
11,656
Residential
489
418
436
494
Small Business (h)
19
21
22
20
Total Mobile Lines Quarterly Net Additions
508
439
458
514
Video (o)
Residential
13,298
13,364
13,528
13,519
Small Business (h)
503
514
533
538
Total Video Customers
13,801
13,878
14,061
14,057
Residential
(66)
(61)
9
(115)
Small Business (h)
(11)
(10)
(5)
(6)
Total Video Quarterly Net Additions
(77)
(71)
4
(121)
Voice
Residential
4,952
5,157
5,562
5,730
Small Business (h)
1,191
1,200
1,214
1,219
Total Voice Customers
6,143
6,357
6,776
6,949
See footnotes on page 11.
CHARTER COMMUNICATIONS, INC. AND SUBSIDIARIES
UNAUDITED CAPITAL EXPENDITURES
(dollars in millions)
Three Months Ended
September 30,
Nine Months Ended
September 30,
2026
2025
2026
2025
Actual
Actual
Actual
Actual
Customer premise equipment (p)
$ 670
$ 656
$ 1,992
$ 1,722
Scalable infrastructure (q)
341
425
987
1,089
Upgrade/rebuild (r)
741
484
2,073
1,336
Support capital (s)
549
449
1,433
1,234
Capital expenditures, excluding line extensions
2,301
2,014
6,485
5,381
Subsidized rural construction line extensions
292
580
1,108
1,590
Other line extensions
434
457
1,160
1,353
Total line extensions (t)
726
1,037
2,268
2,943
Total capital expenditures
$ 3,027
$ 3,051
$ 8,753
$ 8,324
Capital expenditures included in total related to:
Commercial services
$ 376
$ 336
$ 955
$ 933
Subsidized rural construction initiative (u)
$ 292
$ 582
$ 1,110
$ 1,595
Mobile
$ 73
$ 77
$ 202
$ 189
Transition (c)
$ 33
$ —
$ 70
$ —
Three Months Ended
September 30,
Nine Months Ended
September 30,
2026
2025
2026
2025
Pro Forma (b)
Pro Forma (b)
Pro Forma (b)
Pro Forma (b)
Customer premise equipment (p)
$ 705
$ 759
$ 2,171
$ 1,988
Scalable infrastructure (q)
385
560
1,188
1,464
Upgrade/rebuild (r)
757
520
2,148
1,438
Support capital (s)
581
549
1,597
1,558
Capital expenditures, excluding line extensions
2,428
2,388
7,104
6,448
Subsidized rural construction line extensions
292
580
1,108
1,590
Other line extensions
515
674
1,712
2,014
Total line extensions (t)
807
1,254
2,820
3,604
Total capital expenditures
$ 3,235
$ 3,642
$ 9,924
$ 10,052
Capital expenditures included in total related to:
Commercial services
$ 464
$ 479
$ 1,370
$ 1,362
Mobile
$ 76
$ 77
$ 209
$ 189
See footnotes on page 11.
CHARTER COMMUNICATIONS, INC. AND SUBSIDIARIES
FOOTNOTES
(a)
Adjusted EBITDA is defined as net income attributable to Charter shareholders plus net (income) loss attributable to noncontrolling interest, net interest expense, income taxes, depreciation and amortization, impairment of franchises, stock compensation expense, other (income) expenses, net and other operating (income) expenses, net such as restructuring costs, special charges, merger and acquisition costs and (gain) loss on sale or retirement of assets. As such, it eliminates the significant non-cash depreciation and amortization expense that results from the capital-intensive nature of our businesses as well as other non-cash or special items, and is unaffected by our capital structure or investment activities. Free cash flow is defined as net cash flows from operating activities, less capital expenditures and changes in accrued expenses related to capital expenditures.
(b)
Pro forma results reflect the acquisition of Cox Communications as if it occurred as of the earliest period presented.
(c)
Transition represents incremental costs incurred to prepare for the integration of Cox Communications’ operations and to bring systems and processes into a uniform operating structure.
(d)
Other expense excludes stock compensation expense. Total operating costs and expenses excludes stock compensation expense, depreciation and amortization and other operating (income) expenses, net.
(e)
We calculate the aging of customer accounts based on the monthly billing cycle for each account in accordance with our collection policies. On that basis, at September 30, 2026, June 30, 2026, December 31, 2025 and September 30, 2025, customers included approximately 101,800, 84,000, 82,300 and 87,100 customers, respectively, whose accounts were over 60 days past due, approximately 11,700, 10,100, 9,700 and 10,500 customers, respectively, whose accounts were over 90 days past due and approximately 17,700, 13,400, 13,600 and 13,200 customers, respectively, whose accounts were over 120 days past due. Past due accounts for periods prior to September 30, 2026 are for legacy Charter only.
(f)
Legacy Charter passings represent an estimate of the number of units passed by legacy Charter’s cable distribution network in areas where the indicated service is offered, such as single-family homes, apartment and condominium units, as well as small business and mid-market & large business sites. Legacy Cox Communications passings are residential only and represent an estimate of the number of units passed by legacy Cox Communications’ cable distribution network in areas where the indicated service is offered, including single-family homes and apartment and condominium units. These estimates are based on the information currently available and are updated for all periods presented as new information becomes available.
(g)
Customer relationships include the number of customers that receive one or more levels of service, encompassing Internet, mobile, video and voice services, without regard to which service(s) such customers receive. Customers who reside in residential multiple dwelling units (“MDUs”) and that are billed under bulk contracts are counted based on the number of billed units within each bulk MDU. Total customer relationships exclude legacy Charter mid-market & large business customer relationships and legacy Cox Communications business customers.
(h)
Small business and mid-market & large customer statistics reflect data for legacy Charter customers only.
(i)
Penetration represents customer relationships as a percentage of the applicable estimated passings.
(j)
Monthly residential revenue per residential customer is calculated as total residential quarterly revenue divided by three divided by average residential customer relationships during the respective quarter.
(k)
Monthly small business revenue per small business customer is calculated as total small business quarterly revenue divided by three divided by average small business customer relationships during the respective quarter.
(l)
One product, two product and three or more product penetration represents the number of residential customers that subscribe to one product, two products or three or more products, respectively, as a percentage of residential customer relationships.
(m)
Connectivity customers represent all customers receiving our Internet and/or mobile connectivity services.
(n)
Mobile lines include phones and tablets which require one of our standard rate plans (e.g., “Unlimited” or “By the Gig”). Mobile lines exclude wearables and other devices that do not require standard phone rate plans.
(o)
Video customers only include customers that purchase traditional or streaming linear video packages and exclude customers that only purchase streaming applications.
(p)
Customer premise equipment includes equipment and devices located at the customer’s premise used to deliver our Internet, video and voice services (e.g., modems, routers and set-top boxes), as well as installation costs.
(q)
Scalable infrastructure includes costs, not related to customer premise equipment or our network, to secure growth of new customers or provide service enhancements (e.g., headend equipment).
(r)
Upgrade/rebuild includes costs to modify or replace existing fiber/coaxial cable networks, including our network evolution initiative.
(s)
Support capital includes costs associated with the replacement or enhancement of non-network assets (e.g., back-office systems, non-network equipment, land and buildings, vehicles, tools and test equipment).
(t)
Line extensions include network costs associated with entering new service areas (e.g., fiber/coaxial cable, amplifiers, electronic equipment, make-ready and design engineering).
(u)
The subsidized rural construction initiative subcategory includes projects for which we are receiving subsidies from federal, state and local governments, excluding customer premise equipment and installation.
View original content to download multimedia:https://www.prnewswire.com/news-releases/charter-announces-third-quarter-2026-results-and-launches-new-operating-model-302931669.html
SOURCE Charter Communications, Inc.

You may like

— Yancheng Radio and Television Releases the Six‑Episode Micro‑documentary Homeland on the Tidal Flats
YANCHENG, China, Nov. 12, 2026 /PRNewswire/ — Ten thousand years ago, this land was nothing but sea. Today, 520,000 hectares of wetlands have risen from the tides, providing shelter for more than 4,700 species of life, where 467 kinds of birds arrive as promised. This land born out of the ocean holds an entire vibrant world.
Along China’s eastern coast stretches a 582‑kilometer coastline. Yancheng, home to 6.7 million people, lies next to one of the most densely populated regions on Earth, yet it has reserved vast “undeveloped” spaces for nature. Nearly one‑third of the world’s spoon‑billed sandpipers stop here to refuel; the world’s largest wild elk population thrives here; and four out of every ten offshore wind turbines worldwide are manufactured right here. At China’s first coastal World Natural Heritage Site — Yancheng — protection does not mean sealing nature off, nor does development mean pushing the wetlands aside. Instead, the city chooses to live in harmony with nature and grow along its rhythms: leaving ample room for nature amid development, and building better lives while safeguarding the ecosystem.
The six‑episode eco‑humanistic micro‑documentary Homeland on the Tidal Flats uses the camera as a pen to write a love letter between the sea and the land. Episode One, The Tidal Forest, reveals the intricate, hidden web of life in the intertidal zones. Episode Two, Return to the Wild, chronicles the rebirth of the elk population from just 39 to over 8,800. Episode Three, Beneath the Wings, records the visits of spoon‑billed sandpipers and red‑crowned cranes. Episode Four, New Life on Salty Soil, shows how rice waves and green granaries emerge from saline‑alkali soil. Episode Five, Light on the Wind, explores the pulse of offshore wind power and the zero‑carbon city. Episode Six, Wetland Life, captures the everyday rhythm of a city breathing in tune with its wetlands.
Prioritizing ecology and pursuing green development is the answer this beautiful city of harmonious coexistence between humanity and nature has written for Chinese‑style modernization.
View original content to download multimedia:https://www.prnewswire.com/news-releases/cctv-from-the-sea-toward-the-future-302937519.html
SOURCE CCTV+
Technology
Over 100 Delegates and 16 Startups: Taiwan Sends Largest-Ever Fintech Delegation to SFF 2026 as FinTechSpace Debuts “Taiwan Fintech Fleet” Collaboration Model
Published
7 minutes agoon
November 12, 2026By
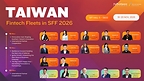
TAIPEI, Nov. 12, 2026 /PRNewswire/ — FinTechSpace, Taiwan’s premier one-stop fintech innovation acceleration hub – guided by the Financial Supervisory Commission (FSC) and founded by the Taiwan Financial Services Roundtable (TFSR) — is making its eighth consecutive appearance at the Singapore FinTech Festival (SFF). This year, FinTechSpace has mobilized innovation energy from both northern and southern Taiwan to curate the island’s largest-ever delegation, bringing over 100 fintech leaders, representatives, and 16 selected startups at the Taiwan Pavilion (Booth #5B33, Hall 5).
The Taiwan Pavilion showcases 16 international pitch sessions anchored around three core pillars: Resilience Forward: Operational Defense & Compliance; New Asset Horizons: Digital & Sustainable Finance; and Ignite Growth: Enterprise & Integrated Solutions. Crucially, FinTechSpace is debuting its groundbreaking “Theme-Based Fleet Pilot Program,” an initiative designed to integrate multi-team technologies and services to capitalize on complementary strengths, demonstrating the versatility, depth, and international competitiveness of Taiwan’s fintech ecosystem. The delegation will also host two high-level international networking events to deepen cross-border collaboration and unlock commercial opportunities.
Maiden Flagship Initiative: “Trustworthy FinTech” Fleet Hits the Global Stage
The newly launched “Taiwan Fintech Fleet” serves as a collaborative mechanism that connects the specialized capabilities of different startups into cohesive, scenario-based enterprise solutions. By replacing standalone tools with integrated offerings, the fleet model enables international financial institutions and enterprise clients to seamlessly adopt multi-faceted services that directly address operational pain points.
The inaugural rollout focuses on “Trust in FinTech,” bringing together six FinTechSpace portfolio companies – IHH, TOPPAN Security, KDAN, AIFT, FANO, and wiAdvance – to form two strategic theme fleets: “Digital Trust Chain” and “Trustworthy AI Guardrails”. The initiative propels startups to transition from “single-point services” to “full-scenario application” solutions, while taking a “fleet goes global” model to lead teams in jointly expanding into international markets and demonstrating the integration and collaborative strength driving Taiwan’s fintech industry.
Two Signature Events: Canada Meets Taiwan Forum and Taiwan–Korea Happy Hour Deepen Global Ties
During SFF, the Taiwan Pavilion will host “Canada Meets Taiwan: AI, Fintech, and New Opportunities for Financial Innovation” on Wednesday, November 18, 2026, from 2:30 to 3:15 PM (Singapore time). The session brings together government, industry, and academic representatives from Taiwan and Canada to discuss how artificial intelligence is reshaping fintech innovation, and to exchange insights on ecosystem development and collaboration opportunities, further strengthening bilateral fintech ties.
The Taiwan Pavilion is also teaming up with the Korea Pavilion to host a “Happy Hour” networking mixer, featuring Taiwanese and Korean snacks in a relaxed, social setting. The event is designed to spark connections between fintech startups, financial institutions, and industry partners from both countries, opening the door to future technical collaboration and market expansion.
An Open Invitation: Join Taiwan in Building the Next Wave of FinTech Opportunity
FinTechSpace warmly invites financial institutions, investors, and industry partners from around the world to visit the Taiwan Pavilion (Booth #5B33, Hall 5) during SFF, November 18–20, 2026, to engage with participating teams and explore opportunities for technical collaboration, business partnerships, and investment.
About FinTechSpace
Established in 2018, FinTechSpace is Taiwan’s first one-stop fintech innovation acceleration hub. Guided by the Financial Supervisory Commission (FSC) and initiated by the Taiwan Financial Services Roundtable (TFSR), the program is operated by the Institute for Information Industry (III). FinTechSpace is dedicated to creating a co-creation ecosystem that fosters FinTech development by integrating physical space, mentorship, and technical resources. It aims to drive FinTech innovation in Taiwan and promote international collaboration. For more information, please visit: www.fintechspace.com.tw.
2026 Taiwan Pavilion Exhibitor List
FinTechSpace (Taipei)
Resilience Forward: Operational Defense & Compliance
CoCoTree
Technology
CoCoTree Technology provides a nature-risk and TNFD-aligned decision platform that helps financial institutions and enterprises assess the nature sensitivity, biodiversity exposure,
and environmental risk of their operating sites and supply chains. The platform turns these insights into risk scores, monitoring alerts, and compliance summaries, supporting credit
underwriting, post-loan monitoring, supply chain engagement, and ESG/TNFD disclosure.
HiTRUST
HiTRUST is a fintech company specializing in digital security, identity verification, and fraud prevention that help financial institutions strengthen transaction security while improving
the user experience. Headquartered in Taiwan with seven offices worldwide, HiTRUST serves more than 10,000 institutions globally. In 2025, the company received a government
grant for Digital Service Innovation and won gold at the Ministry of Economic Affairs’ Smart Innovation Award.
IHH Co., Ltd.
IHH is dedicated to building “secure, anti-counterfeiting, and highly flexible commercial video solutions.” Providing enterprises with a “secure and trusted mechanism to seamlessly
leverage integrated AI capabilities before, during, and after video conferencing to conduct business, yielding highly non-repudiable results.”
IHH ensures every interaction is secure and trustworthy and generates highly non-repudiable digital evidence. Its solutions have been successfully deployed by several major,
market-leading enterprises.
TOPPAN
Security Co.,
Ltd.
TOPPAN Security focuses on advanced digital identity and authentication solutions, offering a one-stop solution spanning eKYC facial recognition, SoftToken, multi-factor authentication
(MFA), and device rebinding to help financial institutions strengthen the security of their digital services. Founded in 2013, the company joined the TOPPAN Group in 2020 and has been
expanding into global markets under the TOPPAN Security brand since 2025.
Woodpecker
Technology
Inc.
Woodpecker Technology specializes in enterprise security monitoring, threat detection, and incident response. Its flagship platform, Woodpecker XVR, delivers a unified SOC view
by integrating data from endpoints, networks, security logs, and user activities. Combined with an on-premises AI security assistant, the platform accelerates incident investigation,
improves alert prioritization, and enables more effective response while ensuring that sensitive data remains fully under the customer’s control. Woodpecker serves financial institutions,
government agencies, critical infrastructure operators, and high-tech manufacturers through partnerships with MDR providers, MSSPs, and system integrators.
Ignite Growth: Enterprise & Integrated Solutions
HOYA BIT
Digital
Technology
HOYA BIT Digital Asset Exchange has secured business compliance approvals from the Taiwan FSC as an exchanger, trading platform, transferor, and custodian, while co-creating
a 24/7 fiat exchange withdrawal service with Taishin Bank and becoming the world’s first ISO 14068-1 carbon-neutral exchange. In partnership with Taishin Bank, it offers round-the-
clock fiat withdrawal services and is the world’s first ISO 14068-1 carbon-neutral certified exchange. Powered by Agentic AI trading technology, HOYA BIT offers virtual asset and
multi-strategy investment services, and its AI Native Exchange OS helps financial institutions and enterprises integrate virtual assets and stablecoin payments and settlement.
Light
Momentum
Technology
Founded in 2021, Light Momentum Technology (LMT) combines expertise in IC design, ICT, and finance to develop fintech, AIoT, and custom ASIC/SoC chip applications, delivering
financial AI and high-frequency trading solutions. LMT was named to EE Times’ Silicon 100 in both 2022 and 2023, established a subsidiary in the Czech Republic in 2024, and has
exhibited at the Singapore FinTech Festival for four consecutive years as it continues to expand into overseas markets and technical partnerships.
On-us Co.,
Ltd.
On-us combines AI with years of accumulated consumer-engagement data through its Smart E-Voucher and On-us Intelligence platforms, turning behavioral signals from how consumers
claim, engage with, and redeem offers into actionable business insights. This helps enterprises optimize membership management, customer acquisition, loyalty programs, and marketing
performance, driving greater customer engagement value and revenue growth.
ThinkCloud
Technology
ThinkCloud Technology specializes in digital identity verification and e-signature solutions. Its flagship innovation, SelfieSign, utilizes patented SVS (Signing Video Stream) technology to
capture real-time video and audio recording during the signing process, timestamps, and verification data in compliance with the EU’s XAdES electronic document standard. ThinkCloud
also offers eStamp digital seals and FaceOTP AI liveness detection. The platform processes more than 3 million signatures a month and holds a 90% share of Taiwan’s medical e-signature
market.
TradingValley
Co., Ltd.
One of Taiwan’s earliest robo-advisory fintech, TradingValley helps financial institutions build digital wealth-management services and, after obtaining a U.S. investment advisor license,
launched its own B2C business. In 2025, the company introduced WinwinGPT, a personalized AI investment assistant that has been a finalist in multiple international fintech competitions
and has been successfully deployed at a major domestic financial holding company to boost the productivity of relationship managers and investment research teams.
Vulcan
Vulcan is an international AI security brand focused on generative and agentic AI security, providing AI red-teaming and real-time runtime protection to help enterprises identify risks
such as prompt injection and data leakage. Vulcan has expanded across Taiwan, Hong Kong, Singapore, Thailand, and the Middle East, serving 10+ major domestic and international
commercial banks and financial holding companies, Global high-tech manufacturers, and government agencies. Its solutions are recognized in the OWASP Agentic AI Security Landscape
and hold Panel Tester status with Singapore’s AI Verify Foundation, helping financial, insurance, manufacturing, and government organizations build trustworthy, governable, compliance-
ready AI environments.
FINNOVATION HUB (Kaohsiung)
New Asset Horizons: Digital & Sustainable Finance
AI PASS LINE
Founded in 2024, AI Pass Line focuses on AI, avatars, voice tech, and AR/MR/XR applications. Built on an “AI × MR” core, the company delivers comprehensive smart solutions spanning
healthcare, education, customer service, AI agents, and digital-twin training. Leveraging AI knowledge management, its enterprise AI Agent platform, and Azure cloud technology, AI Pass
Line helps clients integrate systems and data to boost operational efficiency. With proven experience across medical, financial, retail, and education sectors, it delivers efficient, secure,
and human-centric intelligent services.
CyCatena
Technology
CyCatena Technology provides secure digital asset infrastructure for financial institutions and enterprises. Its core product, CyCatena Vault, enables secure and self-controlled management
of digital assets and stablecoins. With HSM-based key protection, multi-level approval, access control, transaction risk monitoring, and comprehensive audit trails, CyCatena Vault meets
institutional security and compliance requirements. Supporting both on-premises and private cloud deployment, it allows institutions to retain control of their private keys, transaction data,
and infrastructure while integrating seamlessly with existing banking and enterprise systems.
Eureka
FinTech TW
Limited
Eureka aims to be a pioneer in providing innovative market & credit analysis, KYC and ESG solutions to manufacturers and financial institutions across Asia via its comprehensive AI
services platform and bespoke consulting services. Eureka’s comprehensive platform integrates into one single platform big data, vendor databases and customers’ internal data by
utilizing AI and graph technologies. Eureka’s AI services platform provides users with information including market analysis, industry analysis, meeting minutes, credit report, ESG report
and compliance & sanction report systems to assist them in analyzing supply chains, green energy and business relationships.
Root
Intelligent
Tech
Root Intelligent Tech is dedicated to making professional financial planning more accessible through AI. Its services include intelligent financial health assessments, wealth succession and
estate and gift tax planning, AI-powered advisory tools for financial professionals, and green consumption applications. By combining data visualization, scenario simulation, and professional
knowledge retrieval, Root Intelligent Tech helps financial institutions, advisors, and individuals identify financial risks, evaluate planning options, and make informed decisions.
Synstream
Pte Limited
Shinchuan Technology offers an enterprise-grade AI data orchestration platform for financial institutions, enabling rapid AI adoption without replacing existing core systems. The platform
integrates data orchestration, AI vision computing, on-premises small language models (SLMs), and multimodal RAG technology to support KYC/AML compliance monitoring, automated
regulatory reporting, wealth management, and enterprise AI agents, all backed by bank-grade governance, access control, and auditability to improve operational efficiency and data security.
Synstream is an enterprise AI data orchestration platform designed for financial institutions, enabling rapid AI adoption without replacing legacy systems. Powered by three core engines –
Data Orchestration, Visual Intelligence, and Enterprise On-Prem SLM & RAG – Synstream delivers specialized FinTech modules including KYC/AML automation, regulatory reporting,
and wealth management modernization. Featuring banking-grade data governance, full auditability, and hybrid/on-prem deployment, Synstream reduces false positives by ~85% and cuts
case resolution times by ~90%.
View original content to download multimedia:https://www.prnewswire.com/apac/news-releases/over-100-delegates-and-16-startups-taiwan-sends-largest-ever-fintech-delegation-to-sff-2026-as-fintechspace-debuts-taiwan-fintech-fleet-collaboration-model-302937523.html
SOURCE FinTechSpace
Technology
IBM Announces Winner of Sports Tech Startup Prize Challenge at Web Summit Lisbon 2026
Published
7 minutes agoon
November 12, 2026By
LivXP has been selected from a global field of innovators advancing the future of sports through AI.
LISBON, Portugal, Nov. 12, 2026 /PRNewswire/ — IBM (NYSE: IBM) today announced LivXP as the winner of the IBM Sports Tech Startup Prize Challenge at Web Summit Lisbon, recognizing the company for its innovative use of agentic AI to transform how fans engage with their favorite teams, organizations, and leagues.
The challenge marks the culmination of the IBM Sports Tech Startup Challenge, a year-long global initiative created to identify and evaluate growth-stage startups building enterprise-ready technologies for sports organizations, teams, media companies, and fans. Launched at Web Summit Lisbon 2025, IBM has engaged founders through showcases at Web Summits in Vancouver, Rio de Janeiro, and Lisbon, alongside a16z Tech Weeks in New York and San Francisco, and in virtual forums. These showcase activities were designed to provide visibility and engagement opportunities and did not confer eligibility, ranking, priority, or advancement in the invitation-only Prize Challenge held this week. The invite-only challenge featured seven finalists selected from a broad field of sports technology innovators. Finalists pitched their solutions before a distinguished judging panel that included Sarah Meron, Chief Communications and Brand Officer, IBM; Marc Gené, Ferrari Ambassador, Scuderia Ferrari HP; Brad Smith, Headlines Anchor at CNN; and Frederico Gil, founder and CEO of FREDGIL Academy.
LivXP, a Swiss-American company accelerated at the Harvard Innovation Labs, is an AI-powered impulse commerce infrastructure for sports: auctions, experiences, and sponsor activations that land at the fan’s emotional high. From the Tour de Suisse to Boston College Athletics, federations, clubs, international events, and U.S. college sports programs use its white-label platform to reach fans in 150 countries.
“We were incredibly impressed by both the technical innovation and practical application of LivXp’s solution,” said IBM Chief Communications and Brand officer Sarah Meron. “At IBM, we’re always looking for new ways AI can help our clients create more engaging, personalized experiences, and we see exciting potential for technologies like this to enhance the work we do alongside our global sports and entertainment partners.”
Upon being announced the winner, LivXP CEO and Co-Founder Ashima Saxena stated, “Every emotional moment in sport revenue is waiting to happen, and AI finally lets sports organizations capture it at scale, without adding staff. We’re proud to have won the IBM Sports Tech Startup Challenge, and we look forward to working with IBM’s Sports & Entertainment Partnerships Team to bring impulse commerce to more clubs, sponsors, and fans worldwide.”
The Lisbon finale capped a year-long series of startup showcases and judging sessions bringing together influential voices from sports, media, and venture capital, including Maria Sharapova, and representatives from a16z, USTA Ventures, Sony Ventures, Comcast Ventures, Maple Leaf Sports & Entertainment (MLSE), FIFA, and Powerhouse Capital.
Finalists
The seven startups participating in the 2026 IBM Sports Tech Startup Prize Challenge were:
Fanory – Fan intelligence platform transforming live sports experiences into memories, assets, and behavioral data.Neuron Systems – Multi agent AI platform for live sports and entertainment that generates real-time commentary, insights, and content for sports fans and creators.LivXP – Fan engagement marketplace that connects sports fans with exclusive experiences, auctions, and interactions with teams, athletes, and sports organizations.PressBox – AI-powered content platform that enables sports leagues, teams, and media organizations to create and personalize content and marketing.NTangible – Verbal cognitive assessment platform that measures how athletes perform under pressure.Proximity Works Inc. – AI engineering company that builds real-time intelligence and fan engagement systems for sports, media, and entertainment organizations.Noiz – Sports-matching platform making it easier to find courts, try new sports, and build player connections.
The Prize Challenge Grand Prize includes up to $100,000 to support an eligible proof-of-concept project with IBM’s Sports and Entertainment Partnership Team, subject to separate review and agreement requirements, up to $20,000 in IBM credits to be applied toward services and technology, mentorship opportunities, and evaluation opportunities described in the Official Rules.
About the IBM Sports Tech Startup Challenge
Launched in partnership with Web Summit, the IBM Sports Tech Startup Challenge is a global initiative designed to spotlight startups applying AI and other emerging technologies to solve challenges across the sports industry. Building on IBM Ventures’ mission to connect cutting-edge innovation with enterprise clients, the Challenge extends this approach to IBM’s sports portfolio, using our sports partnerships as a proving ground to showcase technologies with real-world potential for both the sports landscape and broader business applications. The 2026 program included startup showcases at Web Summit Vancouver, Rio, and Lisbon, events during a16z Tech Weeks in New York and San Francisco, and in virtual forms, culminating with the invite-only Prize Challenge at Web Summit Lisbon. These showcase activities provided opportunities for visibility and engagement but did not confer eligibility, ranking, priority, or advancement in the Prize Challenge.
About IBM in Sports
For more than 30 years, IBM has partnered with some of the world’s most iconic sports organizations, including Wimbledon, the US Open, the Masters Tournament, Scuderia Ferrari HP, and UFC. Together, IBM and its partners create AI-powered experiences designed to deliver deeper insights, smarter engagement, and richer digital experiences for sports fans around the globe.
About IBM Ventures
As the corporate venture capital arm of IBM, IBM Ventures invests in startups across enterprise AI and quantum software. A strategic investor, IBM Ventures works closely with startups and founders to bring innovative technologies into IBM and help drive value for IBM clients. Through IBM’s technology, expertise and global client network, IBM Ventures helps portfolio companies build strategic relationships and accelerate their growth.
Media Contact:
Rebeccah Propp
IBM
View original content to download multimedia:https://www.prnewswire.com/news-releases/ibm-announces-winner-of-sports-tech-startup-prize-challenge-at-web-summit-lisbon-2026-302937067.html
SOURCE IBM

CCTV+: From the Sea, Toward the Future

Over 100 Delegates and 16 Startups: Taiwan Sends Largest-Ever Fintech Delegation to SFF 2026 as FinTechSpace Debuts “Taiwan Fintech Fleet” Collaboration Model

IBM Announces Winner of Sports Tech Startup Prize Challenge at Web Summit Lisbon 2026

Send Rakhi to UK swiftly with UK Gifts Portal

Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

Nullmax and Renesas Forge Strategic Partnership to Deliver Competitive ADAS Solutions for the Global Market

Why You Should Build on #NEAR – Co-founder Illia Polosukhin at CV Labs
Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

NEAR End of Year Town Hall 2021: The Open Web World, MetaBUILD 2 Hackathon and 2021 recap
Trending
-

 Coin Market5 days ago
Suspicious prediction market activity seen before election poll release: NYT
-

 Technology3 days ago
Global Validation First: How CrossHub Is Building Trust to Scale Overseas
-
 Coin Market5 days ago
US sanctions Canadian money-exchange firms over Iran ties
-
 Near Videos5 days ago
Illia Polosukhin: Why AI Agents Need Verifiability | Token2049
-

 Coin Market3 days ago
Vitalik ‘pivots’ ETH to store of value, crypto suffers after US midterms: Hodler’s Digest
-
 Technology5 days ago
7th World Media Summit opens in Beijing
-
 Coin Market3 days ago
tBTC bridge partially resumes as $120M Aave reserve remains frozen
-
 Technology2 days ago
LG Innotek Shines Again in Vehicle Lighting with Third Consecutive CES Innovation Award