
Technology
Amcor reports fiscal 2024 results and provides outlook for fiscal 2025

Published
2 years agoon
By

June 2024 Quarter Highlights:
Another sequential improvement in volumes and earnings growth;Net sales of $3,535 million; volumes returned to growth, up 1%;GAAP net income of $257 million; GAAP diluted earnings per share (EPS) of 17.8 cps;Adjusted EBIT of $454 million, up 4% on a comparable constant currency basis; andAdjusted EPS of 21.1 cps, up 9% on a comparable constant currency basis.
Fiscal 2024 Full Year Highlights:
Net sales of $13,640 million;GAAP Net Income of $730 million; GAAP diluted EPS of 50.5 cps;Adjusted EPS of 70.2 cps and Adjusted EBIT of $1,560 million;Adjusted Free Cash Flow of $952 million, up >$100 million or 12% on last year; andCash returns to shareholders of approximately $750 million: annual dividend increased to 50.0 cents per share and $30 million of shares repurchased.
Fiscal 2025 outlook:
Adjusted EPS of 72-76 cents per share; Adjusted Free Cash Flow of $900-1,000 million.
ZURICH, Aug. 15, 2024 /PRNewswire/ —
Strong 4Q financial performance ahead of expectations with volumes returning to growth
Amcor expects strong growth from the underlying business to continue in FY25
Amcor Interim CEO Peter Konieczny said: “Amcor finished fiscal 2024 strongly, as the underlying business delivered another sequential improvement in volume and earnings growth, with fourth quarter adjusted EPS up 9%, ahead of the expectations we set out in April. Volumes returned to year on year growth in the quarter as customer demand improved and our teams maintained their outstanding focus on managing costs, driving strong margin expansion. Annual adjusted free cash flow was at the top end of our guidance range and up 12% on last year.
In fiscal 2025, we expect volumes and earnings will grow and adjusted free cash flow will remain strong. Importantly, combined with our historical average dividend yield, growth at the midpoint of our EPS guidance range results in total value creation in-line with our shareholder value creation model 10-15% range.
We remain confident in our capital allocation framework and strategy for long term growth. We believe our underlying business and market positions are strong and we will continue to invest for organic growth, pursue acquisitions or repurchase shares and return cash to shareholders through a compelling and growing dividend.”
Key Financials(1)
Twelve Months Ended June 30,
GAAP results
2023 $ million
2024 $ million
Net sales
14,694
13,640
Net income
1,048
730
EPS (diluted US cents)
70.5
50.5
Twelve Months Ended June 30,
Reported ∆%
Comparable
constant
currency ∆%
Adjusted non-GAAP results
2023 $ million
2024 $ million
Net sales
14,694
13,640
(7)
(6)
EBITDA
2,018
1,962
(3)
(1)
EBIT
1,608
1,560
(3)
(1)
Net income
1,089
1,015
(7)
(5)
EPS (diluted US cents)
73.3
70.2
(4)
(2)
Free Cash Flow
848
952
(1) Adjusted non-GAAP results exclude items which are not considered representative of ongoing operations. Comparable constant currency ∆% excludes the impact of movements in foreign exchange rates and items affecting comparability. Further details related to non-GAAP measures and reconciliations to GAAP measures can be found under “Presentation of non-GAAP information” in this release.
Note: All amounts referenced throughout this document are in US dollars unless otherwise indicated and numbers may not add up precisely to the totals provided due to rounding.
Shareholder returns
Capital allocation
Amcor generates significant annual cash flow and is committed to an investment grade credit rating. We believe that the Company’s strong annual cash flow and balance sheet provide capacity to reinvest in the business for organic growth, pursue acquisitions or share repurchases and return cash to shareholders through a compelling and growing dividend.
During fiscal 2024, the Company returned approximately $750 million to shareholders through cash dividends and share repurchases.
Dividend
The Amcor Board of Directors today declared a quarterly cash dividend of 12.5 cents per share (compared with 12.25 cents per share in the same quarter last year). Combined with the last three quarterly dividends, this increases the annual dividend for fiscal 2024 to 50.0 cents per share. The quarterly dividend declared today will be paid in US dollars to holders of Amcor’s ordinary shares trading on the NYSE. Holders of CDIs trading on the ASX will receive an unfranked dividend of 19.01 Australian cents per share, which reflects the quarterly dividend of 12.5 cents per share converted at an average AUD:USD exchange rate of 0.6574 over the five trading days ended August 13, 2024.
The ex-dividend date will be September 5, 2024, the record date will be September 6, 2024, and the payment date will be September 26, 2024.
Share repurchases
Amcor repurchased approximately 3 million shares during fiscal 2024 for a total cost of approximately $30 million.
Financial results – twelve months ended June 30, 2024
Segment Information
Twelve Months Ended June 30, 2023
Twelve Months Ended June 30, 2024
Adjusted non-GAAP
results
Net sales
$ million
EBIT
$ million
EBIT /
Sales %
EBIT / Average
funds employed
%(1)
Net sales
$ million
EBIT
$ million
EBIT /
Sales %
EBIT / Average
funds employed
%(1)
Flexibles
11,154
1,429
12.8
10,332
1,395
13.5
Rigid Packaging
3,540
265
7.5
3,308
259
7.8
Other(2)
—
(86)
—
(94)
Total Amcor
14,694
1,608
10.9
15.4
13,640
1,560
11.4
14.9
(1) Return on average funds employed includes shareholders’ equity and net debt, calculated using a four quarter average and last twelve months adjusted EBIT.
(2) Represents corporate expenses.
Twelve months ended June 30, 2024:
Net sales of $13,640 million were 7% lower than last year on a reported basis, including a favorable impact of approximately 1% related to movements in foreign exchange rates, an unfavorable impact of approximately 1% related to items affecting comparability, and an unfavorable impact of 1% related to the pass through of lower raw material costs of approximately $220 million.
Net sales on a comparable constant currency basis were 6% lower than last year reflecting approximately 5% lower volumes and an unfavorable price/mix impact of approximately 1%.
Adjusted EBIT of $1,560 million was 1% lower than last year on a comparable constant currency basis, reflecting lower volumes and unfavorable impacts from price/mix, partly offset by strong cost performance.
June 2024 quarter result:
Net sales of $3,535 million were 4% lower than last year on a reported basis, including an unfavorable impact of 2% related to the pass through of lower raw material costs of approximately $70 million. Movements in foreign exchange rates had an unfavorable impact on net sales of less than 1% for the quarter.
Volumes returned to growth in the June quarter, up approximately 1% compared with the prior year which represents a sequential improvement of 5 percentage points. As expected, volumes remained soft in healthcare categories and in the North America beverage business through the June quarter, unfavorably impacting overall volumes by approximately 2%. Price/mix had an unfavorable impact of approximately 3% due to lower volumes in high value healthcare categories. On a comparable constant currency basis, net sales were 1% lower than last year.
Adjusted EBIT of $454 million was approximately 4% higher than last year on a comparable constant currency basis. Unfavorable impacts from price/mix were more than offset by higher volumes, benefits from restructuring initiatives and continued outstanding cost performance which resulted in strong earnings leverage.
Flexibles segment – June 2024 quarter
Three Months Ended June 30,
Reported
∆%
Comparable
constant
currency ∆%
2023 $ million
2024 $ million
Net sales
2,777
2,686
(3)
(1)
Adjusted EBIT
387
403
4
5
Adjusted EBIT / Sales %
13.9
15.0
Net sales of $2,686 million were 3% lower than last year on a reported basis, including an unfavorable impact of approximately 1% related to movements in foreign exchange rates and an unfavorable impact of 1% related to the pass through of lower raw material costs of approximately $40 million.
Volumes returned to growth in the June quarter, up approximately 3% compared with the prior year, which is a sequential improvement of 5 percentage points. Price/mix had an unfavorable impact of approximately 4%, primarily due to lower volumes in high value healthcare categories. On a comparable constant currency basis, net sales were 1% lower than last year.
Volumes were higher than the same quarter last year across most geographies and in several end markets including home & personal care, meat, cheese and unconverted film and foil. As expected, destocking continued in healthcare categories and volumes remained soft, unfavorably impacting overall segment volumes for the quarter by approximately 2%.
Adjusted EBIT of $403 million was 5% higher than last year on a comparable constant currency basis. The impact of higher volumes, benefits from restructuring initiatives and strong cost performance was partly offset by unfavorable price/mix. Earnings leverage was strong, and adjusted EBIT margin of 15.0% was 110 basis points higher than the June quarter last year.
Flexibles segment – Fiscal 2024
Twelve Months Ended June 30,
Reported
∆%
Comparable
constant
currency ∆%
2023 $ million
2024 $ million
Net sales
11,154
10,332
(7)
(6)
Adjusted EBIT
1,429
1,395
(2)
—
Adjusted EBIT / Sales %
12.8
13.5
Net sales of $10,332 million were 7% lower than last year on a reported basis, including a favorable impact of approximately 1% related to movements in foreign exchange rates, an unfavorable impact of approximately 1% related to items affecting comparability and an unfavorable impact of 1% related to the pass through of lower raw material costs of approximately $180 million. On a comparable constant currency basis, net sales were 6% lower, reflecting an unfavorable price/mix impact of approximately 2% and lower volumes of approximately 4%. Volume weakness largely reflects lower market and customer demand and destocking particularly through the first half of the year. The trajectory of volumes improved significantly through the second half of the year, returning to year over year growth in the June quarter.
In North America, net sales declined at mid to high single digit rates driven by lower volumes and an unfavorable price/mix impact. Volumes were higher in the condiments, snacks and cheese categories and this was more than offset by lower volumes in categories including healthcare, meat and liquid beverage.
In Europe, net sales declined at high single digit rates primarily driven by lower volumes. Volumes were lower mainly in the healthcare, snacks & confectionary, coffee and yoghurt end markets.
Across the Asian region, volumes were higher than the prior year with growth in Thailand, India and China, partly offset by lower volumes in the South East Asian healthcare business. In Latin America, net sales declined at mid single digit rates, driven by lower volumes mainly in Chile and Mexico, partly offset by growth in Brazil.
Adjusted EBIT of $1,395 million was in line with last year on a comparable constant currency basis, reflecting lower volumes and unfavorable impacts from price/mix, partly offset by benefits from restructuring initiatives and ongoing actions taken to lower costs and increase productivity. Adjusted EBIT margin of 13.5% was higher than the prior year notwithstanding weaker volumes and a 30 basis point unfavorable impact compared to the prior year related to the sale of the Russian business in December 2022.
Rigid Packaging segment – June 2024 quarter
Three Months Ended June 30,
Reported
∆%
Comparable
constant
currency ∆%
2023 $ million
2024 $ million
Net sales
897
849
(5)
(2)
Adjusted EBIT
73
75
3
2
Adjusted EBIT / Sales %
8.1
8.8
Net sales of $849 million were 5% lower than last year on a reported basis, including an unfavorable impact of 4% related to the pass through of lower raw material costs of approximately $30 million. Movements in foreign exchange rates had a favorable impact on net sales of less than 1% for the quarter.
On a comparable constant currency basis, net sales were 2% lower than last year with volumes approximately 5% lower, partly offset by favorable price/mix benefits of approximately 3%.
In North America, overall beverage volumes improved sequentially for the second consecutive quarter. While consumer and customer demand in key categories improved sequentially, overall volumes were 8% lower as a result of continued soft demand which was expected. Hot fill beverage container volumes were 9% lower than the same quarter last year, which represents a 9 percentage point improvement compared with the March 2024 quarter.
In Latin America, volumes were 3% higher than the same quarter last year, reflecting new business wins in Brazil, Colombia and Central America, partly offset by weaker demand in Argentina. Specialty Container volumes were lower than last year.
Adjusted EBIT of $75 million was 2% higher than last year on a comparable constant currency basis, with the impact of lower volumes more than offset by favorable price/mix, benefits from restructuring initiatives and strong cost performance which drove solid earnings leverage.
Rigid Packaging segment – Fiscal 2024
Twelve Months Ended June 30,
Reported
∆%
Comparable
constant
currency ∆%
2023 $ million
2024 $ million
Net sales
3,540
3,308
(7)
(6)
Adjusted EBIT
265
259
(2)
(4)
Adjusted EBIT / Sales %
7.5
7.8
Net sales of $3,308 million were 7% lower than last year on a reported basis, including an unfavorable impact of 1% related to the pass through of lower raw material costs of approximately $40 million. Movements in foreign exchange rates had a favorable impact on net sales of less than 1%. On a comparable constant currency basis, net sales were 6% lower than last year, reflecting price/mix benefits of approximately 2% and volumes were approximately 8% lower than last year.
In North America, overall beverage volumes were 12% lower than last year, including a reduction in hot fill beverage container volumes of approximately 13%. This mainly reflects a combination of lower consumer and customer demand, as well as significant destocking particularly through the first half of the year.
In Latin America, volumes were 3% higher than last year, reflecting new business wins with a broad range of customers in Brazil and Colombia, partly offset by lower volumes in Argentina. Specialty Container volumes were lower than last year.
Adjusted EBIT of $259 million was 4% lower than last year on a comparable constant currency basis, reflecting lower volumes partly offset by price/mix benefits and favorable cost performance.
Net interest and income tax expense
For the year ended June 30, 2024, net interest expense of $310 million was $51 million higher than last year, reflecting higher interest rates. GAAP income tax expense was $163 million compared with $193 million last year. Adjusted tax expense for the year ended June 30, 2024 was $225 million compared with $250 million last year. Adjusted tax expense for the year ended June 30, 2024 represents an effective tax rate of 18.0%, compared with 18.5% in the prior year.
Adjusted Free Cash Flow
For the year ended June 30, 2024, adjusted free cash inflow was $952 million, at the top end of the Company’s guidance range and up $104 million, or 12% compared with the prior year.
Net debt was $6,111 million at June 30, 2024. Leverage, measured as net debt divided by adjusted trailing twelve month EBITDA, was 3.1 times and in line with our expectations.
Fiscal 2025 Guidance
For the twelve month period ending June 30, 2025, the Company expects:
Adjusted EPS of approximately 72 to 76 cents per share, which represents comparable constant currency growth of 3% to 8% (includes approximately 4% headwind related to normalization of incentive compensation payments) compared with 70.2 cents per share in fiscal 2024.Assuming current exchange rates prevail through fiscal 2025, movements in exchange rates are not expected to have a material impact on reported EPS.Adjusted Free Cash Flow of approximately $900 million to $1,000 million.
Amcor’s guidance contemplates a range of factors which create a degree of uncertainty and complexity when estimating future financial results. Further information can be found under ‘Cautionary Statement Regarding Forward-Looking Statements’ in this release.
Conference Call
Amcor is hosting a conference call with investors and analysts to discuss these results on Thursday August 15, 2024 at 5:30pm US Eastern Daylight Time / Friday August 16, 2024 at 7:30am Australian Eastern Standard Time. Investors are invited to listen to a live webcast of the conference call at our website, www.amcor.com, in the “Investors” section.
Those wishing to access the call should use the following toll-free numbers, with the Conference ID : 9115937
USA: 800 715 9871 (toll free)USA: 646 307 1963 (local)Australia: 1800 519 630 (toll free), 02 9133 7103 (local)United Kingdom: 0800 358 0970 (toll free), 020 3433 3846 (local)Singapore: +65 3159 5133 (local)Hong Kong: +852 3002 3410 (local)
From all other countries, the call can be accessed by dialing +1 646 307 1963 (toll).
A replay of the webcast will also be available in the ‘Investors” section at www.amcor.com following the call.
About Amcor
Amcor is a global leader in developing and producing responsible packaging solutions across a variety of materials for food, beverage, pharmaceutical, medical, home and personal-care, and other products. Amcor works with leading companies around the world to protect products, differentiate brands, and improve supply chains. The Company offers a range of innovative, differentiating flexible and rigid packaging, specialty cartons, closures and services. The company is focused on making packaging that is increasingly recyclable, reusable, lighter weight and made using an increasing amount of recycled content. In fiscal year 2024, 41,000 Amcor people generated $13.6 billion in annual sales from operations that span 212 locations in 40 countries. NYSE: AMCR; ASX: AMC
www.amcor.com I LinkedIn I YouTube
Contact Information
Investors
Tracey Whitehead
Damien Bird
Damon Wright
Global Head of Investor Relations
Vice President Investor Relations Asia Pacific
Vice President Investor Relations North America
Amcor
Amcor
Amcor
+61 408 037 590
+61 481 900 499
+1 224 313 7141
Media – Australia
Media – Europe
Media – North America
James Strong
Ernesto Duran
Julie Liedtke
Managing Director
Head of Global Communications
Director, Media Relations
Sodali & Co
Amcor
Amcor
+61 448 881 174
+41 78 698 69 40
+1 847 204 2319
Amcor plc UK Establishment Address: 83 Tower Road North, Warmley, Bristol, England, BS30 8XP, United Kingdom
UK Overseas Company Number: BR020803
Registered Office: 3rd Floor, 44 Esplanade, St Helier, JE4 9WG, Jersey
Jersey Registered Company Number: 126984, Australian Registered Body Number (ARBN): 630 385 278
Cautionary Statement Regarding Forward-Looking Statements
This document contains certain statements that are “forward-looking statements” within the meaning of the safe harbor provisions of the U.S. Private Securities Litigation Reform Act of 1995. Forward-looking statements are generally identified with words like “believe,” “expect,” “target,” “project,” “may,” “could,” “would,” “approximately,” “possible,” “will,” “should,” “intend,” “plan,” “anticipate,” “commit,” “estimate,” “potential,” “ambitions,” “outlook,” or “continue,” the negative of these words, other terms of similar meaning, or the use of future dates. Such statements are based on the current expectations of the management of Amcor and are qualified by the inherent risks and uncertainties surrounding future expectations generally. Actual results could differ materially from those currently anticipated due to a number of risks and uncertainties. Neither Amcor nor any of its respective directors, executive officers, or advisors provide any representation, assurance, or guarantee that the occurrence of the events expressed or implied in any forward-looking statements will actually occur. Risks and uncertainties that could cause actual results to differ from expectations include, but are not limited to: changes in consumer demand patterns and customer requirements in numerous industries; the loss of key customers, a reduction in their production requirements or consolidation among key customers; significant competition in the industries and regions in which we operate; an inability to expand our current business effectively through either organic growth, including product innovation, investments or acquisitions; challenging global economic conditions, impacts of operating internationally; price fluctuations or shortages in the availability of raw materials, energy, and other inputs which could adversely affect our business; production, supply, and commercial risks, including counterparty credit risks, which may be exacerbated in times of economic volatility; pandemics, epidemics, or other disease outbreaks; an inability to attract, motivate and retain our skilled workforce and manage key transitions; labor disputes and an inability to renew collective bargaining agreements at acceptable terms; physical impact of climate change; cybersecurity risks, which could disrupt our operations or risk of loss of our sensitive business information; failures or disruptions in our information technology systems which could disrupt our operations, compromise customer, employee, supplier and other data; a significant increase in our indebtedness or a downgrade in our credit rating could reduce our operating flexibility and increase our borrowing costs and negatively affect our financial condition and results of operations; rising interest rates that increase our borrowing costs on our variable rate indebtedness and could have other negative impacts; foreign exchange rate risk; a significant write-down of goodwill and/or intangible assets; a failure to maintain an effective system of internal control over financial reporting; inability of our insurance policies, including our use of a captive insurance company, to provide adequate protection against all of the risks we face; an inability to defend our intellectual property rights or intellectual property infringement claims against us; litigation, including product liability claims or litigation related to Environmental, Social, and Governance (“ESG”) matters or regulatory developments; increasing scrutiny and changing expectations from investors, customers, suppliers and governments with respect to our ESG practices and commitments resulting in additional costs or exposure to additional risks; changing ESG disclosure regulations including climate-related rules; changing environmental, health, and safety laws; changes in tax laws or changes in our geographic mix of earnings; and other risks and uncertainties identified from time to time in Amcor’s filings with the U.S. Securities and Exchange Commission (the “SEC”), including without limitation, those described under Item 1A. “Risk Factors” of Amcor’s annual report on Form 10-K for the fiscal year ended June 30, 2023 and any subsequent quarterly reports on Form 10-Q. You can obtain copies of Amcor’s filings with the SEC for free at the SEC’s website (www.sec.gov). Forward-looking statements included herein are made only as of the date hereof and Amcor assumes no obligation, and disclaims any obligation to update any forward-looking statements, or any other information in this communication, as a result of new information, future developments or otherwise, or to correct any inaccuracies or omissions in them which become apparent, except as expressly required by law. All forward-looking statements in this communication are qualified in their entirety by this cautionary statement.
Presentation of non-GAAP information
Included in this release are measures of financial performance that are not calculated in accordance with U.S. GAAP. These measures include adjusted EBITDA and EBITDA (calculated as earnings before interest and tax and depreciation and amortization), adjusted EBIT and EBIT (calculated as earnings before interest and tax), adjusted net income, adjusted earnings per share, adjusted free cash flow and net debt. In arriving at these non-GAAP measures, we exclude items that either have a non-recurring impact on the income statement or which, in the judgment of our management, are items that, either as a result of their nature or size, could, were they not singled out, potentially cause investors to extrapolate future performance from an improper base. Note that while amortization of acquired intangible assets is excluded from non-GAAP adjusted financial measures, the revenue of the acquired entities and all other expenses unless otherwise stated, are reflected in our non-GAAP financial performance earnings measures. While not all inclusive, examples of these items include: material restructuring programs, including associated costs such as employee severance, pension and related benefits, impairment of property and equipment and other assets, accelerated depreciation, termination payments for contracts and leases, contractual obligations, and any other qualifying costs related to restructuring plans; material sales and earnings from disposed or ceased operations and any associated profit or loss on sale of businesses or subsidiaries; changes in the fair value of economic hedging instruments on commercial paper and contingent purchase consideration; significant pension settlements; impairments in goodwill and equity method investments; material acquisition compensation and transaction costs such as due diligence expenses, professional and legal fees, and integration costs; material purchase accounting adjustments for inventory; amortization of acquired intangible assets from business combination; gains or losses on significant property and divestitures and significant property and other impairments, net of insurance recovery; certain regulatory and legal matters; impacts from highly inflationary accounting; expenses related to the Company’s Chief Executive Officer transition; and impacts related to the Russia–Ukraine conflict.
Amcor also evaluates performance on a comparable constant currency basis, which measures financial results assuming constant foreign currency exchange rates used for translation based on the average rates in effect for the comparable prior year period. In order to compute comparable constant currency results, we multiply or divide, as appropriate, current-year U.S. dollar results by the current year average foreign exchange rates and then multiply or divide, as appropriate, those amounts by the prior-year average foreign exchange rates. We then adjust for other items affecting comparability. While not all inclusive, examples of items affecting comparability include the difference between sales or earnings in the current period and the prior period related to disposed, or ceased operations. Comparable constant currency net sales performance also excludes the impact from passing through movements in raw material costs.
Management has used and uses these measures internally for planning, forecasting and evaluating the performance of the Company’s reporting segments and certain of the measures are used as a component of Amcor’s Board of Directors’ measurement of Amcor’s performance for incentive compensation purposes. Amcor believes that these non-GAAP measures are useful to enable investors to perform comparisons of current and historical performance of the Company. For each of these non-GAAP financial measures, a reconciliation to the most directly comparable U.S. GAAP financial measure has been provided herein. These non-GAAP financial measures should not be construed as an alternative to results determined in accordance with U.S. GAAP. The Company provides guidance on a non-GAAP basis as we are unable to predict with reasonable certainty the ultimate outcome and timing of certain significant forward-looking items without unreasonable effort. These items include but are not limited to the impact of foreign exchange translation, restructuring program costs, asset impairments, possible gains and losses on the sale of assets, and certain tax related events. These items are uncertain, depend on various factors, and could have a material impact on U.S. GAAP earnings and cash flow measures for the guidance period.
Dividends
Amcor has received a waiver from the ASX’s settlement operating rules, which will allow the Company to defer processing conversions between its ordinary share and CDI registers from September 5, 2024 to September 6, 2024 inclusive.
U.S. GAAP Condensed Consolidated Statements of Income (Unaudited)
Three Months Ended June 30,
Twelve Months Ended June 30,
($ million, except per share amounts)
2023
2024
2023
2024
Net sales
3,673
3,535
14,694
13,640
Cost of sales
(2,951)
(2,781)
(11,969)
(10,928)
Gross profit
722
754
2,725
2,712
Selling, general, and administrative expenses
(329)
(329)
(1,246)
(1,260)
Research and development expenses
(25)
(26)
(101)
(106)
Restructuring and other related activities, net
(59)
(15)
104
(97)
Other income/(expense), net
16
11
26
(35)
Operating income
325
395
1,508
1,214
Interest expense, net
(70)
(78)
(259)
(310)
Other non-operating income/(expense), net
(3)
1
2
3
Income before income taxes and equity in loss of affiliated
companies
252
318
1,251
907
Income tax expense
(68)
(56)
(193)
(163)
Equity in loss of affiliated companies, net of tax
—
(1)
—
(4)
Net income
184
261
1,058
740
Net income attributable to non-controlling interests
(4)
(4)
(10)
(10)
Net income attributable to Amcor plc
181
257
1,048
730
USD:EUR average FX rate
0.9185
0.9287
0.9561
0.9245
Basic earnings per share attributable to Amcor
0.124
0.178
0.709
0.505
Diluted earnings per share attributable to Amcor
0.123
0.178
0.705
0.505
Weighted average number of shares outstanding – Basic
1,452
1,439
1,468
1,439
Weighted average number of shares outstanding – Diluted
1,456
1,443
1,476
1,441
U.S. GAAP Condensed Consolidated Statements of Cash Flows (Unaudited)
Twelve Months Ended June 30,
($ million)
2023
2024
Net income
1,058
740
Depreciation, amortization, and impairment
586
595
Net gain on disposal of businesses and investments
(220)
—
Changes in operating assets and liabilities, excluding effect of acquisitions, divestitures, and
currency
(265)
(120)
Other non-cash items
102
106
Net cash provided by operating activities
1,261
1,321
Purchase of property, plant, and equipment and other intangible assets
(526)
(492)
Proceeds from sales of property, plant, and equipment and other intangible assets
30
39
Business acquisitions and Investments in affiliated companies, and other
(177)
(23)
Proceeds from divestitures
365
—
Net debt proceeds/(repayments)
228
(43)
Dividends paid
(723)
(722)
Share buy-back/cancellations
(432)
(30)
Purchase of treasury shares and tax withholdings for share-based incentive plans
(87)
(51)
Other, including effects of exchange rate on cash and cash equivalents
(100)
(100)
Net decrease in cash and cash equivalents
(161)
(101)
Cash and cash equivalents at the beginning of the year(1)
850
689
Cash and cash equivalents at the end of the period
689
588
(1) Cash and cash equivalents at the beginning of fiscal 2023 includes $75 million of cash and cash equivalents as held for sale.
U.S. GAAP Condensed Consolidated Balance Sheets (Unaudited)
($ million)
June 30, 2023
June 30, 2024
Cash and cash equivalents
689
588
Trade receivables, net
1,875
1,846
Inventories, net
2,213
2,031
Property, plant and equipment, net
3,762
3,763
Goodwill and other intangible assets, net
6,890
6,736
Other assets
1,574
1,560
Total assets
17,003
16,524
Trade payables
2,690
2,580
Short-term debt and current portion of long-term debt
93
96
Long-term debt, less current portion
6,653
6,603
Accruals and other liabilities
3,477
3,292
Shareholders’ equity
4,090
3,953
Total liabilities and shareholders’ equity
17,003
16,524
Components of Fiscal 2024 Net Sales growth
Three Months Ended June 30
Twelve Months Ended June 30
($ million)
Flexibles
Rigid
Packaging
Total
Flexibles
Rigid
Packaging
Total
Net sales fiscal year 2024
2,686
849
3,535
10,332
3,308
13,640
Net sales fiscal year 2023
2,777
897
3,673
11,154
3,540
14,694
Reported Growth %
(3)
(5)
(4)
(7)
(7)
(7)
FX %
(1)
—
(1)
1
—
1
Constant Currency Growth %
(2)
(6)
(3)
(8)
(7)
(8)
Raw Material Pass Through %
(1)
(4)
(2)
(1)
(1)
(1)
Items affecting comparability %
—
—
—
(1)
—
(1)
Comparable Constant Currency
Growth %
(1)
(2)
(1)
(6)
(6)
(6)
Acquired Operations %
—
—
—
—
—
—
Organic Growth
(1)
(2)
(1)
(6)
(6)
(6)
Volume %
3
(5)
1
(4)
(8)
(5)
Price/Mix %
(4)
3
(3)
(2)
2
(1)
Reconciliation of Non-GAAP Measures
Reconciliation of adjusted Earnings before interest, tax, depreciation and amortization (EBITDA), Earnings before interest
and tax (EBIT), Net income, Earnings per share (EPS) and Free Cash Flow
Three Months Ended June 30, 2023
Three Months Ended June 30, 2024
($ million)
EBITDA
EBIT
Net
Income
EPS
(Diluted
US
cents)(1)
EBITDA
EBIT
Net
Income
EPS
(Diluted
US
cents)(1)
Net income attributable to Amcor
181
181
181
12.3
257
257
257
17.8
Net income attributable to non-controlling
interests
4
4
4
4
Tax expense
68
68
56
56
Interest expense, net
70
70
78
78
Depreciation and amortization
144
136
EBITDA, EBIT, Net income and EPS
467
323
181
12.3
531
395
257
17.8
Impact of highly inflationary accounting
5
5
5
0.4
(2)
(2)
(2)
(0.1)
Property and other losses,net
2
2
2
0.1
—
—
—
—
Restructuring and other related activities, net(2)
66
66
66
4.5
15
15
15
1.0
Other
—
—
—
—
(0.1)
5
5
5
0.3
Amortization of acquired intangibles(3)
40
40
2.9
41
41
2.9
Tax effect of above items
(12)
(0.8)
(11)
(0.8)
Adjusted EBITDA, EBIT, Net income, and EPS
540
436
282
19.3
550
454
305
21.1
Reconciliation of adjusted growth to comparable constant currency growth
% growth – Adjusted EBITDA, EBIT, Net income and EPS
2
4
8
9
% items affecting comparability(4)
—
—
—
—
% currency impact
—
—
1
—
% comparable constant currency growth
2
4
9
9
Adjusted EBITDA
540
550
Interest paid, net
(79)
(99)
Income tax paid
(95)
(90)
Purchase of property, plant and equipment and
other intangible assets
(144)
(134)
Proceeds from sales of property, plant and
equipment and other intangible assets
18
27
Movement in working capital
572
610
Other
22
(27)
Adjusted Free Cash Flow
834
837
(1) Calculation of diluted EPS for the three months ended June 30, 2024 excludes net income attributable to shares to be repurchased under
forward contracts of $1 million. Calculation of diluted EPS for the three months ended June 30, 2023 excludes net income attributable to shares to
be repurchased under forward contracts of $1 million.
(2) Includes incremental restructuring and other costs attributable to group wide initiatives to partly offset divested earnings from the Russian
business.
(3) Amortization of acquired intangible assets from business combinations.
(4) Reflects the impact of acquired, disposed, and ceased operations.
Twelve Months Ended June 30, 2023
Twelve Months Ended June 30, 2024
($ million)
EBITDA
EBIT
Net
Income
EPS
(Diluted
US
cents)(1)
EBITDA
EBIT
Net
Income
EPS
(Diluted
US
cents)(1)
Net income attributable to Amcor
1,048
1,048
1,048
70.5
730
730
730
50.5
Net income attributable to non-controlling
interests
10
10
10
10
Tax expense
193
193
163
163
Interest expense, net
259
259
310
310
Depreciation and amortization
569
569
EBITDA, EBIT, Net income and EPS
2,080
1,510
1,048
70.5
1,782
1,213
730
50.5
Impact of highly inflationary accounting
24
24
24
1.9
53
53
53
3.7
Property and other losses, net
2
2
2
0.1
—
—
—
—
Restructuring and other related activities, net(2)
(90)
(90)
(90)
(6.0)
97
97
97
6.7
CEO Transition costs
—
—
—
—
8
8
8
0.6
Other
2
2
2
—
22
22
22
1.5
Amortization of acquired intangibles (3)
160
160
10.8
167
167
11.6
Tax effect of above items
(57)
(4.0)
(62)
(4.4)
Adjusted EBITDA, EBIT, Net income and EPS
2,018
1,608
1,089
73.3
1,962
1,560
1,015
70.2
Reconciliation of adjusted growth to comparable constant currency growth
% growth – Adjusted EBITDA, EBIT, Net income, and EPS
(3)
(3)
(7)
(4)
% items affecting comparability(4)
3
3
3
3
% currency impact
(1)
(1)
(1)
(1)
% comparable constant currency growth
(1)
(1)
(5)
(2)
Adjusted EBITDA
2,018
1,962
Interest paid, net
(248)
(295)
Income tax paid
(225)
(253)
Purchase of property, plant and equipment and
other intangible assets
(526)
(492)
Proceeds from sales of property, plant and
equipment and other intangible assets
30
39
Movement in working capital
(229)
(15)
Other
28
6
Adjusted Free Cash Flow
848
952
(1) Calculation of diluted EPS for the twelve months ended June 30, 2024 excludes net income attributable to shares to be repurchased under forward contracts of $3 million. Calculation of diluted EPS for the twelve months ended June 30, 2023 excludes net income attributable to shares to be repurchased under forward contracts of $7 million.
(2) Includes incremental restructuring and other costs attributable to group wide initiatives to partly offset divested earnings from the Russian business.
(3) Amortization of acquired intangible assets from business combinations.
(4) Reflects the impact of acquired, disposed, and ceased operations.
Reconciliation of adjusted EBIT by reporting segment
Three Months Ended June 30, 2023
Three Months Ended June 30, 2024
($ million)
Flexibles
Rigid
Packaging
Other
Total
Flexibles
Rigid
Packaging
Other
Total
Net income attributable to Amcor
181
257
Net income attributable to non-
controlling interests
4
4
Tax expense
68
56
Interest expense, net
70
78
EBIT
283
62
(22)
323
351
73
(29)
395
Impact of highly inflationary accounting
—
5
—
5
—
(2)
—
(2)
Property and other losses, net
—
—
2
2
—
—
—
—
Restructuring and other related
activities, net(1)
62
2
2
66
11
4
—
15
Other
3
3
(6)
—
—
—
5
5
Amortization of acquired intangibles(2)
39
1
—
40
41
—
—
41
Adjusted EBIT
387
73
(24)
436
403
75
(24)
454
Adjusted EBIT / sales %
13.9 %
8.1 %
11.9 %
15.0 %
8.8 %
12.8 %
Reconciliation of adjusted growth to comparable constant currency growth
% growth – Adjusted EBIT
4
3
—
4
% items affecting comparability(3)
—
—
—
—
% currency impact
1
(1)
—
—
% comparable constant currency
5
2
—
4
(1) Includes incremental restructuring and other costs attributable to group wide initiatives to partly offset divested earnings from the Russian business.
(2) Amortization of acquired intangible assets from business combinations.
(3) Reflects the impact of acquired, disposed, and ceased operations.
Twelve Months Ended June 30, 2023
Twelve Months Ended June 30, 2024
($ million)
Flexibles
Rigid
Packaging
Other
Total
Flexibles
Rigid
Packaging
Other
Total
Net income attributable to Amcor
1,048
730
Net income attributable to non-
controlling interests
10
10
Tax expense
193
163
Interest expense, net
259
310
EBIT
1,357
225
(72)
1,510
1,147
185
(119)
1,213
Impact of highly inflationary
accounting
—
24
—
24
—
53
—
53
Property and other losses, net
—
—
2
2
—
—
—
—
Restructuring and other related
activities, net(1)
(100)
8
2
(90)
79
18
—
97
CEO transition costs
—
—
—
—
—
—
8
8
Other
17
3
(18)
2
5
—
17
22
Amortization of acquired intangibles(2)
155
5
—
160
164
3
—
167
Adjusted EBIT
1,429
265
(86)
1,608
1,395
259
(94)
1,560
Adjusted EBIT / sales %
12.8 %
7.5 %
10.9 %
13.5 %
7.8 %
11.4 %
Reconciliation of adjusted growth to comparable constant currency growth
% growth – Adjusted EBIT
(2)
(2)
—
(3)
% items affecting comparability(3)
3
—
—
3
% currency impact
(1)
(2)
—
(1)
% comparable constant currency growth
—
(4)
—
(1)
(1) Includes incremental restructuring and other costs attributable to group wide initiatives to partly offset divested earnings from the Russian business.
(2) Amortization of acquired intangible assets from business combinations.
(3) Reflects the impact of acquired, disposed, and ceased operations.
Reconciliation of net debt
($ million)
June 30, 2023
June 30, 2024
Cash and cash equivalents
(689)
(588)
Short-term debt
80
84
Current portion of long-term debt
13
12
Long-term debt excluding current portion
6,653
6,603
Net debt
6,057
6,111
View original content:https://www.prnewswire.com/news-releases/amcor-reports-fiscal-2024-results-and-provides-outlook-for-fiscal-2025-302223329.html
SOURCE Amcor

You may like
Technology
LexisNexis Risk Solutions Extends Risk Intelligence to Agentic Activity
Published
28 minutes agoon
November 6, 2026By
AI agents are creating a new class of digital interaction, requiring organisations to distinguish legitimate agent activity from malicious automationKnow Your Agent intelligence helps organisations identify agent activity and fold it into broader risk intelligence used to assess digital interactionsBuilt on the unique scale and connectivity of the LexisNexis® Risk Intelligence Network, Know Your Agent intelligence helps organisations prepare for an agentic future.
UNITED KINGDOM, Nov. 6, 2026 /PRNewswire/ — LexisNexis® Risk Solutions has extended its powerful risk intelligence solutions to help organisations understand and assess a new class of digital actor: AI agents operating on behalf of people and businesses.
For decades, LexisNexis Risk Solutions has helped organisations make risk decisions by connecting identity, device, behavioural, network and transaction intelligence at global scale. As AI agents become another participant in digital interactions, the company is extending that same connected intelligence approach to agentic activity.
Know Your Agent (KYA) intelligence adds a new layer of agentic insights to LexisNexis Risk Solutions’ digital identity and fraud prevention platform. It helps organisations recognise when AI agents are interacting with their digital services and can bring those interactions directly into established risk assessment and decisioning workflows, rather than treating them as an isolated risk problem. Many LexisNexis Risk Solutions customers are already using KYA intelligence in their current risk management decision making.
Analysis of global digital transactions by LexisNexis Risk Solutions shows agentic traffic grew over 750% in the first half of 2026 alone. Rapid growth is expected to continue as more people and organisations adopt agents to undertake everyday tasks such as online shopping.
Because most personal agents today do not self-declare as agents, organisations face an immediate challenge: distinguishing agentic activity from other digital traffic. But this is only the first step. Agent detection alone cannot answer key questions organisations ultimately need to resolve: Who or what is the agent acting for? Has that activity been authorised? Is its behaviour consistent with that authority? And does the wider context of the interaction indicate that it is legitimate?
That context may also change during a digital journey as control passes between a person and an AI agent, making continuous visibility into the interaction increasingly important. This is where the scale and connectivity of the Risk Intelligence Network becomes essential.
AI-agent activity does not need to be evaluated as an isolated interaction. It can be understood in the context of the identities, devices, networks, behavioural patterns and relationships surrounding digital activity, helping to provide richer context for risk decisions. This connected intelligence approach incorporates agent detection into risk decisions in real time, while aiding in creating a foundation for increasingly sophisticated agent identity and authorisation capabilities as agents, standards and use cases evolve.
Autonomous AI agents have the potential to increase the scale and sophistication of fraud, including authorised push payment fraud and account takeover attacks. Malicious agents can learn dynamically from successes and failures, enabling subsequent attacks to become more tailored and prolific.
For organisations, the decision is not whether an agent is universally trusted but whether a specific agent, acting in a specific context, should be permitted to perform a specific action. Legitimate agents will increasingly participate in digital customer journeys, but the appropriate response will depend on what the agent is attempting to do, the context of the interaction, and the organisation’s own risk policies. KYA intelligence helps organisations bring agentic activity into existing decisioning workflows so they can allow, authenticate, review or reject interactions as appropriate.
“Agentic commerce is moving quickly from experimentation into the mainstream,” said Grayson Clarke, chief commercial officer at LexisNexis Risk Solutions. “Agentic transactions globally more than doubled again in the last quarter, driven primarily by personal agents. Some businesses are enabling agents to transact on consumers’ behalf, while others are restricting their activities, and many are still determining the right approach. We have already seen firsthand how a global financial institution used our detection capabilities to help identify agentic activity and prevent it from executing sensitive transactions.”
LexisNexis Risk Solutions analysed more than 116 billion digital transactions globally in 2025 through its LexisNexis® Digital Identity Network®, giving it a uniquely broad view of how human, automated and increasingly agentic interactions are evolving. The network detected 4.9 billion automated bot attacks during the year, a 59% increase year over year. That scale reflects the role LexisNexis Risk Solutions already plays in helping many of the world’s largest financial institutions, merchants and digital businesses assess risk across digital interactions.
Mike Woodberry, senior vice president of product and analytics at LexisNexis Risk Solutions, added, “Managing risk in the agentic economy will require more than agent detection alone. The real challenge is establishing context: what is acting, who or what it represents, whether it is authorised and what it is attempting to do. Our vision for KYA is to extend established risk intelligence into the agentic economy, helping give organisations the flexibility to apply the appropriate response to each interaction rather than relying on a one-size-fits-all risk assessment.”
Woodberry continued, “Organisations should not have to build a new risk strategy every time digital interactions evolve. Adding a new layer of agentic insights to our established identity and fraud prevention platform helps customers build on the capabilities they already rely on while preparing for the next generation of digital interactions.”
Discover more about how organisations can distinguish between human and agentic traffic.
About LexisNexis Risk Solutions
LexisNexis® Risk Solutions provides customers with information-based analytics and decision tools that combine public and industry-specific content with advanced technology and algorithms to assist them in evaluating and predicting risk and enhancing operational efficiency. Headquartered in metro Atlanta, Georgia, the company has offices throughout the world, serves customers in more than 190 countries and territories and is part of RELX. For more information, please visit LexisNexis Risk Solutions.
Media Contact:
Mike Normansell
Senior Media Relations Manager
+44 7743899948
Disclaimer
LexisNexis® Risk Solutions products and services provide risk signals, analytics and insights designed to assist customers in making risk-based decisions. Results may vary depending on factors including implementation, data availability, transaction characteristics and customer use. No product or service can detect or prevent all fraudulent, malicious, unauthorized or agentic activity. References to detection, identification, risk assessment or prevention should not be interpreted as a guarantee of outcomes.
View original content to download multimedia:https://www.prnewswire.co.uk/news-releases/lexisnexis-risk-solutions-extends-risk-intelligence-to-agentic-activity-302931935.html
Technology
EPG Modular Data Center Marks Topping-Out of Its US$120 Million Malaysia FIZ Factory
Published
28 minutes agoon
November 6, 2026By
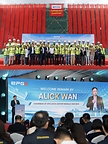
JOHOR BAHRU, Malaysia, Nov. 6, 2026 /PRNewswire/ — EPG Modular Data Center today marked the topping-out of its Malaysia FIZ (Free Industrial Zone) Factory in Senai Airport City (SAC), Johor. The milestone advances development of a manufacturing base closer to customers in Southeast Asia, expanding EPG’s production capabilities and strengthening its ability to respond to customer needs across the region and beyond.
The ceremony featured the raising of the final structural beam, followed by a tour of the facility. Guests included representatives from the Johor State Government, SAC and other government agencies, as well as business partners, customers, financial institutions and investment firms.
Representing an investment of approximately US$120 million, EPG’s FIZ Factory spans 107,450 square meters, including 70,000 square meters of production space. Scheduled for completion in the first quarter of 2027, the facility is projected to rank among the largest single-site data center module manufacturing bases in the modular data center (MDC) sector by production capacity. Once fully operational, it is expected to employ more than 800 people locally.
The factory’s master plan comprises five buildings for sheet metal production, power transfer unit (PTU) products, diesel generator manufacturing, final assembly, and R&D and office functions. The facility will produce MDC shelters and supporting equipment, including diesel generator sets and PTU power modules.
Designed for flexible, digitally enabled manufacturing, the FIZ Factory will integrate advanced automation equipment, intelligent control systems and automated welding technology. Its production lines are expected to achieve an automation rate of at least 80%, with processes including pretreatment, laser cutting, robotic welding and dust-free coating. Modular line design will accommodate multiple product types and specifications.
Digital platforms for supplier relationship management (SRM), product lifecycle management (PLM), manufacturing execution (MES), quality management (QMS) and warehouse management (WMS) will connect processes across the supply chain, R&D, production, quality and warehousing. Digital twin technology will support production visibility and traceability, while intelligent sensing and real-time alerts will help strengthen workplace and equipment safety.
By consolidating production of MDC shelters and critical power equipment in Malaysia, EPG is building capacity closer to regional customers. The factory is expected to help the company coordinate production and assembly, respond more effectively to project schedules and deliver with greater flexibility.
EPG is also committed to responsible operations at the facility. Its priorities include resource efficiency, waste reduction, environmental protection, employee safety, local talent development and cooperation with Malaysian suppliers and partners. The company will operate in accordance with Malaysian laws and regulations and its ESG management requirements, integrating environmental, social and governance (ESG) principles into its decision-making, compliance and risk management.
“The FIZ Factory marks an important step in bringing EPG’s manufacturing capabilities closer to customers and the markets we serve,” said Alick Wan, EPG’s founder and chairman. “By combining advanced manufacturing with strong local partnerships, we are building a responsive base in Malaysia and a model that can evolve with customer needs in other markets.”
Learn more about EPG Modular Data Center at www.epg-module.com.
Contact: communications@epg-module.com
About EPG
EPG is a prefabricated modular data center infrastructure provider, powered by R&D centers in Singapore, Malaysia, and Shanghai, as well as six advanced manufacturing hubs in Malaysia and China. With over 20 years of engineering expertise, it has a workforce of over 1,700 employees, including more than 300 researchers and experienced engineers in its R&D and technical team. Through continuous technological innovation and a scalable delivery system, EPG delivers integrated and efficient data center solutions for hyperscale, cloud, and enterprise deployments across APAC, EMEA, and other global markets.
View original content to download multimedia:https://www.prnewswire.com/news-releases/epg-modular-data-center-marks-topping-out-of-its-us120-million-malaysia-fiz-factory-302931943.html
SOURCE EPG Global Technology (Shanghai) Co., Ltd.
Technology
TCL CSOT Begins Equipment Move-In at Its t8 Production Line
Published
28 minutes agoon
November 6, 2026By
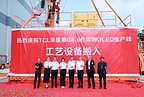
GUANGZHOU, China, Nov. 6, 2026 /PRNewswire/ — TCL CSOT’s t8 8.6-generation Inkjet Printing OLED (IJP OLED) production line in Guangzhou had entered the equipment move-in phase on October 31. With core production equipment now moving into the facility, the world’s first 8.6-generation IJP OLED production line has entered the final phase before expected mass production in 2027. The announcement was made at a ceremony attended by TCL CSOT executives and suppliers.
“The move-in of the first piece of core production equipment marks the t8 project’s transition to the equipment installation and commissioning phase,” said Feng Zhang, Senior Vice President of TCL CSOT. “This is one of the most advanced facilities of its kind, and installing the state-of-the-art equipment will be a true test of our ability to work with our partners to expand current technical limits. We look forward to working closely with our partners to take on these challenges as we establish t8 as a new benchmark for safety, quality, and efficiency.”
Representing a major strategic investment in the next generation of display technology, the t8 project will play a key role in driving future display development through IJP OLED. With a total investment of approximately RMB 29.5 billion and a designed monthly processing capacity of approximately 22,500 glass substrates (8.6-generation, approximately 2,290 mm × 2,620 mm), the production line will primarily produce displays for tablets, laptops, and monitors, with scope to expand into flexible and foldable displays. Following the start of construction on September 16, 2025, the main factory structure was topped out in just 226 days. Equipment move-in at t8 marks the project’s entry into the final phase before mass production. The project will now proceed through production line installation, integrated commissioning of power systems, and process validation, with mass production expected in the fourth quarter of 2027.
IJP OLED uses an inkjet printing process to deposit organic light-emitting materials onto glass substrates with greater precision through a process known as on-demand deposition. Compared with traditional vacuum thermal evaporation (VTE), IJP achieves higher material utilization for greener, more efficient production, and is widely recognized as a key technological pathway for next-generation displays.
“From a single drop of ink and a small prototype to our G5.5 line (t12) in Wuhan becoming the world’s first IJP OLED mass production line, and now the move-in at our G8.6 production line in Guangzhou, TCL CSOT has spent the past 13 years bringing IJP OLED from the laboratory to the production line. Equipment move-in at t8 marks the start of the final stretch before mass production,” said Weiran Cao, General Manager of IJP-OLED Middle Platform of TCL CSOT.
As the t8 project progresses towards mass production, TCL CSOT will continue to drive wider adoption of the industry-leading IJP OLED technology and further expand the sizes and applications of its OLED portfolio, delivering advanced displays and improved experiences for customers and end users worldwide.
SOURCE TCL CSOT


LexisNexis Risk Solutions Extends Risk Intelligence to Agentic Activity

EPG Modular Data Center Marks Topping-Out of Its US$120 Million Malaysia FIZ Factory

TCL CSOT Begins Equipment Move-In at Its t8 Production Line

Send Rakhi to UK swiftly with UK Gifts Portal

Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

Nullmax and Renesas Forge Strategic Partnership to Deliver Competitive ADAS Solutions for the Global Market

Why You Should Build on #NEAR – Co-founder Illia Polosukhin at CV Labs
Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

NEAR End of Year Town Hall 2021: The Open Web World, MetaBUILD 2 Hackathon and 2021 recap
Trending
-

 Coin Market4 days ago
Binance net outflows surge to $5.8B as withdrawals resume after record hack
-

 Coin Market4 days ago
THORChain halts swaps after block reorg bug, slowing Binance hackers
-
 Technology4 days ago
RD Technologies Upgrades Its Cross-Border Payments and Digital Finance Ecosystem
-

 Technology4 days ago
Thunes and UnionPay International Transform Payments to China’s Mainland, Launching High-Capacity Instant Payouts
-

 Technology3 days ago
AGIBOT Unveils GO-3 Preview, Takes Top Spot on Three Embodied AI Benchmarks
-
 Technology4 days ago
Ace nanochem Develops Three New Semiconductor Materials for Power Devices and Advanced Packaging
-
 Technology4 days ago
Tiger Brokers Brings Extended-Hours* US Options Trading to Investors Worldwide
-
 Technology4 days ago
FF EAI Robotics Ecosystem (FFR) CEO YT Jia Shares Weekly Investor Update: Recaps FFR’s Listing Closing and First Investor Day in New York; FFR Sold and Shipped 351 Robot Devices in October, Setting Another Monthly Record