Technology
Jowell Global Ltd. Announces First Half 2024 Unaudited Financial Results
Published
2 years agoon
By
— First Half Revenue of $85.7 million, increase 1.5% year-over-year —
— First Half GMV of $107.3 million, down 7.0% year-over-year —
SHANGHAI, Dec. 19, 2024 /PRNewswire/ — Jowell Global Ltd. (“Jowell” or the “Company”) (NASDAQ: JWEL), one of the leading cosmetics, health and nutritional supplements, and household products e-commerce platforms in China, today announced its unaudited financial results for the six months ended June 30, 2024.
First Half 2024 Financial and Operational Highlights
Total revenues were $85.7 million, an increase of 1.5% from $84.4 million in the same period of 2023.Net loss was $3.8 million, a decrease of 47.1%, as compared to the net loss of $7.1 million in the same period of 2023.Total GMV (Gross Merchandise Value) transacted in our online shopping mall was $107.3 million, a decrease of 7.0% from $115.5 million in the same period of 2023.Total VIP members[1] as of June 30, 2024 were approximately 2.7 million, an increase of 8.5% compared to approximately 2.5 million as of June 30, 2023.Total LHH stores[2] as of June 30, 2024 were 26,795, an increase of 1.0% compared to 26,528 as of June 30, 2023.
[1] “Total VIP members” refers to the total number of members registered on Jowell’s platform as of June 30, 2024
and June 30, 2023.
[2] “LHH stores” refers to the brand name of “Love Home Store”. Authorized retailers may operate as independent
stores or store-in-shop (an integrated store), selling products they purchased through Jowell’s online platform
LHH Mall under their retailer accounts, which provides them with major discounts.
First Half 2024 Financial Results
Total Revenues
Total revenues for the first half 2024 were $85.7 million, representing an increase of 1.5% from $84.4 million in the same period of 2023. Our weighted average unit price was $5.16 per unit for the first half of 2024, which represented an increase of 4.2% as compared to $4.95 per unit for the same period of 2023.
Our health and nutritional supplements revenue for the first half of 2024 increased by about $11.1 million, or 182.1%, as compared to the same period of 2023. The increase in health and nutritional supplements revenue was mainly due to the increase in sales of premium brand health and nutritional supplements. We have stepped up our promotions on these items during the Chinese New Year holidays in the first half of 2024 in an attempt to offer more promotional discounts in response to the overall market downturn.
First Half Ended June 30
%
2024
2023
change
Revenues (in thousands, except for percentages)
US$
US$
YoY*
Product sales
• Cosmetic products
19,768.5
29,495.5
(33.0 %)
• Health and nutritional supplements
17,190.7
6,094.2
182.1 %
• Household products
48,438.7
48,473.1
(0.1 %)
• Others
286.4
343.4
(16.6 %)
Total
85,684.3
84,406.2
1.5 %
* YOY—year over year
Total cost and operating expenses were $89.6 million in the first half of 2024, a decrease of 1.5% from $91.0 million in the same period of 2023.
Costs of revenues were $84.8 million in the first half of 2024, an increase of 1.3% from $83.8 million in the same period of 2023, which including an increase of $11.1 million in health and nutritional supplements and partially offset by a decrease of $7.9 million in cosmetic products and $1.4 million in household products.Cost of revenues of health and nutritional supplements for the first half 2024 increased about 189.9% as compared to the same period of 2023. The increase was primarily due to a 65.7% increase in weighted average unit cost. The increase in weighted average unit costs for our health and nutritional supplements is mainly because we offered and sold more higher unit price products in the first half 2024 than the same period of 2023.The decrease in the cost of cosmetic products and household products was attributable to a decrease in the weighted average unit cost and a decrease in sales volume. The weighted average unit cost of cosmetic products decreased from $2.94 in the first half of 2023 to $2.47 in the first half of 2024, and weighted average unit cost of household products decreased from $8.18 in the first half of 2023 to $8.11 in the first half of 2024, both decreases mainly due to reduced customers discretionary spendings on premium brands and their preference to low cost, low price and necessity household products during the first half of 2024, as compared to the same period of 2023. The cosmetic products sales volume declined the most, with a decrease of 13.5% during the first half of 2024 comparing to the same period of 2023.Fulfillment expenses primarily consist of costs related to expenses paid for order preparing, packaging, outbound freight, and physical storage. Fulfillment expenses were $0.8 million in the first half of 2024, a decrease of 56.8% from the $1.9 million in the same period of 2023. Fulfillment expenses as a percentage of total revenues were 1% in the first half of 2024, down from 2.3% in the first half of 2023. The significant reduction in fulfillment costs are attributed to our cost reduction measures in logistics. Firstly, we reduced the rental area of warehouses and labor costs in the logistics process; Secondly, we switched to logistics service providers with lower cost to replace the original ones, significantly reducing express logistics costs.Marketing expenses primarily consist of targeted online advertising, and payroll and related expenses for personnel engaged in marketing and selling activities. Marketing expenses were $2.8 million in the first half of 2024, a decrease of 15.8% from the $3.3 million in the same period of 2023. The decrease was primarily due to a decrease in our marketing and promotion activities. Marketing expense as percentage of total revenues was 3.2% in the first half of 2024, down from 3.9% in the same period of 2023.General and administrative expenses mainly consist of payroll, depreciation, office supplies and upkeep. General and administration expenses were $1.2 million in the first half of 2024, a decrease of 40.1% from $2.0 million in the same period of 2023. General and administration expenses as percentage of total revenues was 1.4% in the first half of 2024, down from 2.3% in the same period of 2023.
Operating Loss
Operating loss was $4.0 million for the first half of 2024, compared with the operating loss of $6.6 million in the same period of 2023. The decrease in operating loss for the first half of 2024 was mainly due the decrease of marketing expenses, as well as reduction of operating expenses as discussed above.
Net Loss
Net loss was $3.8 million, a decrease of 47.1% compared with net loss of $7.1 million in the same period of 2023, which was mainly due the factors mentioned above.
Loss per Share
The Company computes earnings (loss) per share (“EPS”) in accordance with ASC 260, “Earnings per Share” (“ASC 260”). Each of the Company’s Preferred Share has voting rights equal to two Ordinary Shares of the Company and each Preferred Share is convertible into one Ordinary Share at any time. Except for voting rights and conversion rights, the Ordinary Shares and the Preferred Shares rank pari passu with one another and have the same rights, preferences, privileges and restrictions. For the first half ended June 30, 2024 and 2023, respectively, the Company had no potential ordinary shares outstanding that could potentially dilute EPS in the future.
Cash and Cash Equivalents
For the first half of 2024, the Company reported a net loss of $3.8 million, a negative operating cash flow of $41,012 and an accumulated deficit of approximately $29.8 million. The Company’s principal sources of liquidity are sales revenues, proceeds from a private placement and a registered direct offering. As of June 30, 2024, the Company had cash and restricted cash of approximately $0.8 million, held by the variable interest entity (VIE) Shanghai Juhao Information Technology Co., Ltd. (“Shanghai Juhao”) with banks and financial institutions inside China as the Company conducts its operations primarily through the consolidated VIE in China; the Company’s working capital as of June 30, 2024 was $13.4 million. Due to the uncertainty of the current market environment, management believes it is necessary to enhance the collection of its outstanding accounts receivable and other receivables, and to be cautious in terms of its operational decisions and project selections. As of October 31, 2024, approximately $1.8 million, or 62%, of its accounts receivable balance as of June 30, 2024 were collected, and approximately $9.9 million, or 93%, of its advances to supplier balance as of June 30, 2024 were utilized. In addition, the Company’s Form F-3 registration was declared effective on August 31, 2022, and the Company may also seek equity financing from outside investors if necessary.
Based on the latest business plan of the Company, Shanghai Juhao has reduced its promotion efforts and marketing expenditures since the second half of 2023, which reduced the cash used in operating activities. Management believes that the above-mentioned factors, including cash on hand of approximately $0.8 million, will provide sufficient liquidity for the Company to meet its future liquidity and capital requirements for at least the next twelve months.
About Jowell Global Ltd.
Jowell Global Ltd. (the “Company”) is one of the leading cosmetics, health and nutritional supplements and household products e-commerce platforms in China. We offer our own brand products to customers and also sell and distribute health and nutritional supplements, cosmetic products and certain household products from other companies on our platform. In addition, we allow third parties to open their own stores on our platform for a service fee based upon sale revenues generated from their online stores and we provide them with our unique and valuable information about market needs, enabling them to better manage their sales effort, as well as an effective platform to promote their brands. The Company also sells its products through authorized retail stores all across China, which operate under the brand names of “Love Home Store” or “LHH Store” and “Best Choice Store”. For more information, please visit http://ir.1juhao.com/.
Exchange Rate
The Company’s financial information is presented in U.S. dollars (“USD”). The functional currency of the Company is the Chinese Yuan, Renminbi (“RMB”), the currency of the PRC. Any transactions which are denominated in currencies other than RMB are translated into RMB at the exchange rate quoted by the People’s Bank of China prevailing at the dates of the transactions, and exchange gains and losses are included in the statements of operations as foreign currency transaction gain or loss. The consolidated financial statements of the Company have been translated into U.S. dollars in accordance with ASC 830, “Foreign Currency Matters”.
This press release contains translations of certain RMB amounts into U.S. dollars (“USD” or “$”) at specified rates solely for the convenience of the reader. The exchange rates in effect as of June 30, 2024 and December 31, 2023 were RMB1 for $0.1403 and $0.1412, respectively. The average exchange rates for the six months ended June 30, 2024 and 2023 were RMB1 for $0.1407 and $0.1444, respectively.
Safe Harbor Statement
This press release contains forward-looking statements. These statements are made under the “safe harbor” provisions of the U.S. Private Securities Litigation Reform Act of 1995. Statements that are not historical facts, including statements about the Company’s beliefs and expectations, are forward-looking statements. Forward-looking statements involve inherent risks and uncertainties, and a number of factors could cause actual results to differ materially from those contained in any forward-looking statement. In some cases, forward-looking statements can be identified by words or phrases such as “may,” “will,” “expect,” “anticipate,” “target,” “aim,” “estimate,” “intend,” “plan,” “believe,” “potential,” “continue,” “is/are likely to” or other similar expressions. The Company may also make written or oral forward-looking statements in its reports filed with, or furnished to, the U.S. Securities and Exchange Commission, in its annual reports to shareholders, in press releases and other written materials and in oral statements made by its officers, directors or employees to third parties. These statements are subject to uncertainties and risks including, but not limited to, the following: the Company’s goals and strategies; the Company’s future business development; financial condition and results of operations; product and service demand and acceptance; reputation and brand; the impact of competition and pricing; changes in technology; government regulations; fluctuations in general economic and business conditions in China and assumptions underlying or related to any of the foregoing and other risks contained in reports filed by the Company with the SEC. For these reasons, among others, investors are cautioned not to place undue reliance upon any forward-looking statements in this press release. Additional factors are discussed in the Company’s filings with the SEC, which are available for review at www.sec.gov. The Company undertakes no obligation to publicly revise these forward-looking statements to reflect events or circumstances that arise after the date hereof.
For investor and media inquiries, please contact:
Jowell Global Ltd.
Ms. Jessie Zhao
Email: IR@1juhao.com
Jowell Global Ltd.
CONDENSED CONSOLIDATED BALANCE SHEETS
June 30,
December 31,
2024
2023
(Unaudited)
ASSETS
Current Assets:
Cash
$
805,344
$
1,250,281
Accounts receivable, net
2,344,481
2,401,056
Accounts receivable – related parties
–
47,040
Advance to suppliers
10,050,688
3,506,432
Advance to suppliers – related parties
12,493,792
9,874,545
Inventories
4,508,515
8,198,402
Prepaid expenses and other current assets
1,075,591
1,384,758
Total current assets
31,278,411
26,662,514
Long-term investment
3,709,340
3,888,377
Property and equipment, net
845,579
681,942
Intangible assets, net
532,810
634,655
Right of use lease assets, net
1,506,729
2,019,300
Other non-current asset
638,723
895,775
Deferred tax assets
512,175
515,364
Total Assets
$
39,023,767
$
35,297,927
LIABILITIES AND STOCKHOLDERS’ EQUITY
Current Liabilities:
Short-term loan
$
210,473
$
423,567
Accounts payable
2,791,515
3,765,230
Accounts payable – related parties
280,530
194,818
Deferred revenue
11,691,812
2,309,957
Deferred revenue – related parties
40,000
47,059
Current portion of operating lease liabilities
1,475,947
942,989
Accrued expenses and other liabilities
975,072
782,048
Due to related parties
414,585
528,472
Taxes payable
1,487
58,233
Total current liabilities
17,881,421
9,052,373
Non-current portion of operating lease liabilities
–
1,032,235
Total liabilities
17,881,421
10,084,608
Commitments and contingencies
Equity
Common stock, $0.0016 par value, 450,000,000 shares authorized, 2,170,475 issued
and outstanding at June 30, 2024 and December 31, 2023, respectively *
3,473
3,473
Preferred stock, $0.0016 par value, 50,000,000 shares authorized, 46,875 issued and
outstanding at June 30, 2024 and December 31, 2023, respectively *
75
75
Additional paid-in capital
52,687,182
52,687,182
Statutory reserves
394,541
394,541
Accumulated deficit
(29,768,863)
(26,039,567)
Accumulated other comprehensive loss
(2,153,720)
(1,843,970)
Total Jowell Global Ltd. Stockholders’ Equity
21,162,688
25,201,734
Noncontrolling interest
(20,342)
11,585
Total Equity
21,142,346
25,213,319
Total Liabilities and Equity
$
39,023,767
$
35,297,927
* On October 25, 2023, the Company consolidated its ordinary shares at the ratio of one-for-sixteen (“Share
Consolidation”). Immediately following the Share Consolidation, the Company increased the authorized share
capital to $80,000 divided into shares of which (i) 450,000,000 shares are designated as ordinary shares with a
nominal or par value of $0.0016 per share, and (ii) 50,000,000 shares are designated as preferred shares with a
nominal or par value of $0.0016 per share. All shares and per share data for all the periods presented have been
retroactively restated.
Jowell Global Ltd.
CONDENSED CONSOLIDATED STATEMENTS OF OPERATIONS AND COMPREHENSIVE LOSS
(Unaudited)
For the Six Months Ended
June 30,
2024
2023
Net Revenues
$
85,684,310
$
84,406,244
Cost and Operating Expenses:
Cost of revenues
(84,831,857)
(83,763,353)
Fulfillment expenses
(838,764)
(1,942,595)
Marketing expenses
(2,784,515)
(3,306,812)
General and administrative expenses
(1,186,747)
(1,981,967)
Total cost and operating expenses
(89,641,883)
(90,994,727)
Loss From Operations
(3,957,573)
(6,588,483)
Other Income (Expenses), net
Interest expense
(23,997)
(39,388)
Investment loss
(170,352)
(483,214)
Other income (expense), net
385,341
(2,118)
Other Income (expenses), net
190,992
(524,720)
Loss Before Income Taxes
(3,766,581)
(7,113,203)
Income Taxes Expense
51
2,761
Net Loss
(3,766,632)
(7,115,964)
Less: net loss attributable to noncontrolling interest
(37,336)
(26,083)
Net Loss Attributable to Ordinary Shareholders of Jowell Global Ltd.
$
(3,729,296)
$
(7,089,881)
Loss Per share – Basic and Diluted
$
(1.74)
$
(3.33)
Weighted Average Shares Outstanding – Basic and diluted*
2,170,260
2,135,574
Net Loss
$
(3,766,632)
$
(7,115,964)
Other Comprehensive Loss, net of tax
Foreign currency translation loss
(304,341)
(1,534,036)
Total Comprehensive Loss
(4,070,973)
(8,650,000)
Less: comprehensive income attributable to non-controlling interest
(31,927)
(25,637)
Comprehensive Loss Attributable to Ordinary Shareholders of Jowell Global
Ltd.
$
(4,039,046)
$
(8,624,363)
* On October 25, 2023, the Company consolidated its ordinary shares at the ratio of one-for-sixteen (“Share
Consolidation”). Immediately following the Share Consolidation, the Company increased the authorized share
capital to $80,000 divided into shares of which (i) 450,000,000 shares are designated as ordinary shares with a
nominal or par value of $0.0016 per share, and (ii) 50,000,000 shares are designated as preferred shares with a
nominal or par value of $0.0016 per share. All shares and per share data for all the periods presented have been
retroactively restated.
Jowell Global Ltd.
CONDENSED CONSOLIDATED STATEMENTS OF CHANGES IN STOCKHOLDERS’ EQUITY
FOR THE SIX MONTHS ENDED JUNE 30, 2024 AND 2023
(Unaudited)
Common Stock*
Preferred Stock*
Additional
Paid-in
Statutory
Retained
Earnings
(Accumulated
Accumulated
Other
Comprehensive
Total Jowell
Global Ltd.
Stockholders’
Noncontrolling
Total
Shares
Amount
Shares
Amount
Capital
Reserves
deficit)
Income (loss)
Equity
interest
Equity
Balance as of
January 1,
2023
2,132,788
$
3,413
46,875
$
75
$
52,557,552
$
394,541
$
(14,572,425)
$
(950,720)
$
37,432,436
$
33,471
$
37,465,907
Share-based
compensation
3,093
$
5
–
–
129,685
–
–
–
129,690
–
129,690
Capital
contributed
by minority
shareholder
–
–
–
–
–
–
–
–
–
36,105
36,105
Net loss for
the period
–
–
–
–
–
–
(7,089,881)
–
(7,089, 881)
(26,083)
(7,115,964)
Foreign
currency
translation
loss
–
–
–
–
–
–
–
(1,534,482)
(1,534,482)
446
(1,534,036)
Balance as of
June 30,
2023
2,135,881
$
3,418
46,875
$
75
52,687,237
$
394,541
$
(21,662,306)
$
(2,485,202)
$
28,937,763
$
43,939
$
28,981,702
Balance as of
January 1,
2024
2,170,475
$
3,473
46,875
$
75
$
52,687,182
$
394,541
$
(26,039,567)
$
(1,843,970)
$
25,201,734
$
11,585
$
25,213,319
Net loss for
the period
–
–
–
–
–
–
(3,729,296)
–
(3,729,296)
(37,336)
(3,766,632)
Foreign
currency
translation
loss
–
–
–
–
–
–
–
(309,750)
(309,750)
5,409
(304,341)
Balance as of June 30, 2024
2,170,475
$
3,473
46,875
$
75
$
52,687,182
$
394,541
$
(29,768,863)
$
(2,153,720)
$
21,162,688
$
(20,342)
$
21,142,346
* On October 25, 2023, the Company consolidated its ordinary shares at the ratio of one-for-sixteen (“Share
Consolidation”). Immediately following the Share Consolidation, the Company increased the authorized share
capital to $80,000 divided into shares of which (i) 450,000,000 shares are designated as ordinary shares with a
nominal or par value of $0.0016 per share, and (ii) 50,000,000 shares are designated as preferred shares with a
nominal or par value of $0.0016 per share. All shares and per share data for all the periods presented have been
retroactively restated.
Jowell Global Ltd.
CONDENSED CONSOLIDATED STATEMENTS OF CASH FLOWS
(Unaudited)
For the Six Months Ended
June 30,
2024
2023
Cash flows from operating activities:
Net loss
$
(3,766,632)
$
(7,115,964)
Adjustments to reconcile net loss to net cash provided by (used in) operating
activities:
Depreciation and amortization
160,682
202,822
Impairment loss from long-term investment
155,449
483,214
Amortization of operating lease right-of-use assets
501,604
552,702
Share-based compensation
–
129,690
Property and equipment written off
32,910
–
Changes in operating assets and liabilities:
Accounts receivables
41,845
1,670,275
Accounts receivable – related Parties
46,892
251,882
Inventories
3,650,270
(4,785,784)
Advance to suppliers
(6,586,006)
17,698,012
Advance to suppliers – related parties
(2,688,537)
(180,791)
Prepaid expenses and other current assets
301,516
(280,888)
Accounts payables
(953,319)
(236,633)
Accounts payables – related parties
87,183
(1,508,872)
Deferred revenue
9,418,057
(15,828,565)
Operating lease liabilities
(488,542)
(552,367)
Taxes payable
(56,558)
13,098
Accrued expenses and other liabilities
102,174
(429,988)
Net cash used in operating activities
(41,012)
(9,918,157)
Cash flows from investing activities:
Due from affiliate
–
(3,177,354)
Purchase of intangible assets
(2,276)
(4,950)
Disposal of equipment
–
81,469
Purchase of equipment
(9,190)
(12,260)
Net cash provided by (used in) investing activities
(11,466)
(3,113,095)
Cash flows from financing activities:
Proceeds from short-term loans
–
649,913
Repayment of short-term loans
(211,116)
(2,455,228)
Proceeds from related party loans
(113,020)
205,846
Net cash used in financing activities
(324,136)
(1,599,469)
Effect of exchange rate changes on cash
(68,323)
(103,551)
Net decrease in cash
(444,937)
(14,734,272)
Cash, beginning of period
1,250,281
16,718,102
Cash, end of period
$
805,344
$
1,983,830
Supplemental disclosure information:
Cash paid for income tax
$
51
$
2,761
Cash paid for interest
$
23,997
$
39,388
Supplemental non-cash activities:
Cash paid in prior year for purchase of intangible assets
$
(640,674)
$
–
Right of use assets obtained in exchange for operating lease obligations
$
–
$
(98,320)
View original content:https://www.prnewswire.com/news-releases/jowell-global-ltd-announces-first-half-2024-unaudited-financial-results-302336322.html
SOURCE Jowell Global Ltd.
You may like
Technology
MEXC and Payward Highlight Collaboration as Crypto and TradFi Converge at TOKEN2049
Published
9 minutes agoon
October 9, 2026By
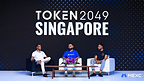
MUTSAMUDU, Comoros, Oct. 9, 2026 /CNW/ — MEXC,a pioneer in 0-fee digital asset trading, and Payward, the parent company of Kraken, shared their perspectives on the convergence of crypto and traditional finance during a TOKEN2049 Singapore panel. MEXC CEO Vugar Usi Zade and Payward Co-CEO Arjun Sethi, discussed how broader market access, retail demand and collaboration between platforms could shape the future of global trading.
Crypto and TradFi Move Closer Together
An important theme was the shift toward more connected, always-on markets. Vugar said blockchain infrastructure is challenging traditional market structures built around fixed trading hours, while users increasingly expect access to different asset classes through a more seamless experience.
“Over the next five years, we’ll see a convergence toward a singular platform where asset classes and investments can move quickly and smoothly,” said Vugar. “Retail will be the main driver.”
Arjun highlighted the infrastructure challenge behind this shift, noting that 24/7 trading is ultimately about bringing assets and collateral into a more connected financial environment.
“24/7 trading really means: how do you bring all that collateral into one place?” said Arjun.
Collaboration Over Competition
Both speakers also highlighted collaboration as an important part of scaling the next generation of global trading platforms.
Arjun noted that serving a much larger global user base will require platforms to work with partners that bring different strengths in their respective markets, explicitly pointing to MEXC as one such example.
“The only way to do that is to partner with folks, including MEXC, to be able to help succeed in their core markets,” said Arjun.
Vugar similarly emphasized that exchanges can increasingly build on one another’s strengths rather than approach every opportunity purely through competition. MEXC brings a retail-first approach, deep liquidity and broad experience in perpetual markets across crypto and TradFi assets, while Payward brings global financial infrastructure, professional trading capabilities and strong market experience in the United States.
The discussion built on the two companies’ earlier indication that they are exploring broader collaboration, with both executives pointing to infrastructure, market access and distribution as areas where greater connectivity between platforms could create value.
Trust and access were also highlighted as essential foundations for this evolution. Vugar described trust and access as two of the most important elements in building future financial platforms, while Arjun emphasized the importance of transparency as the industry becomes more connected.
The panel pointed to a future in which crypto and TradFi become increasingly connected, with collaboration between platforms helping bring together market access, infrastructure and user reach to serve a broader global audience.
About MEXC
Founded in 2018, MEXC is a leading global multi-asset trading platform built as your 0-fee gateway to infinite opportunities. Serving users across 170+ markets, MEXC provides simple and efficient access to crypto, stocks, tokenized assets, derivatives, and a growing range of TradFi-linked opportunities through one account and one gateway.
With 0 trading fees, deep liquidity, broad asset coverage, and a high-performance trading experience, MEXC is designed for retail users who want to discover earlier, act faster, and trade with fewer barriers. As crypto and traditional finance continue to converge, MEXC is committed to making global opportunities more accessible, helping users trade freely and MEXCmize every opportunity.
MEXC Official Website| X | Telegram |How to Sign Up on MEXC
Risk Disclaimer:
This content does not constitute investment advice. Given the volatility of financial markets, including digital assets, tokenized assets, and traditional financial products, investors should carefully assess market conditions, underlying asset fundamentals, and potential financial risks before making any investment or trading decisions.
View original content to download multimedia:https://www.prnewswire.com/news-releases/mexc-and-payward-highlight-collaboration-as-crypto-and-tradfi-converge-at-token2049-302903465.html
SOURCE MEXC
Technology
Ride Sharing Market worth $317.47 billion by 2033 | MarketsandMarkets™
Published
9 minutes agoon
October 9, 2026By
DELRAY BEACH, Fla., Oct. 9, 2026 /PRNewswire/ — According to MarketsandMarkets™, the Ride Sharing Market is projected to reach USD 317.47 billion by 2033, from USD 170.56 billion in 2026, at a CAGR of 9.3%.
Browse 241 market data Tables and 60 Figures spread through 301 Pages and in-depth TOC on “Ride Sharing Market”
Ride Sharing Market Size & Forecast:
Market Size Available for Years: 2022-20332026 Market Size: USD 170.56 billion2033 Projected Market Size: USD 317.47 billionCAGR (2026–2033): 9.3%
Ride Sharing Market Trends & Insights:
The B2C segment is expected to hold a larger share of the ride sharing market by business model in 2026.Micro-mobility is expected to register the fastest growth by vehicle type during the forecast period.Europe is projected to record the second-fastest growth in the ride sharing market during the forecast period.
Download PDF Brochure: https://www.marketsandmarkets.com/pdfdownloadNew.asp?id=198699113
The ride sharing market is driven by a shift from occasional ride booking toward high-frequency, platform-based mobility consumption. Growth is coming from both a larger user base and more trips per user. In addition, the expansion of the addressable trip pool also supports the growth of ride sharing market. Platforms are adding lower-cost products, premium services, scheduled mobility, corporate transportation, and specialized passenger services, allowing the same platform to capture different trip occasions and income segments.
Ride sharing demand is expanding through higher trip frequency and broader platform usage.
Uber recorded 3.9 billion trips in Q2 2026, up 18% year over year, while monthly active platform consumers increased 16% to 208 million. Importantly, trips per monthly active consumer also increased 2%, indicating that growth is being supported not only by adding users, but also by greater usage of ride sharing among existing customers.DiDi recorded 13.74 billion China Mobility transactions in 2025, up 10.8% from 2024, while its international transactions increased from 3.61 billion to 4.51 billion, up 24.7%. This reflects continued expansion of ride sharing demand across both established and international markets.Lyft completed 945.5 million rides in 2025, up 14%, while annual riders reached 51.3 million. Product expansion into family mobility, premium ground transportation, and other multimodal services is allowing platforms to capture travel occasions that extend beyond conventional daily ride hailing.
Ride sharing is being shaped by deeper usage within existing markets and faster expansion into new mobility demand pools. Higher trip frequency is encouraging platforms to improve vehicle utilization, while international expansion is opening additional transaction pools beyond mature markets. At the same time, broader service offerings are allowing platforms to address different travel requirements, from daily commuting and airport travel to corporate mobility, family transportation, and short-distance urban trips. This is pushing the industry from a single service model toward multi-use mobility platforms, where growth depends on increasing the number of travel occasions captured per user and expanding access across cities, customer segments, and transport modes.
The B2C segment is expected to hold a larger share of the ride sharing market by business model in 2026.
The B2C business model holds the largest share of the ride sharing market, as individual consumer e-hailing and short-distance commuting generate a high volume of daily ride requests across urban markets. The growth of this business model is further supported by the rising total cost of personal vehicle ownership, including vehicle purchase, fuel, maintenance, insurance, parking, and depreciation, making ride sharing an increasingly practical option for consumers who use private vehicles less frequently. In emerging economies, two-wheelers and three-wheelers are gaining traction within B2C services because of their lower fares, lower operating costs, and suitability for short-distance trips in congested cities. Alternatively, smaller mobility formats are also emerging, including pedal-assisted and electric tricycles in parts of Europe and three-wheeled mobility services in North America, although their role remains more localized than conventional passenger cars. Moreover, electrification is further reshaping the B2C model, as the higher initial cost of EVs can be offset by lower energy and maintenance expenses, particularly for vehicles with high daily utilization, resulting in a faster return on investment over the vehicle lifecycle. Thus, B2C ride sharing is expected to continue evolving in the coming years, expanding beyond conventional passenger car e-hailing toward a more cost-efficient, multi-vehicle mobility model that addresses diverse consumer trip needs.
Request for Proposal:
https://www.marketsandmarkets.com/requestsampleNew.asp?id=198699113
Micro-mobility is expected to register the fastest growth by vehicle type during the forecast period.
Micromobility, including shared e-bikes and e-scooters, is expected to register strong growth in ride sharing as demand increases for affordable and convenient short-distance mobility beyond conventional car-based services. These vehicles are well-suited for first-mile and last-mile connectivity, internal movement within gated communities, residential townships, universities, corporate campuses, industrial parks, and large commercial premises. App-based sharing models are also expanding within B2B and controlled environments such as special economic zones, business hubs & IT parks, and industrial areas, among others, allowing organizations and property developers to provide dedicated fleets while users can locate, unlock, and pay for vehicles digitally. In Asia Pacific, companies such as Yulu and Zypp Electric are expanding electric two-wheeler use across urban and commercial applications, while in Europe, companies like Lime & Dott operate shared e-bikes and e-scooters across major cities across Europe. In North America, Lime and Bird have established shared micromobility services across multiple cities, supporting short urban trips and first-mile and last-mile connectivity. Hence, the increasing use of shared e-bikes and e-scooters across residential communities, workplaces, transit hubs, and urban centers is expected to strengthen micromobility adoption as an efficient solution for short-distance travel.
Europe is projected to record the second-fastest growth in the ride sharing market during the forecast period.
Europe is expected to record the second-fastest growth in the ride sharing market. E-hailing and station-based mobility are the most prominent services, with taxi and ride hailing platforms remaining important for point-to-point travel. Shared bikes, e-bikes, and e-scooters are expanding as complementary modes for first-mile and last-mile journeys. Electric propulsion is gaining a stronger position, particularly in high-utilization urban fleets, as cities introduce low-emission requirements and operators improve access to charging. For instance, Freenow completed 51% of European trips in electrified vehicles in 2025. By vehicle type, passenger cars remain central to e-hailing and car sharing, while e-bikes and e-scooters are gaining traction for short trips, particularly within dense city centers and as connections to rail and metro networks. Consequently, short-distance trips are becoming an important growth pool, whereas passenger car-based services continue to address longer urban and intercity journeys, airport travel, and trips where public transport is less convenient. In addition, there is integration of ride sharing with public transport and MaaS platforms, supported by cities moving toward regulated parking, designated micromobility zones, data sharing, and long-term operator partnerships. Europe’s ride sharing market is also seeing stronger corporate mobility solutions as businesses shift employee and business travel toward centrally managed digital mobility platforms. Autonomous e-hailing is also moving from testing toward commercial deployment, with robotaxi services launched in Zagreb and planned deployments in Madrid, Zurich, and Munich, indicating a growing pathway for autonomous ride sharing across European cities. Overall, Europe’s growth is being supported by the convergence of electrification, micromobility, multimodal integration, corporate mobility, and emerging autonomous e-hailing, creating multiple growth avenues beyond conventional ride hailing.
Request Pricing:
https://www.marketsandmarkets.com/Enquiry_Before_BuyingNew.asp?id=198699113
Top Companies in Ride Sharing Market:
The Top Companies in Ride Sharing Market Maruti DENSO Corporation, MAHLE GmbH, Valeo SA, Hanon Systems, BorgWarner Inc., Gentherm Inc., Schaeffler AG, Johnson Electric Holdings Limited, Dana Incorporated, Robert Bosch GmbH.
Ride sharing market – Investment and Funding Scenario
Investment and Funding Context
Investment and funding activity in the ride sharing market is concentrated on autonomous mobility, strategic geographic expansion, fleet technology, and new mobility models, rather than large-scale investment in conventional ride hailing capacity. In July 2025, Lyft acquired FREENOW, expanding into nine European countries, while Grab committed strategic investments in autonomous mobility companies including WeRide and Vay to support robotaxi, autonomous shuttle, and remote driving deployment. In March 2026, Uber announced an investment of up to USD 1.25 billion in Rivian through 2031, for the planned deployment of autonomous R2 robotaxis, indicating that capital is shifting toward technology-enabled fleet models and partnerships with vehicle and autonomous driving companies. Overall, funding is being directed toward autonomous vehicles, EV-based fleets, platform expansion, fleet management technology, and strategic partnerships, creating investment opportunities across vehicle manufacturers, autonomous driving providers, fleet operators, charging infrastructure, and mobility technology providers.
Revenue Shift Context
The revenue pool in the ride sharing market is shifting from basic trip commissions toward higher-value services, platform monetization, and technology-enabled mobility. Traditional revenue remains tied to passenger fares and platform commissions from e-hailing, car rental, and car sharing, but additional revenue is emerging from corporate mobility, subscriptions, advertising, financial services, fleet management, and partnerships with EV and autonomous vehicle providers. Ride-sharing platforms are also expanding beyond individual trip transactions by integrating multiple mobility options into a single platform, allowing them to capture revenue across different stages of a customer’s journey. At the same time, autonomous vehicles can change the economics of the market by reducing the dependence on driver-supplied capacity and creating new revenue structures around robotaxi operations and fleet services. Going forward, revenue growth is expected to come increasingly from higher monetization per user, broader mobility offerings, technology-based services, corporate accounts, and autonomous and electric fleet ecosystems, rather than only from increasing ride volumes.
Mergers & Acquisitions (M&A)
Mergers & acquisitions in the ride sharing market are increasingly focused on geographic expansion, multimodal mobility, technology access, and fleet capabilities, rather than simply increasing ride volumes. Consolidation enables platforms to enter new cities and countries faster, acquire established customer and driver networks, and strengthen local operating capabilities without building these networks entirely from the ground up. Acquisitions and strategic combinations also provide access to autonomous driving, fleet management, mapping, payment, booking, and mobility integration technologies, reducing internal development time and expanding the range of services offered through a single platform. At the same time, M&A can strengthen access to vehicle fleets, taxi networks, car sharing operations, and corporate mobility customers, while creating opportunities to combine multiple mobility services under one digital ecosystem. M&A activity is expected to focus increasingly on technology-enabled mobility, autonomous fleets, multimodal platforms, geographic expansion, and fleet access, making consolidation an important route for ride-sharing companies seeking broader service coverage and higher revenue per user.
RIDE SHARING MARKET: MERGERS & ACQUISITIONS, OCTOBER 2025–MAY 2026
Month & Year
Deal Type
Company 1
Company 2
Description
May 2026
Acquisition
Grab (Singapore)
Delivery Hero (Germany)
Grab announced a deal to acquire Delivery Hero’s Taiwan delivery business, including its Foodpanda operations, for USD 600 million in cash. This acquisition strengthens Grab’s logistics and customer network, supporting its ride-hailing super-app ecosystem and international expansion strategy.
April 2026
Acquisition
Lyft (UK)
Gett (UK)
Lyft agreed to acquire Gett’s UK business, bringing Gett’s London black cab network and corporate transportation business into Lyft’s ecosystem. Gett stated that the transaction would give Lyft access to the majority of London’s registered black cab drivers and nearly double the number of rides on Lyft’s London platform.
October 2025
Acquisition
Lyft Inc. (US)
TBR Global Chauffeuring (United Kingdom)
Lyft acquired TBR Global Chauffeuring, a premium transport provider based in Glasgow, for approximately USD 101 million. This acquisition enhances Lyft’s capabilities in high-end, pre-booked ground transportation, complementing its core ride-sharing services for corporate and event clients.
Company Revenue Share Details
The top five players are estimated to account for a significant share of the ride sharing market, indicating a concentrated but highly competitive market structure across major platforms. Leading companies such as Uber, DiDi, Lyft, Grab, and Bolt benefit from large user and driver networks, broad geographic coverage, strong brand recognition, established payment infrastructure, and high booking volumes that create network effects and strengthen their market positions. Their scale also enables investment in pricing technology, driver management, mapping, safety systems, fleet partnerships, and multimodal mobility services. At the same time, regional platforms and local operators remain important because licensing requirements, local transport regulations, payment preferences, and operating models vary substantially across countries. This creates a market where global platforms compete alongside strong regional players, with network density, geographic reach, technology capabilities, regulatory access, and service diversification becoming key factors influencing competitive positioning.
Browse Adjacent Market: Automotive and Transportation Market Research Reports & Consulting
Related Reports:
About MarketsandMarkets™
MarketsandMarkets™ has been recognized as one of America’s Best Management Consulting Firms by Forbes, as per their recent report.
MarketsandMarkets™ is a blue ocean alternative in growth consulting and program management, leveraging a man-machine offering to drive supernormal growth for progressive organizations in the B2B space. With the widest lens on emerging technologies, we are proficient in co-creating supernormal growth for clients across the globe.
Today, 80% of Fortune 2000 companies rely on MarketsandMarkets, and 90 of the top 100 companies in each sector trust us to accelerate their revenue growth. With a global clientele of over 13,000 organizations, we help businesses thrive in a disruptive ecosystem.
The B2B economy is witnessing the emergence of $25 trillion in new revenue streams that are replacing existing ones within this decade. We work with clients on growth programs, helping them monetize this $25 trillion opportunity through our service lines – TAM Expansion, Go-to-Market (GTM) Strategy to Execution, Market Share Gain, Account Enablement, and Thought Leadership Marketing.
Built on the ‘GIVE Growth’ principle, we collaborate with several Forbes Global 2000 B2B companies to keep them future-ready. Our insights and strategies are powered by industry experts, cutting-edge AI, and our Market Intelligence Cloud, KnowledgeStore™, which integrates research and provides ecosystem-wide visibility into revenue shifts.
MarketsandMarkets™ SalesPlay is an AI-driven Revenue Intelligence Co-Pilot designed to help revenue teams prioritize the right accounts, identify critical changes early, and surface opportunities ahead of demand, so pipeline builds naturally and deals close with greater consistency.
To find out more, visit www.MarketsandMarkets™.com or follow us on Twitter, LinkedIn and Facebook.
Contact:
Mr. Rohan Salgarkar
MarketsandMarkets™ INC.
1615 South Congress Ave.
Suite 103, Delray Beach, FL 33445
USA: +1-888-600-6441
Email: sales@marketsandmarkets.com
Visit Our Website: https://www.marketsandmarkets.com/
Research Insight: https://www.marketsandmarkets.com/ResearchInsight/mobility-on-demand-market.asp
Content Source: https://www.marketsandmarkets.com/PressReleases/mobility-on-demand.asp
View original content to download multimedia:https://www.prnewswire.com/news-releases/ride-sharing-market-worth-317-47-billion-by-2033–marketsandmarkets-302903356.html
SOURCE MarketsandMarkets
Technology
OxGen AI Summit to Convene Global Leaders at a Critical Moment for Industry and Society
Published
9 minutes agoon
October 9, 2026By
OXFORD, England, Oct. 9, 2026 /PRNewswire/ — As Artificial Intelligence increasingly integrates into society, leaders across industry, government, and civil society face critical questions on how to unlock its value practically, responsibly, and sustainably. They must also weigh difficult decisions that will shape the trajectory of AI, from how it is impacting the economy, jobs and skills to geopolitics and how we safeguard critical thinking and human agency.
Returning as a landmark annual Summit, the Oxford Generative AI Summit (‘OxGen AI Summit’), hosted by OxGen AI Limited, will take place on 15–16 October 2026, at the Cheng Kar Shun Digital Hub, a state-of-the-art venue at Jesus College, University of Oxford.
The Summit will gather over 200 in-person global leaders spanning business, government, academia, and the media for high-level, cross-sector dialogue. Designed as an intimate two-day event, it will feature keynotes, panel discussions, and fireside chats led by distinguished global leaders exploring the practical adoption, societal impacts, and future of AI.
The Summit will convene over 70 global expert speakers from across industry, government, academia, and media. Confirmed speakers include The Honourable Dr Kevin Rudd AC (Global President & CEO, Asia Society; 26th Prime Minister of Australia), Rt Hon George Osborne CH (Managing Director & Head of OpenAI for Countries, OpenAI), Sir John Lazar CBE FREng FBCS (President, Royal Academy of Engineering), Kenneth Cukier (Deputy Executive Editor, The Economist), Baroness Beeban Kidron (Member, House of Lords; Founder, 5Rights Foundation), Rebecca Finlay (CEO, Partnership on AI), Sharon Doherty (Chief People & Places Officer, Lloyds Banking Group), Jeremy Kahn (AI Editor, Fortune), Bryan Tsao, (Chief Product Officer, Legora), Daniele Magazzeni (Group Chief AI Officer, UBS), Danielle Belgrave (VP of AI & Machine Learning, GSK), alongside leading Oxford researchers including Professor Sir Nigel Shadbolt, Carl Benedikt Frey, Professor Xiaolan Fu FAcSS, Prof. Philip Torr FREng FRS, and Professor Lord Tarassenko CBE FREng FMedSci, among others.
The agenda is structured around two core tracks: Practical AI Adoption: Exploring how AI can benefit industry and society, and how leaders are harnessing agentic AI to unlock enterprise value. Societal Impacts of AI: Addressing the profound present and future societal footprint of AI, including its impacts on jobs, skills, and the economy; geopolitics; truth, trust, and critical thinking; and other important topics.
“The Summit is the foremost forum convening multi-stakeholder leaders to examine and share their approaches to AI adoption in practice, responsibly and at scale, while also addressing its profound societal implications. Together, they discuss and debate the most pressing topics in AI that will shape our shared future,” said Cassidy Bereskin, Founder of OxGen AI. “We are honoured to welcome preeminent global leaders to Oxford and to provide a space for meaningful cross-sector dialogue on the future of AI and society.”
“It is rare to have industry, government and academia in one room thinking hard about the real impact of AI. The OxGen AI Summit provides precisely the diverse forum that legal technology needs at this time. Legora is proud to be the Platinum Sponsor of OxGen26,” said Adamantia Velonis, Director of AI Transformation & Applied Research, Legora.
“I’m honoured to be a speaker at the Oxford Generative AI Summit again this year, representing Razorfish, bringing our perspective into the room and — as always — leaving with a sharper one,” said Cristina Lawrence, Chief Social & Innovation Officer, Razorfish.
“Many of the most consequential ideas in AI emerge where research, policy, and industry meet. Salesforce Ventures is proud to support OxGen as it convenes that community in Oxford, and we look forward to meeting the founders and researchers shaping what comes next,” said Brian James Murphy, Head of Data Science and Technology, Salesforce Ventures.
For registration and additional information about the Oxford Generative AI Summit 2026, please visit the official website at oxgensummit.org.
For Media Enquiries:
info@oxgensummit.org
View original content:https://www.prnewswire.co.uk/news-releases/oxgen-ai-summit-to-convene-global-leaders-at-a-critical-moment-for-industry-and-society-302903475.html
MEXC and Payward Highlight Collaboration as Crypto and TradFi Converge at TOKEN2049
Ride Sharing Market worth $317.47 billion by 2033 | MarketsandMarkets™
OxGen AI Summit to Convene Global Leaders at a Critical Moment for Industry and Society
Send Rakhi to UK swiftly with UK Gifts Portal
Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network
Nullmax and Renesas Forge Strategic Partnership to Deliver Competitive ADAS Solutions for the Global Market
Why You Should Build on #NEAR – Co-founder Illia Polosukhin at CV Labs
Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network
NEAR End of Year Town Hall 2021: The Open Web World, MetaBUILD 2 Hackathon and 2021 recap
Trending
-
Technology3 days agoAmpersand closes generation gap between agents and the enterprise software stack, backed by $15 million from Bessemer Venture Partners
-
Technology4 days agoPavilion Launches as the First Founder-Owned National Vacation Rental Company
-
Technology3 days agoHG Insights Launches Contextual Intelligence Platform, Bringing Precision to AI-Driven GTM Revenue
-
Technology3 days agoWiremind raises €35 Million in First-Ever Funding Round
-
Technology4 days agoRain Files Application With the OCC to Establish Rain National Trust Bank
-
Coin Market4 days agoBitcoin ETFs notch third inflow week as Ether ETFs shed $138M
-
Coin Market4 days agoZcash activates NU7 on testnet ahead of November mainnet target
-
Technology4 days agoStryker Launches Mako 4 SmartRobotics™ in India, Advancing the Next Generation of Robotic-Assisted Joint Replacement