
Technology
LendingClub Reports Fourth Quarter and Full Year 2024 Results

Published
2 years agoon
By
Grew Originations +13%, Revenue +17%, and Total Assets +20% in Fourth Quarter Compared to Prior Year
Executed $400 Million Loan Sale out of the Held-for-Sale Portfolio to a New Bank Buyer
SAN FRANCISCO, Jan. 28, 2025 /PRNewswire/ — LendingClub Corporation (NYSE: LC), the parent company of LendingClub Bank, America’s leading digital marketplace bank, today announced financial results for the fourth quarter and full year ended December 31, 2024.
“We executed well in 2024, exiting the year with growth in originations, continued credit outperformance, successful new products and experiences, and more than five million members,” said Scott Sanborn, LendingClub CEO. “From this strong foundation, we are well-positioned to accelerate as we move through 2025 and further grow originations, revenue, and return on equity while continuing to innovate for our members.”
Fourth Quarter 2024 Results
Balance Sheet:
Total assets of $10.6 billion increased 20% compared to $8.8 billion in the prior year, driven primarily by the success of the Structured Certificates program as well as the purchase of a $1.3 billion LendingClub-issued loan portfolio in the third quarter of 2024.Deposits of $9.1 billion increased 24% compared to $7.3 billion in the prior year, driven by the continued success of our savings and CD offerings.LevelUp Savings, launched in the third quarter of 2024, reached balances of nearly $1.2 billion at year end.87% of total deposits are FDIC-insured.Robust available liquidity of $3.3 billion.Strong capital position with a consolidated Tier 1 leverage ratio of 11.0% and a CET1 capital ratio of 17.3%.Book value per common share was $11.83, compared to $11.34 in the prior year.Tangible book value per common share was $11.09, compared to $10.54 in the prior year.
Financial Performance:
Loan originations increased 13% to $1.85 billion, compared to $1.63 billion in the prior year, driven by the successful execution of new consumer loan initiatives combined with strong marketplace investor demand.Total net revenue increased 17% to $217.2 million, compared to $185.6 million in the prior year, driven by improved marketplace loan sales pricing and higher net interest income on a larger balance sheet.Provision for credit losses of $63.2 million, compared to $41.9 million in the prior year, primarily driven by higher held-for-investment whole loan retention.Improved net charge-offs in the held-for-investment at amortized cost loan portfolio to $46.0 million, compared to $82.5 million in the prior year.Net charge-off ratio of 4.5% compared to 6.6% in the prior year.Net income of $9.7 million, compared to $10.2 million in the prior year.Net income for the fourth quarter of 2024 includes a one-time, post-tax $3.2 million non-cash impairment expense, as a result of the Tally acquisition, for internally-developed software.Return on Equity (ROE) of 2.9%, with a Return on Tangible Common Equity (ROTCE) of 3.1%, compared to an ROE of 3.3% in the prior year, with an ROTCE of 3.6%.Pre-Provision Net Revenue (PPNR) increased 34% to $74.3 million, compared to $55.6 million in the prior year.
Three Months Ended
Year Ended
($ in millions, except per share amounts)
December 31,
2024
September 30,
2024
December 31,
2023
December 31,
2024
December 31,
2023
Total net revenue
$ 217.2
$ 201.9
$ 185.6
$ 787.0
$ 864.6
Non-interest expense
142.9
136.3
130.0
543.7
566.4
Pre-provision net revenue (1)
74.3
65.5
55.6
243.3
298.2
Provision for credit losses
63.2
47.5
41.9
178.3
243.6
Income before income tax expense
11.1
18.0
13.7
65.1
54.6
Income tax expense
(1.4)
(3.6)
(3.5)
(13.7)
(15.7)
Net income
$ 9.7
$ 14.5
$ 10.2
$ 51.3
$ 38.9
Diluted EPS
$ 0.08
$ 0.13
$ 0.09
$ 0.45
$ 0.36
(1) See page 3 of this release for additional information on our use of non-GAAP financial measures.
For a calculation of Pre-Provision Net Revenue, Tangible Book Value Per Common Share, and Return on Tangible Common Equity, refer to the “Reconciliation of GAAP to Non-GAAP Financial Measures” tables at the end of this release.
Financial Outlook
First Quarter 2025
Loan originations
$1.8B to $1.9B
Pre-provision net revenue (PPNR)
$60M to $70M
Fourth Quarter 2025
Loan originations
>$2.3B
Return on tangible common equity (ROTCE)
>8%
About LendingClub
LendingClub Corporation (NYSE: LC) is the parent company of LendingClub Bank, National Association, Member FDIC. LendingClub Bank is the leading digital marketplace bank in the U.S., where members can access a broad range of financial products and services designed to help them pay less when borrowing and earn more when saving. Based on hundreds of billions of cells of data and over $95 billion in loans, our advanced credit decisioning and machine-learning models are used across the customer lifecycle to expand seamless access to credit for our members, while generating compelling risk-adjusted returns for our loan investors. Since 2007, more than 5 million members have joined the Club to help reach their financial goals. For more information about LendingClub, visit https://www.lendingclub.com.
Conference Call and Webcast Information
The LendingClub fourth quarter 2024 webcast and teleconference is scheduled to begin at 2:00 p.m. Pacific Time (or 5:00 p.m. Eastern Time) on Tuesday, January 28, 2025. A live webcast of the call will be available at http://ir.lendingclub.com under the Filings & Financials menu in Quarterly Results. To access the call, please dial +1 (404) 975-4839, or outside the U.S. +1 (833) 470-1428, with Access Code 507312, ten minutes prior to 2:00 p.m. Pacific Time (or 5:00 p.m. Eastern Time). An audio archive of the call will be available at http://ir.lendingclub.com. An audio replay will also be available 1 hour after the end of the call until February 4, 2025, by calling +1 (929) 458-6194 or outside the U.S. +1 (866) 813-9403, with Access Code 167509. LendingClub has used, and intends to use, its investor relations website, X (formerly Twitter) handles (@LendingClub and @LendingClubIR) and Facebook page (https://www.facebook.com/LendingClubTeam) as a means of disclosing material non-public information and to comply with its disclosure obligations under Regulation FD.
Contacts
For Investors:
IR@lendingclub.com
Media Contact:
Press@lendingclub.com
Non-GAAP Financial Measures
To supplement our financial statements, which are prepared and presented in accordance with GAAP, we use the following non-GAAP financial measures: Pre-Provision Net Revenue (PPNR), Tangible Book Value (TBV) Per Common Share, and Return on Tangible Common Equity (ROTCE). Our non-GAAP financial measures do have limitations as analytical tools and you should not consider them in isolation or as a substitute for an analysis of our results under GAAP.
We believe these non-GAAP financial measures provide management and investors with useful supplemental information about the financial performance of our business, enable comparison of financial results between periods where certain items may vary independent of business performance, and enable comparison of our financial results with other public companies.
We believe PPNR is an important measure because it reflects the financial performance of our business operations. PPNR is a non-GAAP financial measure calculated by subtracting the provision for credit losses and income tax benefit/expense from net income.
We believe TBV Per Common Share is an important measure used to evaluate the company’s use of equity. TBV Per Common Share is a non-GAAP financial measure representing tangible common equity (common equity reduced by goodwill and customer relationship intangible assets), divided by the ending number of common shares issued and outstanding.
We believe ROTCE is an important measure because it reflects the company’s ability to generate income from its core assets. ROTCE is a non-GAAP financial measure calculated by dividing annualized net income by the average tangible common equity for the applicable period.
For a reconciliation of such measures to the nearest GAAP measures, please refer to the tables on pages 14 and 15 of this release.
We do not provide a reconciliation of forward-looking Pre-Provision Net Revenue and Return on Tangible Common Equity to the most directly comparable GAAP reported financial measures on a forward-looking basis because we are unable to predict future provision expense and goodwill, respectively, with reasonable certainty without unreasonable effort.
Safe Harbor Statement
Some of the statements above, including statements regarding our competitive advantages, macroeconomic outlook, anticipated future performance and financial results, are “forward-looking statements.” The words “anticipate,” “believe,” “estimate,” “expect,” “intend,” “may,” “outlook,” “plan,” “predict,” “project,” “will,” “would” and similar expressions may identify forward-looking statements, although not all forward-looking statements contain these identifying words. Factors that could cause actual results to differ materially from those contemplated by these forward-looking statements include: our ability to continue to attract and retain new and existing borrowers and platform investors; competition; overall economic conditions; the interest rate environment; the regulatory environment; default rates and those factors set forth in the section titled “Risk Factors” in our most recent Annual Report on Form 10-K, as filed with the Securities and Exchange Commission, as well as in our subsequent filings with the Securities and Exchange Commission. We may not actually achieve the plans, intentions or expectations disclosed in forward-looking statements, and you should not place undue reliance on forward-looking statements. Actual results or events could differ materially from the plans, intentions and expectations disclosed in forward-looking statements. We do not assume any obligation to update any forward-looking statements, whether as a result of new information, future events or otherwise, except as required by law.
LENDINGCLUB CORPORATION
OPERATING HIGHLIGHTS
(In thousands, except percentages or as noted)
(Unaudited)
As of and for the three months ended
% Change
December 31,
2024
September 30,
2024
June 30,
2024
March 31,
2024
December 31,
2023
Q/Q
Y/Y
Operating Highlights:
Non-interest income
$ 74,817
$ 61,640
$ 58,713
$ 57,800
$ 54,129
21 %
38 %
Net interest income
142,384
140,241
128,528
122,888
131,477
2 %
8 %
Total net revenue
217,201
201,881
187,241
180,688
185,606
8 %
17 %
Non-interest expense
142,855
136,332
132,258
132,233
130,015
5 %
10 %
Pre-provision net revenue(1)
74,346
65,549
54,983
48,455
55,591
13 %
34 %
Provision for credit losses
63,238
47,541
35,561
31,927
41,907
33 %
51 %
Income before income tax expense
11,108
18,008
19,422
16,528
13,684
(38) %
(19) %
Income tax expense
(1,388)
(3,551)
(4,519)
(4,278)
(3,529)
(61) %
(61) %
Net income
$ 9,720
$ 14,457
$ 14,903
$ 12,250
$ 10,155
(33) %
(4) %
Basic EPS
$ 0.09
$ 0.13
$ 0.13
$ 0.11
$ 0.09
(31) %
— %
Diluted EPS
$ 0.08
$ 0.13
$ 0.13
$ 0.11
$ 0.09
(38) %
(11) %
LendingClub Corporation Performance Metrics:
Net interest margin
5.42 %
5.63 %
5.75 %
5.75 %
6.40 %
Efficiency ratio(2)
65.8 %
67.5 %
70.6 %
73.2 %
70.0 %
Return on average equity (ROE)(3)
2.9 %
4.4 %
4.7 %
3.9 %
3.3 %
Return on tangible common equity (ROTCE)(1)(4)
3.1 %
4.7 %
5.1 %
4.2 %
3.6 %
Return on average total assets (ROA)(5)
0.4 %
0.6 %
0.6 %
0.5 %
0.5 %
Marketing expense as a % of loan originations
1.27 %
1.37 %
1.47 %
1.47 %
1.44 %
LendingClub Corporation Capital Metrics:
Common equity Tier 1 capital ratio
17.3 %
15.9 %
17.9 %
17.6 %
17.9 %
Tier 1 leverage ratio
11.0 %
11.3 %
12.1 %
12.5 %
12.9 %
Book value per common share
$ 11.83
$ 11.95
$ 11.52
$ 11.40
$ 11.34
(1) %
4 %
Tangible book value per common share(1)
$ 11.09
$ 11.19
$ 10.75
$ 10.61
$ 10.54
(1) %
5 %
Loan Originations (in millions)(6):
Total loan originations
$ 1,846
$ 1,913
$ 1,813
$ 1,646
$ 1,630
(4) %
13 %
Marketplace loans
$ 1,241
$ 1,403
$ 1,477
$ 1,361
$ 1,432
(12) %
(13) %
Loan originations held for investment
$ 605
$ 510
$ 336
$ 285
$ 198
19 %
206 %
Loan originations held for investment as a % of total loan originations
33 %
27 %
19 %
17 %
12 %
Servicing Portfolio AUM (in millions)(7):
Total servicing portfolio
$ 12,371
$ 12,674
$ 12,999
$ 13,437
$ 14,122
(2) %
(12) %
Loans serviced for others
$ 7,207
$ 7,028
$ 8,337
$ 8,671
$ 9,336
3 %
(23) %
(1)
Represents a non-GAAP financial measure. See “Reconciliation of GAAP to Non-GAAP Financial Measures.”
(2)
Calculated as the ratio of non-interest expense to total net revenue.
(3)
Calculated as annualized net income divided by average equity for the period presented.
(4)
Calculated as annualized net income divided by average tangible common equity for the period presented.
(5)
Calculated as annualized net income divided by average total assets for the period presented.
(6)
Includes unsecured personal loans and auto loans only.
(7)
Loans serviced on our platform, which includes unsecured personal loans, auto loans and education and patient finance loans serviced for others and retained by the Company.
LENDINGCLUB CORPORATION
OPERATING HIGHLIGHTS (Continued)
(In thousands, except percentages or as noted)
(Unaudited)
As of and for the three months ended
% Change
December 31,
2024
September 30,
2024
June 30,
2024
March 31,
2024
December 31,
2023
Q/Q
Y/Y
Balance Sheet Data:
Securities available for sale
$ 3,452,648
$ 3,311,418
$ 2,814,383
$ 2,228,500
$ 1,620,262
4 %
113 %
Loans held for sale at fair value
$ 636,352
$ 849,967
$ 791,059
$ 550,415
$ 407,773
(25) %
56 %
Loans and leases held for investment at amortized cost
$ 4,125,818
$ 4,108,329
$ 4,228,391
$ 4,505,816
$ 4,850,302
— %
(15) %
Gross allowance for loan and lease losses (1)
$ (285,686)
$ (274,538)
$ (285,368)
$ (311,794)
$ (355,773)
4 %
(20) %
Recovery asset value (2)
$ 48,952
$ 53,974
$ 56,459
$ 52,644
$ 45,386
(9) %
8 %
Allowance for loan and lease losses
$ (236,734)
$ (220,564)
$ (228,909)
$ (259,150)
$ (310,387)
7 %
(24) %
Loans and leases held for investment at amortized cost, net
$ 3,889,084
$ 3,887,765
$ 3,999,482
$ 4,246,666
$ 4,539,915
— %
(14) %
Loans held for investment at fair value (3)
$ 1,027,798
$ 1,287,495
$ 339,222
$ 427,396
$ 272,678
(20) %
277 %
Total loans and leases held for investment (3)
$ 4,916,882
$ 5,175,260
$ 4,338,704
$ 4,674,062
$ 4,812,593
(5) %
2 %
Whole loans held on balance sheet (4)
$ 5,553,234
$ 6,025,227
$ 5,129,763
$ 5,224,477
$ 5,220,366
(8) %
6 %
Total assets
$ 10,630,509
$ 11,037,507
$ 9,586,050
$ 9,244,828
$ 8,827,463
(4) %
20 %
Total deposits
$ 9,068,237
$ 9,459,608
$ 8,095,328
$ 7,521,655
$ 7,333,486
(4) %
24 %
Total liabilities
$ 9,288,778
$ 9,694,612
$ 8,298,105
$ 7,978,542
$ 7,575,641
(4) %
23 %
Total equity
$ 1,341,731
$ 1,342,895
$ 1,287,945
$ 1,266,286
$ 1,251,822
— %
7 %
(1)
Represents the allowance for future estimated net charge-offs on existing portfolio balances.
(2)
Represents the negative allowance for expected recoveries of amounts previously charged-off.
(3)
The balances at December 31, 2024 and September 30, 2024 include a loan portfolio that was purchased during the third quarter of 2024 of loans that we previously originated and sold.
(4)
Includes loans held for sale at fair value, loans and leases held for investment at amortized cost, net of allowance for loan and lease losses, and loans held for investment at fair value.
The asset quality metrics presented in the following table are for loans and leases held for investment at amortized cost and do not reflect loans held for investment at fair value:
As of and for the three months ended
December 31,
2024
September 30,
2024
June 30,
2024
March 31,
2024
December 31,
2023
Asset Quality Metrics (1):
Allowance for loan and lease losses to total loans
and leases held for investment at amortized cost
5.7 %
5.4 %
5.4 %
5.8 %
6.4 %
Allowance for loan and lease losses to commercial
loans and leases held for investment at amortized
cost
3.9 %
3.1 %
2.7 %
1.9 %
1.8 %
Allowance for loan and lease losses to consumer
loans and leases held for investment at amortized
cost
6.1 %
5.8 %
5.9 %
6.4 %
7.2 %
Gross allowance for loan and lease losses to
consumer loans and leases held for investment at
amortized cost
7.5 %
7.3 %
7.5 %
7.8 %
8.3 %
Net charge-offs
$ 45,977
$ 55,805
$ 66,818
$ 80,483
$ 82,511
Net charge-off ratio (2)
4.5 %
5.4 %
6.2 %
6.9 %
6.6 %
(1)
Calculated as ALLL or gross ALLL, where applicable, to the corresponding portfolio segment balance of loans and leases held for investment at amortized cost.
(2)
Net charge-off ratio is calculated as annualized net charge-offs divided by average outstanding loans and leases held for investment during the period.
LENDINGCLUB CORPORATION
LOANS AND LEASES HELD FOR INVESTMENT
(In thousands)
(Unaudited)
The following table presents loans and leases held for investment at amortized cost and loans held for investment at fair value:
December 31,
2024
December 31,
2023
Unsecured personal
$ 3,106,472
$ 3,726,830
Residential mortgages
172,711
183,050
Secured consumer
230,232
250,039
Total consumer loans held for investment
3,509,415
4,159,919
Equipment finance (1)
64,232
110,992
Commercial real estate
373,785
380,322
Commercial and industrial
178,386
199,069
Total commercial loans and leases held for investment
616,403
690,383
Total loans and leases held for investment at amortized cost
4,125,818
4,850,302
Allowance for loan and lease losses
(236,734)
(310,387)
Loans and leases held for investment at amortized cost, net
$ 3,889,084
$ 4,539,915
Loans held for investment at fair value (2)
1,027,798
272,678
Total loans and leases held for investment (2)
$ 4,916,882
$ 4,812,593
(1)
Comprised of sales-type leases for equipment.
(2)
The balance at December 31, 2024 includes a loan portfolio that was purchased during the third quarter of 2024 of loans that we previously originated and sold.
LENDINGCLUB CORPORATION
ALLOWANCE FOR LOAN AND LEASE LOSSES
(In thousands)
(Unaudited)
The following table presents the components of the allowance for loan and lease losses on loans and leases held for investment at amortized cost:
December 31, 2024
December 31, 2023
Gross allowance for loan and lease losses (1)
$ 285,686
$ 355,773
Recovery asset value (2)
(48,952)
(45,386)
Allowance for loan and lease losses
$ 236,734
$ 310,387
(1)
Represents the allowance for future estimated net charge-offs on existing portfolio balances.
(2)
Represents the negative allowance for expected recoveries of amounts previously charged-off.
The following tables present the allowance for loan and lease losses on loans and leases held for investment at amortized cost and do not reflect loans held for investment at fair value:
Three Months Ended
December 31, 2024
September 30, 2024
Consumer
Commercial
Total
Consumer
Commercial
Total
Allowance for loan and lease
losses, beginning of period
$ 200,899
$ 19,665
$ 220,564
$ 210,729
$ 18,180
$ 228,909
Credit loss expense for loans
and leases held for investment
56,322
5,825
62,147
45,813
1,647
47,460
Charge-offs
(64,167)
(1,887)
(66,054)
(68,388)
(721)
(69,109)
Recoveries
19,544
533
20,077
12,745
559
13,304
Allowance for loan and lease
losses, end of period
$ 212,598
$ 24,136
$ 236,734
$ 200,899
$ 19,665
$ 220,564
Three Months Ended
December 31, 2023
Consumer
Commercial
Total
Allowance for loan and lease losses, beginning of period
$ 336,288
$ 14,207
$ 350,495
Credit loss expense for loans and leases held for investment
43,227
(824)
42,403
Charge-offs
(88,904)
(1,193)
(90,097)
Recoveries
7,450
136
7,586
Allowance for loan and lease losses, end of period
$ 298,061
$ 12,326
$ 310,387
LENDINGCLUB CORPORATION
PAST DUE LOANS AND LEASES HELD FOR INVESTMENT
(In thousands)
(Unaudited)
The following tables present past due loans and leases held for investment at amortized cost and do not reflect loans held for investment at fair value:
December 31, 2024
30-59
Days
60-89
Days
90 or More
Days
Total Days
Past Due
Guaranteed
Amount (1)
Unsecured personal
$ 23,530
$ 19,293
$ 21,387
$ 64,210
$ —
Residential mortgages
151
88
—
239
—
Secured consumer
2,342
600
337
3,279
—
Total consumer loans held for investment
$ 26,023
$ 19,981
$ 21,724
$ 67,728
$ —
Equipment finance
$ 67
$ —
$ 4,551
$ 4,618
$ —
Commercial real estate
8,320
483
9,731
18,534
8,456
Commercial and industrial
6,257
1,182
15,971
23,410
18,512
Total commercial loans and leases held for investment
$ 14,644
$ 1,665
$ 30,253
$ 46,562
$ 26,968
Total loans and leases held for investment at amortized cost
$ 40,667
$ 21,646
$ 51,977
$ 114,290
$ 26,968
December 31, 2023
30-59
Days
60-89
Days
90 or More
Days
Total Days
Past Due
Guaranteed
Amount (1)
Unsecured personal
$ 32,716
$ 29,556
$ 30,132
$ 92,404
$ —
Residential mortgages
1,751
—
—
1,751
—
Secured consumer
2,076
635
217
2,928
—
Total consumer loans held for investment
$ 36,543
$ 30,191
$ 30,349
$ 97,083
$ —
Equipment finance
$ 1,265
$ —
$ —
$ 1,265
$ —
Commercial real estate
—
3,566
1,618
5,184
4,047
Commercial and industrial
12,261
1,632
1,515
15,408
11,260
Total commercial loans and leases held for investment
$ 13,526
$ 5,198
$ 3,133
$ 21,857
$ 15,307
Total loans and leases held for investment at amortized cost
$ 50,069
$ 35,389
$ 33,482
$ 118,940
$ 15,307
(1) Represents loan balances guaranteed by the Small Business Association.
LENDINGCLUB CORPORATION
CONDENSED CONSOLIDATED STATEMENTS OF INCOME
(In thousands, except share and per share data)
(Unaudited)
Three Months Ended
Change (%)
December 31,
2024
September 30,
2024
December 31,
2023
Q4 2024
vs
Q3 2024
Q4 2024
vs
Q4 2023
Non-interest income:
Origination fees
$ 64,745
$ 71,465
$ 76,702
(9) %
(16) %
Servicing fees
17,391
8,081
17,450
115 %
— %
Gain on sales of loans
15,007
12,433
11,921
21 %
26 %
Net fair value adjustments
(24,980)
(33,595)
(53,892)
26 %
54 %
Marketplace revenue
72,163
58,384
52,181
24 %
38 %
Other non-interest income
2,654
3,256
1,948
(18) %
36 %
Total non-interest income
74,817
61,640
54,129
21 %
38 %
Total interest income
240,596
240,377
208,319
— %
15 %
Total interest expense
98,212
100,136
76,842
(2) %
28 %
Net interest income
142,384
140,241
131,477
2 %
8 %
Total net revenue
217,201
201,881
185,606
8 %
17 %
Provision for credit losses
63,238
47,541
41,907
33 %
51 %
Non-interest expense:
Compensation and benefits
58,656
57,408
58,591
2 %
— %
Marketing
23,415
26,186
23,465
(11) %
— %
Equipment and software
13,361
12,789
13,190
4 %
1 %
Depreciation and amortization
19,748
13,341
11,953
48 %
65 %
Professional services
9,136
8,014
7,727
14 %
18 %
Occupancy
3,991
4,005
3,926
— %
2 %
Other non-interest expense
14,548
14,589
11,163
— %
30 %
Total non-interest expense
142,855
136,332
130,015
5 %
10 %
Income before income tax expense
11,108
18,008
13,684
(38) %
(19) %
Income tax expense
(1,388)
(3,551)
(3,529)
(61) %
(61) %
Net income
$ 9,720
$ 14,457
$ 10,155
(33) %
(4) %
Net income per share:
Basic EPS
$ 0.09
$ 0.13
$ 0.09
(31) %
— %
Diluted EPS
$ 0.08
$ 0.13
$ 0.09
(38) %
(11) %
Weighted-average common shares – Basic
112,788,050
112,042,202
109,948,785
1 %
3 %
Weighted-average common shares – Diluted
116,400,285
113,922,256
109,949,371
2 %
6 %
LENDINGCLUB CORPORATION
CONDENSED CONSOLIDATED STATEMENTS OF INCOME (Continued)
(In thousands, except share and per share data)
(Unaudited)
Year Ended December 31,
2024
2023
Change (%)
Non-interest income:
Origination fees
$ 283,420
$ 279,146
2 %
Servicing fees
64,933
98,613
(34) %
Gain on sales of loans
49,097
47,839
3 %
Net fair value adjustments
(154,659)
(134,114)
(15) %
Marketplace revenue
242,791
291,484
(17) %
Other non-interest income
10,179
11,297
(10) %
Total non-interest income
252,970
302,781
(16) %
Total interest income
907,958
832,630
9 %
Total interest expense
373,917
270,792
38 %
Net interest income
534,041
561,838
(5) %
Total net revenue
787,011
864,619
(9) %
Provision for credit losses
178,267
243,565
(27) %
Non-interest expense:
Compensation and benefits
232,158
261,948
(11) %
Marketing
100,402
93,840
7 %
Equipment and software
51,194
53,485
(4) %
Depreciation and amortization
58,834
47,195
25 %
Professional services
32,045
35,173
(9) %
Occupancy
15,798
17,532
(10) %
Other non-interest expense
53,247
57,264
(7) %
Total non-interest expense
543,678
566,437
(4) %
Income before income tax expense
65,066
54,617
19 %
Income tax expense
(13,736)
(15,678)
(12) %
Net income
$ 51,330
$ 38,939
32 %
Net income per share:
Basic EPS
$ 0.46
$ 0.36
28 %
Diluted EPS
$ 0.45
$ 0.36
25 %
Weighted-average common shares – Basic
111,731,523
108,466,179
3 %
Weighted-average common shares – Diluted
113,122,859
108,468,857
4 %
LENDINGCLUB CORPORATION
NET INTEREST INCOME
(In thousands, except percentages or as noted)
(Unaudited)
Consolidated LendingClub Corporation (1)
Three Months Ended
December 31, 2024
Three Months Ended
September 30, 2024
Three Months Ended
December 31, 2023
Average
Balance
Interest
Income/
Expense
Average
Yield/
Rate
Average
Balance
Interest
Income/
Expense
Average
Yield/
Rate
Average
Balance
Interest
Income/
Expense
Average
Yield/
Rate
Interest-earning assets (2)
Cash, cash equivalents, restricted cash and other
$ 1,193,570
$ 14,194
4.76 %
$ 939,611
$ 12,442
5.30 %
$ 1,190,539
$ 16,271
5.47 %
Securities available for sale at fair value
3,390,315
57,259
6.76 %
3,047,305
52,476
6.89 %
1,197,625
20,920
6.99 %
Loans held for sale at fair value
673,279
20,696
12.30 %
899,434
30,326
13.49 %
501,850
15,883
12.66 %
Loans and leases held for investment:
Unsecured personal loans
3,080,934
104,011
13.50 %
3,045,150
103,291
13.57 %
3,890,041
128,190
13.18 %
Commercial and other consumer loans
1,023,041
14,203
5.55 %
1,057,688
15,497
5.86 %
1,126,010
17,033
6.05 %
Loans and leases held for investment at amortized cost
4,103,975
118,214
11.52 %
4,102,838
118,788
11.58 %
5,016,051
145,223
11.58 %
Loans held for investment at fair value (3)
1,153,204
30,233
10.49 %
972,698
26,345
10.83 %
306,636
10,022
13.07 %
Total loans and leases held for investment (3)
5,257,179
148,447
11.29 %
5,075,536
145,133
11.44 %
5,322,687
155,245
11.67 %
Total interest-earning assets
10,514,343
240,596
9.15 %
9,961,886
240,377
9.65 %
8,212,701
208,319
10.15 %
Cash and due from banks and restricted cash
51,555
41,147
63,181
Allowance for loan and lease losses
(227,673)
(225,968)
(334,711)
Other non-interest earning assets
597,609
624,198
659,995
Total assets
$ 10,935,834
$ 10,401,263
$ 8,601,166
Interest-bearing liabilities
Interest-bearing deposits:
Checking and money market accounts
$ 805,362
$ 5,502
2.72 %
$ 1,092,376
$ 10,146
3.70 %
$ 1,081,875
$ 9,593
3.52 %
Savings accounts and certificates of deposit
8,214,866
92,698
4.49 %
6,944,586
86,717
4.97 %
5,720,058
66,660
4.62 %
Interest-bearing deposits
9,020,228
98,200
4.33 %
8,036,962
96,863
4.79 %
6,801,933
76,253
4.45 %
Other interest-bearing liabilities
615
12
7.20 %
486,736
3,273
2.69 %
24,180
589
9.74 %
Total interest-bearing liabilities
9,020,843
98,212
4.33 %
8,523,698
100,136
4.67 %
6,826,113
76,842
4.47 %
Non-interest bearing deposits
328,022
344,577
314,822
Other liabilities
251,239
225,467
238,806
Total liabilities
$ 9,600,104
$ 9,093,742
$ 7,379,741
Total equity
$ 1,335,730
$ 1,307,521
$ 1,221,425
Total liabilities and equity
$ 10,935,834
$ 10,401,263
$ 8,601,166
Interest rate spread
4.82 %
4.98 %
5.68 %
Net interest income and net interest margin
$ 142,384
5.42 %
$ 140,241
5.63 %
$ 131,477
6.40 %
(1)
Consolidated presentation reflects intercompany eliminations.
(2)
Nonaccrual loans and any related income are included in their respective loan categories.
(3)
The average balance for the fourth and third quarters of 2024 includes a loan portfolio that was purchased during the third quarter of 2024 of loans that we previously originated and sold.
LENDINGCLUB CORPORATION
CONSOLIDATED BALANCE SHEETS
(In Thousands, Except Share and Per Share Amounts)
(Unaudited)
December 31,
2024
December 31,
2023
Assets
Cash and due from banks
$ 15,524
$ 14,993
Interest-bearing deposits in banks
938,534
1,237,511
Total cash and cash equivalents
954,058
1,252,504
Restricted cash
23,338
41,644
Securities available for sale at fair value ($3,492,264 and $1,663,990 at amortized cost, respectively)
3,452,648
1,620,262
Loans held for sale at fair value
636,352
407,773
Loans and leases held for investment
4,125,818
4,850,302
Allowance for loan and lease losses
(236,734)
(310,387)
Loans and leases held for investment, net
3,889,084
4,539,915
Loans held for investment at fair value (1)
1,027,798
272,678
Property, equipment and software, net
167,532
161,517
Goodwill
75,717
75,717
Other assets
403,982
455,453
Total assets
$ 10,630,509
$ 8,827,463
Liabilities and Equity
Deposits:
Interest-bearing
$ 8,676,119
$ 7,001,680
Noninterest-bearing
392,118
331,806
Total deposits
9,068,237
7,333,486
Borrowings
—
19,354
Other liabilities
220,541
222,801
Total liabilities
9,288,778
7,575,641
Equity
Common stock, $0.01 par value; 180,000,000 shares authorized; 113,383,917 and 110,410,602 shares issued and outstanding, respectively
1,134
1,104
Additional paid-in capital
1,702,316
1,669,828
Accumulated deficit
(337,476)
(388,806)
Accumulated other comprehensive loss
(24,243)
(30,304)
Total equity
1,341,731
1,251,822
Total liabilities and equity
$ 10,630,509
$ 8,827,463
(1)
The balance at December 31, 2024 includes a loan portfolio that was purchased during the third quarter of 2024 of loans that we previously originated and sold.
LENDINGCLUB CORPORATION
RECONCILIATION OF GAAP TO NON-GAAP FINANCIAL MEASURES
(In thousands, except share and per share data)
(Unaudited)
Pre-Provision Net Revenue
For the three months ended
For the year ended
December 31,
2024
September 30,
2024
June 30,
2024
March 31,
2024
December 31,
2023
December 31,
2024
December 31,
2023
GAAP Net income
$ 9,720
$ 14,457
$ 14,903
$ 12,250
$ 10,155
$ 51,330
$ 38,939
Less: Provision for credit losses
(63,238)
(47,541)
(35,561)
(31,927)
(41,907)
(178,267)
(243,565)
Less: Income tax expense
(1,388)
(3,551)
(4,519)
(4,278)
(3,529)
(13,736)
(15,678)
Pre-provision net revenue
$ 74,346
$ 65,549
$ 54,983
$ 48,455
$ 55,591
$ 243,333
$ 298,182
For the three months ended
For the year ended
December 31,
2024
September 30,
2024
June 30,
2024
March 31,
2024
December 31,
2023
December 31,
2024
December 31,
2023
Non-interest income
$ 74,817
$ 61,640
$ 58,713
$ 57,800
$ 54,129
$ 252,970
$ 302,781
Net interest income
142,384
140,241
128,528
122,888
131,477
534,041
561,838
Total net revenue
217,201
201,881
187,241
180,688
185,606
787,011
864,619
Non-interest expense
(142,855)
(136,332)
(132,258)
(132,233)
(130,015)
(543,678)
(566,437)
Pre-provision net revenue
74,346
65,549
54,983
48,455
55,591
243,333
298,182
Provision for credit losses
(63,238)
(47,541)
(35,561)
(31,927)
(41,907)
(178,267)
(243,565)
Income before income tax expense
11,108
18,008
19,422
16,528
13,684
65,066
54,617
Income tax expense
(1,388)
(3,551)
(4,519)
(4,278)
(3,529)
(13,736)
(15,678)
GAAP Net income
$ 9,720
$ 14,457
$ 14,903
$ 12,250
$ 10,155
$ 51,330
$ 38,939
Tangible Book Value Per Common Share
December 31,
2024
September 30,
2024
June 30,
2024
March 31,
2024
December 31,
2023
GAAP common equity
$ 1,341,731
$ 1,342,895
$ 1,287,945
$ 1,266,286
$ 1,251,822
Less: Goodwill
(75,717)
(75,717)
(75,717)
(75,717)
(75,717)
Less: Customer relationship intangible assets
(8,586)
(9,439)
(10,293)
(11,165)
(12,135)
Tangible common equity
$ 1,257,428
$ 1,257,739
$ 1,201,935
$ 1,179,404
$ 1,163,970
Book value per common share
GAAP common equity
$ 1,341,731
$ 1,342,895
$ 1,287,945
$ 1,266,286
$ 1,251,822
Common shares issued and outstanding
113,383,917
112,401,990
111,812,215
111,120,415
110,410,602
Book value per common share
$ 11.83
$ 11.95
$ 11.52
$ 11.40
$ 11.34
Tangible book value per common share
Tangible common equity
$ 1,257,428
$ 1,257,739
$ 1,201,935
$ 1,179,404
$ 1,163,970
Common shares issued and outstanding
113,383,917
112,401,990
111,812,215
111,120,415
110,410,602
Tangible book value per common share
$ 11.09
$ 11.19
$ 10.75
$ 10.61
$ 10.54
LENDINGCLUB CORPORATION
RECONCILIATION OF GAAP TO NON-GAAP FINANCIAL MEASURES (Continued)
(In thousands, except ratios)
(Unaudited)
Return On Tangible Common Equity
For the three months ended
For the year ended
December 31,
2024
September 30,
2024
June 30,
2024
March 31,
2024
December 31,
2023
December 31,
2024
December 31,
2023
Average GAAP common equity
$ 1,335,730
$ 1,307,521
$ 1,266,608
$ 1,257,237
$ 1,221,425
$ 1,291,938
$ 1,204,050
Less: Average goodwill
(75,717)
(75,717)
(75,717)
(75,717)
(75,717)
(75,717)
(75,717)
Less: Average customer relationship intangible assets
(9,013)
(9,866)
(10,729)
(11,650)
(12,643)
(10,324)
(14,198)
Average tangible common equity
$ 1,251,000
$ 1,221,938
$ 1,180,162
$ 1,169,870
$ 1,133,065
$ 1,205,897
$ 1,114,135
Return on average equity
Annualized GAAP net income
$ 38,880
$ 57,828
$ 59,612
$ 49,000
$ 40,620
$ 51,330
$ 38,939
Average GAAP common equity
$ 1,335,730
$ 1,307,521
$ 1,266,608
$ 1,257,237
$ 1,221,425
$ 1,291,938
$ 1,204,050
Return on average equity
2.9 %
4.4 %
4.7 %
3.9 %
3.3 %
4.0 %
3.2 %
Return on tangible common equity
Annualized GAAP net income
$ 38,880
$ 57,828
$ 59,612
$ 49,000
$ 40,620
$ 51,330
$ 38,939
Average tangible common equity
$ 1,251,000
$ 1,221,938
$ 1,180,162
$ 1,169,870
$ 1,133,065
$ 1,205,897
$ 1,114,135
Return on tangible common equity
3.1 %
4.7 %
5.1 %
4.2 %
3.6 %
4.3 %
3.5 %
View original content to download multimedia:https://www.prnewswire.com/news-releases/lendingclub-reports-fourth-quarter-and-full-year-2024-results-302362517.html
SOURCE LendingClub Corporation

You may like

BEIJING, Oct. 18, 2026 /PRNewswire/ — An interview from China.org.cn with Wang Xiaohui and David Ferguson on the Long March:
Wang Xiaohui:
When you march toward your ideals but encounter repeated setbacks and failures, do you have the courage to pause, reflect on the path taken, and chart a new way forward?
David Ferguson:
If I continually encountered setbacks on the road to my ideals, I would stop and reflect seriously on whether my methods need adjusted or my direction needs corrected. This is a matter of being honest with oneself and honest about one’s shortcomings. Granted, this requires as much courage as setting out in the first place — because what you have to confront is not only the judgment of others, but your own ingrained reluctance to accept that you might have got it wrong.
Wang Xiaohui:
The waters of the Xiangjiang River ran crimson in the winter of 1934.
To cover the Red Army’s main force as they crossed the river, Chen Shuxiang, then Commander of the 34th Division of the Fifth Army Corps, led his troops to fight against vastly superior enemy forces until they ran out of ammunition and supplies. Severely wounded, Chen was captured alive. On the way to the enemy camp to be paraded for merit, Chen seized a moment of the enemy’s unawareness, tore his own intestines through his abdominal wound, and died a heroic death. He was only 29 years old.
The Battle of Xiangjiang River was the deadliest campaign for the Red Army since the start of the Long March. In less than two months, their troop strength plummeted from over 86,000 to just over 30,000.
At that critical moment, doubts and discontent among officers and soldiers with the military leadership peaked.
During the fights against the previous four Kuomintang (KMT) “encirclement” campaigns, the Red Army adopted Mao Zedong’s strategy of “luring the enemy in deep.” With flexible tactics in mobile warfare, the Red Army worked miracles of defeating superior enemies time and again. Yet, the tide turned completely during the KMT’s fifth “encirclement.”
At that time, the CPC was a branch of the Communist International (Comintern). After 1927, the Comintern instructed the CPC to adopt an urban-centered path in its revolution, for it was how Russia’s October Revolution had achieved victory. Affected by this directive, during the Fifth Counter-Campaign against “Encirclement and Suppression”, Bo Gu and Otto Braun, who held actual command of the Red Army, insisted on launching offensive operations to seize major cities.
Otto Braun also mechanically applied European conventional warfare tactics, forcing the Red Army into rigid positional and fortress battles. In the Battle of Guangchang, the poorly equipped Red Army fought head-on against enemy tanks and artillery on open terrain, resulting in more than 5,000 casualties, about one-fourth of all participating troops.
Successive military defeats forced the Red Army to launch a strategic shift. However, Bo Gu and Otto Braun insisted that everything be evacuated, including heavy equipment: printing presses, currency-making machines, and arms-manufacturing facilities… When crossing the Xiangjiang River, troops were slowed down by these cumbersome supplies, and numerous soldiers even laid down their lives for protecting these assets. Chen Shuxiang and his 34th Division wrote the gravest footnote to this bloody sacrifice.
By the banks of the Xiangjiang River, the spark of hope in the eyes of the Red Army soldiers was nearly quenched by the cold water. Could the rigid foreign doctrines truly guide the Red Army and China’s revolution? What path lay ahead?
History often unfolds in paradoxes: when all hope seems lost, a historical turning point is quietly emerging.
After the Battle of Xiangjiang River, Mao firmly opposed the original plan drafted by Bo Gu and Otto Braun to march towards Hunan. Instead, he proposed to advance to Guizhou where enemy defenses were weak. There, the Red Army broke through the natural barrier of the Wujiang River, and captured Zunyi. On Jan. 15, 1935, the CPC Central Committee convened an enlarged Political Bureau meeting in an old mansion, later known to the world as the Zunyi Conference.
Inside the modest living room on the second floor, a charcoal brazier expelled the winter chill. The CPC leadership sat around a long table to review why the Red Army had fallen into passive positions since 1933. Bo Gu attributed the defeats solely to the enemy’s overwhelming strength, while other leading officials like Zhou Enlai and Zhang Wentian pinpointed flawed military command as the fundamental cause.
Mao Zedong also made a pivotal speech.
As a revolutionary forged in rural base-area practice, Mao always sought truth from real combat experience. Citing victories from the previous four counter-“encirclement” campaigns, he rebutted Bo Gu’s opinions and criticized the flawed strategies of passive defense and abandoning mobile warfare tactics. In plain, incisive language, he pointed out that “the soldiers also needed to march, eat and sleep,” and that Braun’s rigid commands were completely divorced from the realities of China’s revolutionary warfare.
Throughout the whole meeting, Bo Gu remained dejected; Braun sat near the door and lit one cigarette after another. Never had these “true Bolsheviks” faced such rigorous criticism before.
The intensive confrontation lasted three days. In the end, Mao Zedong was elected to the leadership of the Red Army and the CPC Central Committee, putting an end to the wrong guidance. This marked a life-and-death turning point in the history of the Communist Party of China.
The Zunyi Conference freed the CPC from the Comintern’s intervention, enabling the Party to independently master the destiny of China’s revolution. From then on, the Red Army turned peril into safety, and China’s revolution emerged from despair toward new life.
David Ferguson:
When faced with major setbacks, the Communist Party of China was not crushed; instead, it demonstrated the courage to confront and correct its own mistakes, thereby turning adversity into opportunity. For any ruling party, this kind of courage is exceptionally rare.
Throughout history, guided by the principle of seeking truth from facts, the Party has always corrected errors, updated systems and adjusted course. By doing so, it has guaranteed social progress. This is precisely the secret to success that has made the Party resilient and invincible.
Wang Xiaohui:
No grand undertaking advances without setbacks. Faced with obstacles and defeats, the CPC demonstrated extraordinary courage and wisdom. They sought truth from facts, corrected wrong courses, and led the revolution towards triumph.
The Zunyi Conference Spirit, embodied in firm conviction, adherence to truth, independence and self-reliance, solidarity and unity, was forged amid blood and fire. It has shaped the unique spiritual character of the CPC. In the years that followed, these timeless values continued to evolve and sustain the Party in the face of trials and challenges, endowing it with enduring vitality.
China Mosaic
http://www.china.org.cn/video/node_7230027.htm
Faith: The Spark Born by the Yudu Riverside
http://www.china.org.cn/2026-10/17/content_118737624.shtml
View original content to download multimedia:https://www.prnewswire.com/news-releases/truth-seeking-the-turning-point-in-zunyi-302912139.html
SOURCE China.org.cn
Technology
GMIF2026: AI Inference Powers the “Token Factory” and Drives System-Level Rethinking of Memory & Storage
Published
6 minutes agoon
October 19, 2026By
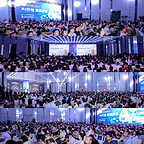
SHENZHEN, China, Oct. 18, 2026 /PRNewswire/ — The 5th GMIF Innovation Summit (Global Memory Innovation Forum 2026, GMIF2026) recently concluded at the Renaissance Shenzhen Bay Hotel. Co-hosted by the Shenzhen Memory Industry Association (SMIA) and the School of Integrated Circuits at Peking University, the summit was themed “The Future Built on AI Memory and Storage.” Now in its fifth edition, GMIF has grown from a regional industry gathering into a benchmark for the global semiconductor memory ecosystem, with diversified programs including keynote sessions, an investment forum, product exhibitions, a global livestream, and a golf friendship match, all centered on the value of memory and storage in the token economy and the AI inference era.
In the opening remarks by Rixin Sun, President of Shenzhen Memory Industry Association (SMIA), GMIF’s growth over five consecutive editions was traced from its early days to today. As a platform for global exchange, GMIF is built around the memory value chain, linking wafer IDMs and players in controllers, modules, packaging and testing, equipment and materials, and end applications to promote technical exchange, supply-demand matching, and ecosystem cooperation.
President Sun noted that as AI evolves from generative to agentic, inference efficiency, data scheduling, and system coordination have become shared priorities. Collaboration across the value chain is no longer a traditional supply-demand relationship, but a deeper partnership built around workload requirements, joint product definition, and scenario validation. Looking ahead, GMIF will pursue a more specialized and differentiated format, connecting memory companies with AI compute and end-application players worldwide.
Capital Meets Technology: Memory & Storage Moves to the Center of AI Infrastructure
As AI shifts from model training to large-scale commercial inference, the token is becoming a new unit of value. Inference demands low latency, high concurrency, and sustained throughput, which places memory and storage bandwidth, capacity, and energy efficiency among the variables that shape overall system efficiency and cost.
Daniel Yen of Morgan Stanley projected that global data center capital expenditure will stay strong in the coming years, with more than half of cloud data center capex expected to go to memory & storage (excluding HBM) by 2027. Yen identified six innovation paths to overcome the “memory wall” challenge: process migration, design changes, advanced packaging, memory peripherals, PIM/CIM, and new materials.
Prof. Yimao Cai, Dean of the School of Integrated Circuits at Peking University, pointed out that HBM remains central to high-end AI compute, but yield, cost, and thermal constraints limit broader adoption. NAND-based high-bandwidth technologies such as HBF have become a major research focus because of their cost advantage, and hybrid multi-media architectures could balance performance, capacity, and cost for deploying models with hundreds of billions of parameters.
Kevin Yoon, CVP & CTO of Samsung Memory China at Samsung Electronics, described how agents are generating massive KV cache demand and driving rapid iteration of tiered storage, citing Samsung’s work on Z-NAND, PCIe Gen6 SSDs, and ultra-high-capacity data center SSDs. Maya Zhang, Senior Director of Product Marketing from Sandisk, called this the first year of the “inference boom.” As inference reaches commercial scale, AI data centers are shifting from cost centers to value and capacity centers, and the evaluation framework is moving from TCO to TVO. NAND is becoming a strategic core component of AI, and the SSD is becoming a “token battery” that greatly improves the economics of the industry through token reuse.
Solidigm and Arm focused on the evolution of system-level design. Benny Ni, GAR Sales VP at Solidigm, noted high-capacity QLC SSDs are being adopted faster, and that memory offloading has moved from an alternative to a core design paradigm for data centers, while liquid cooling has become a prerequisite for unlocking high-end storage performance. John Xavier Lionel, Head of Global Storage Business at Arm, shared competition in the AI era is shifting from simply chasing higher TOPS to building a more efficient system balance among compute, memory, storage, and data movement. Arm’s cloud-edge-device continuum framework balances power, capacity, bandwidth, latency, security, and cost constraints at each tier, so that “the right AI workload runs in the right place.”
Moving from the cloud to the edge, Stanley Huang, AVP of Silicon Motion, stressed that devices are the ultimate carrier of AI experiences and that intelligent storage directly determines real-world device performance. Its PerformaShape technology allocates resources flexibly across different agents and greatly improves read/write consistency.
Sam Sun, Chairman of BIWIN, explained that large-scale AI inference is extending memory demand from data centers to the edge and endpoints, where differing needs in capacity, performance, power, size, and reliability are pushing storage from general-purpose specifications toward deep matching with specific scenarios and platforms. Drawing on full-stack capabilities from media selection and controller and firmware development to advanced packaging, testing, and volume delivery, BIWIN works closely with customers, platforms, and chip makers to tailor products to each use case, shortening development and validation cycles and improving system space, energy efficiency, and performance.
Token Factories Move Enterprise AI from Pilot to Production
As the token becomes the core unit of value, producing tokens efficiently and at low cost has become a shared challenge for enterprise AI adoption worldwide, and the “token factory” is emerging as a new industry paradigm. Tao Zhou, General Manager of the Server Division of Lenovo ISG China, said 80% of enterprises have deployed at least one type of agent, yet fewer than 40% of projects can scale and deliver positive ROI. Lenovo has built a full-stack “token factory” paradigm spanning data governance, compute optimization, and security management to address this.
A solid token factory depends on underlying storage media and architecture. Numbers Law’s PMD (Parallel Magnetic Drive) technology and NEXWISE‘s “KuberCloud” token factory solution contributed to full-stack capability from hardware to compute scheduling and model operations. Infplane, Maxio, and Genstoraige lowered the deployment threshold for large on-device models through AI SSD tiered offloading and memory expansion.
Real-world applications are also deepening. SYNCORE has achieved vehicle-cloud embodied intelligence across the whole vehicle. Dify, with its private agent architecture, and Paratera, with its MaaS compute service platform, are moving AI from basic compute supply toward deeper industry intelligence services, accelerating the industrialization of AI.
40 Companies Showcase the Core of the AI Memory & Storage Chain
The concurrent exhibition brought together 40 companies across the full value chain, from memory chips and controllers to compute servers, AIDC services, packaging and testing equipment, and system applications, presenting the latest advances in AI memory and storage from around the world.
Memory IDMs and controller makers led with new products. SanDisk featured its iNAND AT EU752 automotive UFS 4.1, SN861 enterprise NVMe SSD, and BiCS8 QLC NAND. Silicon Motion introduced the SM8466 PCIe Gen6 16-channel controller and the SM2524XT controller for edge SSDs. Maxio, YEESTOR, and other Chinese controller makers showed flagship PCIe Gen4/Gen5 and UFS controllers with enhanced LDPC, a sign that China’s controller portfolio is taking shape and benchmarking itself against leading international standards.
Compute and token factory solutions were another highlight. Lenovo exhibited its WenTian series of AI training-and-inference integrated servers. NEXWISE presented its full-stack token factory hardware and software, with heterogeneous compute management and token-based billing. Paratera showed its intelligent compute cloud and supercomputing cloud services, and Numbers Law demonstrated its PMD (Parallel Magnetic Drive) technology, aimed at sharply raising HDD IOPS and throughput. Infplane, Genstoraige, and Quanxing introduced KV cache offload and memory-fusion AI SSD solutions that use storage to share the compute load and significantly cut deployment costs.
Module makers and full-scenario solution providers brought a wide range of products. BIWIN exhibited enterprise SSDs, CXL products, wide-temperature industrial storage, and embedded products spanning AI cloud, edge, and device. KingSpec, POWEV, Topdisk, Barycn, Jielong Storage, HIKSEMI, and others presented industrial-grade, automotive-grade, server, and embedded product families, demonstrating strong volume production and reliable delivery.
Equipment, testing, and materials suppliers rounded out the floor. Attach Point, MICROVIEW, and Maxwell Technologies showed die attach and bonding equipment for 2.5D/3D advanced packaging. OKN Technology, Acroview Technology, Hongjingwei, and Tytantest introduced test and burn-in systems covering SSD, DRAM, and NAND that can accurately reproduce high-load AI I/O scenarios. Hemei Jingyi and Silergy brought storage IC package substrates and dedicated power management ICs. From advanced packaging equipment to test validation to core components, this supporting ecosystem lays the manufacturing foundation for volume production of AI memory and storage and for Chinese suppliers expanding overseas.
GMIF2026 Annual Awards Unveiled: Global Memory & Storage Leaders Build an Open, Collaborative Ecosystem
To recognize companies that have made outstanding contributions to the memory and storage value chain, the summit established the GMIF2026 Annual Awards, which cover memory, compute, packaging and testing equipment, test systems, and end applications across AI infrastructure, and were judged on technological innovation, industry contribution, market service, and real-world results.
Honorees, including Samsung Semiconductor, SanDisk, Solidigm, CXMT, Arm, Lenovo, Dify, Silicon Motion, Infplane, Genstoraige, Numbers Law, Paratera, SYNCORE, NEXWISE, Maxio Technology, BIWIN, Topdisk, KingSpec, POWEV, Quanxing Technology, OKN Technology, Attach Point, COMIX, Barycn, LKAUTO, Maxwell Technologies, Hemei Jingyi, Silergy, Heyan Technology, ExTripod Electronics, UNIMOS, GBAT, and Tytantest, were recognized for standout achievements in technology breakthroughs, product deployment, ecosystem building, and the industry chain.
Global Livestream and Golf Friendship Match Extend the Boundaries of Industry Cooperation
To join the global ecosystem and expand international cooperation, the summit featured a special Global Livestream by Memory Brands on LinkedIn, Facebook, and YouTube. Eight brands presented online: BIWIN, Silicon Motion, Quanxing Technology, OKN Technology, KingSpec, Maxwell Technologies, ExTripod Electronics, and Silergy. They gave overseas audiences a direct look at China’s latest advances in memory chips, advanced packaging, test systems, and other core AI infrastructure components, connecting technology standards, supply chain resources, and market demand across regions.
The momentum carried into the next day. The GMIF2026 “BIWIN Cup” golf friendship match, exclusively sponsored by BIWIN, brought senior executives from across the global memory value chain to the course. After a day of intensive discussion at the main forum, the setting was more relaxed, but the conversations among technology, capital, and markets carried on, helping speed practical cooperation across borders and sectors.
Conclusion
Across the GMIF program, one message stood out: global AI competition is moving beyond the “single-point era” of peak GPU performance into a “system-level era” that integrates storage, compute, networking, and software. In the token economy, memory and storage is shedding its auxiliary role and becoming the strategic foundation of AI inference.
This edition of GMIF brought together capital outlook, frontier technology, product innovation, real-world practice, and ecosystem collaboration, and, with the awards, livestream, and networking events, carried the conversation from ideas to product showcases, overseas exposure, and business deals. Going forward, GMIF will stay focused on the industry’s frontier issues and connect key players across the global memory value chain, promoting joint standards, technology development, and market expansion to open a new chapter for the AI memory and storage industry.
About GMIF
Global Memory Innovation Forum (GMIF) is a premier annual gathering that connects the global memory and storage community. Featuring diverse activities including keynote speeches, roundtable dialogues, supply-demand match-making, product showcases, industry rankings, awards programs, and global livestreaming, GMIF brings together key enterprises across the memory and storage chain, technical experts, terminal companies and investment institutions to exchange insights, build partnerships, and create business opportunities. Learn more about GMIF, please visit https://www.gmif.com.cn/. Follow us on LinkedIn, YouTube and Facebook.
Media Contact:
Carina Gu, wenjing.gu@gmif.com.cn
View original content to download multimedia:https://www.prnewswire.com/news-releases/gmif2026-ai-inference-powers-the-token-factory-and-drives-system-level-rethinking-of-memory–storage-302912123.html
SOURCE Shenzhen Memory Industry Association (SMIA)

Truth-seeking: the Turning Point in Zunyi
Truth-seeking: the Turning Point in Zunyi

GMIF2026: AI Inference Powers the “Token Factory” and Drives System-Level Rethinking of Memory & Storage

Send Rakhi to UK swiftly with UK Gifts Portal

Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

Nullmax and Renesas Forge Strategic Partnership to Deliver Competitive ADAS Solutions for the Global Market

Why You Should Build on #NEAR – Co-founder Illia Polosukhin at CV Labs
Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

NEAR End of Year Town Hall 2021: The Open Web World, MetaBUILD 2 Hackathon and 2021 recap
Trending
-
 Coin Market5 days ago
‘Bunker mode’ won’t protect your crypto, critics say
-
 Technology5 days ago
Solidion Technology Reaffirms Commitment to Address Growing Energy Storage Needs of AI Data Centers
-
 Technology5 days ago
TVU Networks to Showcase Connected Live Video Ecosystem at Broadcast India Show 2026
-
 Technology5 days ago
PEGATRON Brings AI Infrastructure from Design to Deployment at OCP Global Summit 2026
-
 Coin Market4 days ago
Organizations join forces to fight Illinois crypto tax, after 6-month pause
-
 Technology5 days ago
SUS ENVIRONMENT Draws International Attention for Transforming Waste-to-Energy Plants into Sustainable Urban Assets
-
 Coin Market5 days ago
Can crypto users trust the supply chain behind hardware wallets?
-
 Technology5 days ago
A $2.1 Trillion Wellness Industry Never Built a Daily Practice for Black Children. So This Atlanta Family Did.