
Technology
goeasy Ltd. Reports Results for the First Quarter

Published
1 year agoon
By

Loan Portfolio of $4.79 billion, up 24% from $3.85 billion
Revenue of $392 million, up 10% from $357 million
Net Charge Off Rate of 8.9%, down 20 bps from 9.1%
Operating Income of $145 million; Adjusted Operating Income of $148 million, up 3% from $144 million
Diluted EPS of $2.32; Adjusted Diluted EPS1 of $3.53, down 8% from $3.83
MISSISSAUGA, ON, May 7, 2025 /CNW/ – goeasy Ltd. (TSX: GSY), (“goeasy” or the “Company”), one of Canada’s leading consumer lenders focused on delivering a full suite of financial services to Canadians with non-prime credit, today reported results for the first quarter ended March 31, 2025.
First Quarter Results
During the quarter, the Company generated $677 million in loan originations, down 1% compared to $686 million produced in the first quarter of 2024. The loan originations were driven by continued strength in the volume of applications for credit, which were up 10% over the prior year. The Company experienced strong performance across several product and acquisition channels, including home equity lending, point-of-sale and automotive financing.
Loan originations during the quarter led to growth in the loan portfolio of $190 million, above the Company’s forecasted range of between $160 million and $185 million. At quarter end, the consumer loan portfolio was $4.79 billion, up 24% from $3.85 billion in the first quarter of 2024. The growth in consumer loans led to an increase in revenue to $392 million, up 10% from $357 million in the first quarter of last year. Interest income increased year over year by $36 million or 14%.
During the quarter, the Company continued to experience stable credit and payment performance. The annualized net charge off rate was 8.9%, down 20 bps from 9.1% in the first quarter of 2024, and within the Company’s forecasted range of between 8.75% and 9.75% for the quarter. The Company’s allowance for future credit losses increased to 7.86%, compared to 7.61% in the fourth quarter of 2024, due to weaker macroeconomic performance and unfavourable changes in forward looking macroeconomic indicators produced by Moody’s Analytics.
Operating income for the first quarter of 2025 was $145 million, up 5% from $138 million in the first quarter of 2024. Operating margin for the first quarter was 37.0%, down slightly from 38.6% in the same period last year. After adjusting for unusual and non-recurring items, the Company reported adjusted operating income2 of $148 million, an increase of 3% compared to $144 million in the first quarter of 2024. Adjusted operating margin1 for the first quarter was 37.9%, down from 40.2% in the same period in 2024. The efficiency ratio1 for the first quarter of 2025 was 26.1%, an improvement of 130 bps from 27.4% in the first quarter of 2024, reflecting an increase in operating leverage.
Net income in the first quarter was $39.4 million, down from $58.9 million in the same period of 2024, which resulted in diluted earnings per share of $2.32, down from the $3.40 reported in the first quarter of 2024. After adjustments related primarily to the non-cash fair value change on prepayment options related to notes payable, adjusted net income2 was $60.0 million, down 9% from $66.3 million in the first quarter of 2024, primarily due to a decline in total yield on consumer loans (including ancillary products) as well as the increase in allowance for future credit losses as a result of weaker macroeconomic performance and unfavourable changes in forward looking macroeconomic indicators. Adjusted diluted earnings per share1 was $3.53, down 8% from $3.83 in the first quarter of 2024. Return on equity during the quarter was 13.4%, compared to 21.9% in the first quarter of 2024. Adjusted return on equity1 was 20.4% in the quarter, compared to 24.6% in the same period of 2024.
“During the quarter we were proud to serve 43,500 new customers, while producing $190 million in portfolio growth, highlighting the critical role we play in providing everyday Canadians access to credit,” said David Ingram, goeasy’s Executive Chairman, “Our results continued to demonstrate the resilience of our business model during periods of macroeconomic uncertainty. We also bolstered our balance sheet and liquidity, with $565 million of new capital, lifting our funding capacity to $2.0 billion to support our organic growth plans. With the increased level of liquidity and conservative leverage profile, we also repurchased approximately $96 million in shares during and subsequent to quarter-end,” Mr. Ingram continued, “While the total yield in the quarter was at the lower end of our forecasted range, we are addressing through product, pricing and collections optimization efforts and remain on track to achieving all of our forecasted metrics for 2025.”
Other Key First Quarter Highlights
easyfinancial
Revenue of $355 million, up 12%46% of the loan portfolio secured, up from 43%Strong volume of applications for credit, up 10%New customer volume at 43,500, up 8%73% of net loan advances1 in the quarter were issued to new customers, up from 69%Strong volume of originations in automotive financing, up 30%Average loan book per branch3 improved to a record $7.2 million, an increase of 20%Weighted average interest rate3 on consumer loans of 28.4%, down from 30.0%Operating income of $157 million, up 1%
easyhome
Revenue of $37.0 million, down slightly from $39.1 millionConsumer loan portfolio within easyhome stores increased to $125.8 million, up 17%Financial revenue2 from consumer lending increased to $13.5 million, up 6%Operating income of $9.5 million, down 16%
Overall
95th consecutive quarter of positive net income2025 marks the 21st consecutive year of paying dividends and the 11th consecutive year of a dividend increase60th consecutive quarter of same store revenue growthTotal customers served over 1.5 million since easyfinancial’s inceptionAcquired and organically originated over $16.6 billion in loans since easyfinancial’s inceptionAdjusted return on equity1 of 20.4%, down from 24.6%Fully drawn weighted average cost of borrowing at 6.3%, down from 6.8%Debt to adjusted tangible equity4 of 3.53x on March 31, 2025
Balance Sheet and Liquidity
Total assets were $5.33 billion as of March 31, 2025, an increase of 21% from $4.42 billion as of March 31, 2024, primarily driven by growth in the consumer loan portfolio.
Subsequent to quarter-end, the Company issued US$400 million aggregate principal amount of senior unsecured notes due 2030 (the “Notes”). In connection with the offering, the Company entered into a currency swap agreement (the “Currency Swap”) to reduce the Canadian dollar equivalent cost of borrowing on the Notes to 6.03% per annum. Before giving effect to the Currency Swap, the coupon on the Notes is 7.375% per annum. The Company used the net proceeds from the sale of the Notes to partially repay indebtedness under its secured facilities and for general corporate purposes.
Free cash flow from operations before net growth in gross consumer loans receivable2 in the quarter was $31 million compared to $77 million in the first quarter of 2024. Based on the cash on hand at the end of the quarter and the borrowing capacity under the Company’s existing revolving credit facilities, including the aforementioned Notes offering completed following the quarter, the Company has approximately $2.0 billion in total funding capacity as of May 1, 2025 and a debt to adjusted tangible equity ratio of 3.53x as of March 31, 2025. The Company remains confident that the capacity available under its existing funding facilities, and its ability to raise additional debt financing, is sufficient to fund its organic growth forecast.
At quarter-end, the Company’s weighted average cost of borrowing was 6.8%, and the fully drawn weighted average cost of borrowing was 6.3%. The Company estimates that it could currently grow the consumer loan portfolio by approximately $300 million per year solely from internal cash flows, without utilizing external debt. The Company also estimates that once its existing and available sources of debt are fully utilized, it could continue to grow the loan portfolio by approximately $500 million per year solely from internal cash flows.
Dividend
The Board of Directors has approved a quarterly dividend of $1.46 per share payable on July 11, 2025 to the holders of common shares of record as at the close of business on June 27, 2025.
Forward-Looking Statements
All figures reported above with respect to outlook are targets established by the Company and are subject to change as plans and business conditions vary. Accordingly, investors are cautioned not to place undue reliance on the foregoing guidance. Actual results may differ materially.
This press release includes forward-looking statements about goeasy, including, but not limited to, its business operations, strategy and expected financial performance and condition. Forward-looking statements include, but are not limited to, statements with respect to forecasts for growth of the consumer loans receivable, annual revenue growth forecasts, strategic initiatives, new product offerings and new delivery channels, anticipated cost savings, planned capital expenditures, anticipated capital requirements and the Company’s ability to secure sufficient capital, liquidity of the Company, plans and references to future operations and results, critical accounting estimates, expected future yields and net charge off rates on loans, the dealer relationships, the size and characteristics of the Canadian non-prime lending market and the continued development of the type and size of competitors in the market. In certain cases, forward-looking statements that are predictive in nature, depend upon or refer to future events or conditions, and/or can be identified by the use of words such as “expect”, “continue”, “anticipate”, “intend”, “aim”, “plan”, “believe”, “budget”, “estimate”, “forecast”, “foresee”, “target” or negative versions thereof and similar expressions, and/or state that certain actions, events or results “may”, “could”, “would”, “might” or “will” be taken, occur or be achieved.
Forward-looking statements are based on certain factors and assumptions, including expected growth, results of operations and business prospects and are inherently subject to, among other things, risks, uncertainties and assumptions about the Company’s operations, economic factors and the industry generally. There can be no assurance that forward-looking statements will prove to be accurate as actual results and future events could differ materially from those expressed or implied by forward-looking statements made by the Company. Some important factors that could cause actual results to differ materially from those expressed in the forward-looking statements include, but are not limited to, goeasy’s ability to enter into new lease and/or financing agreements, collect on existing lease and/or financing agreements, open new locations on favourable terms, offer products which appeal to customers at a competitive rate, respond to changes in legislation, react to uncertainties related to regulatory action, raise capital under favourable terms, compete, manage the impact of litigation (including shareholder litigation), control costs at all levels of the organization and maintain and enhance the system of internal controls.
The Company cautions that the foregoing list is not exhaustive. These and other factors could cause actual results to differ materially from our expectations expressed in the forward-looking statements, and further details and descriptions of these and other factors are disclosed in the Company’s Management’s Discussion and Analysis (“MD&A”), including under the section entitled “Risk Factors”.
The reader is cautioned to consider these, and other factors carefully and not to place undue reliance on forward-looking statements, which may not be appropriate for other purposes. The Company is under no obligation (and expressly disclaims any such obligation) to update or alter the forward-looking statements whether as a result of new information, future events or otherwise, unless required by law.
About goeasy
goeasy Ltd. is a Canadian company, headquartered in Mississauga, Ontario, that provides non-prime leasing and lending services through its easyhome, easyfinancial and LendCare brands. Supported by over 2,600 employees, the Company offers a wide variety of financial products and services including unsecured and secured instalment loans, merchant financing through a variety of verticals and lease-to-own merchandise. Customers can transact seamlessly through an omni-channel model that includes online and mobile platforms, over 400 locations across Canada, and point-of-sale financing offered in the retail, powersports, automotive, home improvement and healthcare verticals, through approximately 11,000 merchant partners across Canada. Throughout the Company’s history, it has acquired and organically served over 1.5 million Canadians and originated over $16.6 billion in loans.
Accredited by the Better Business Bureau, goeasy is the proud recipient of several awards in recognition of its exceptional culture and continued business growth including 2024 Best Workplaces™ in Financial Services & Insurance, Waterstone Canada’s Most Admired Corporate Cultures, ranking on the 2022 Report on Business Women Lead Here executive gender diversity benchmark, placing on the 2024 Report on Business ranking of Canada’s Top Growing Companies, ranking on the TSX30, Greater Toronto Top Employers Award and has been certified as a Great Place to Work®. The Company is represented by a diverse group of team members from over 90 nationalities who believe strongly in giving back to communities in which it operates. To date, goeasy has raised and donated over $6.5 million to support its long-standing partnerships with BGC Canada and many other local charities.
goeasy Ltd.’s. common shares are listed on the TSX under the trading symbol “GSY”. goeasy is rated BB- with a stable trend from S&P and Ba3 with a stable trend from Moody’s.
For more information about goeasy and our business units, visit www.goeasy.com, www.easyfinancial.com, www.lendcare.ca, www.easyhome.ca.
For further information contact:
Farhan Ali Khan
Executive Vice President & Chief Strategy and Corporate Development Officer
(905) 272-2788
Notes:
1 These are non-IFRS ratios. Refer to “Non-IFRS Measures and Other Financial Measures” section in this press release.
2 These are non-IFRS measures. Refer to “Non-IFRS Measures and Other Financial Measures” section in this press release.
3 These are supplementary financial measures. Refer to “Non-IFRS Measures and Other Financial Measures” section in this press release.
4 These are capital management measures. Refer to “Non-IFRS Measures and Other Financial Measures” section in this press release.
5 Non-IFRS ratios, non-IFRS measures, supplementary financial measures and capital management measures are not determined in accordance with IFRS, do not have standardized meanings and may not be comparable to similar financial measures presented by other companies.
goeasy Ltd.
INTERIM CONDENSED CONSOLIDATED STATEMENTS OF FINANCIAL POSITION
(Unaudited)
(Expressed in thousands of Canadian dollars)
As At
As At
March 31,
December 31,
2025
2024
ASSETS
Cash
180,832
251,381
Accounts receivable
41,918
42,438
Prepaid expenses
15,000
9,488
Consumer loans receivable, net
4,555,358
4,366,533
Investments
41,918
41,918
Lease assets
38,665
40,973
Derivative financial assets
73,773
60,675
Deferred income tax assets, net
7,749
–
Property and equipment, net
33,579
35,004
Right-of-use assets, net
52,732
54,224
Intangible assets, net
107,080
110,979
Goodwill
180,923
180,923
TOTAL ASSETS
5,329,527
5,194,536
LIABILITIES AND SHAREHOLDERS’ EQUITY
Liabilities
Revolving credit facility
164,610
21,797
Accounts payable and other liabilities
126,457
156,903
Income taxes payable
5,928
24,567
Dividends payable
23,717
19,519
Unearned revenue
25,710
25,864
Accrued interest payable
62,543
49,003
Deferred income tax liabilities, net
–
4,184
Lease liabilities
60,495
62,164
Secured borrowings
107,402
120,335
Revolving securitization warehouse facilities
1,134,628
1,073,876
Derivative financial liabilities
25,481
21,466
Notes payable
2,440,141
2,413,795
TOTAL LIABILITIES
4,177,112
3,993,473
Shareholders’ equity
Share capital
428,142
438,302
Contributed surplus
29,223
26,942
Accumulated other comprehensive loss
(52,612)
(56,938)
Retained earnings
747,662
792,757
TOTAL SHAREHOLDERS’ EQUITY
1,152,415
1,201,063
TOTAL LIABILITIES AND SHAREHOLDERS’ EQUITY
5,329,527
5,194,536
goeasy Ltd.
INTERIM CONDENSED CONSOLIDATED STATEMENTS OF INCOME
(Unaudited)
(Expressed in thousands of Canadian dollars, except earnings per share)
Three Months Ended
March 31,
March 31,
2025
2024
REVENUE
Interest income
295,829
260,072
Lease revenue
22,242
24,741
Commissions earned
68,187
63,964
Charges and fees
5,603
8,337
391,861
357,114
OPERATING EXPENSES
BAD DEBTS
131,023
105,195
OTHER OPERATING EXPENSES
Salaries and benefits
49,463
52,450
Share-based compensation
4,441
4,252
Technology costs
12,220
8,340
Advertising and promotion
8,686
7,774
Underwriting and collections
7,162
4,702
Occupancy
5,672
5,326
Other expenses
7,681
10,486
95,325
93,330
DEPRECIATION AND AMORTIZATION
Depreciation of lease assets
6,983
7,080
Amortization of intangible assets
5,646
5,842
Depreciation of right-of-use assets
5,297
5,406
Depreciation of property and equipment
2,597
2,550
20,523
20,878
TOTAL OPERATING EXPENSES
246,871
219,403
OPERATING INCOME
144,990
137,711
OTHER LOSS
–
(4,398)
FINANCE COSTS
(89,651)
(51,313)
INCOME BEFORE INCOME TAXES
55,339
82,000
INCOME TAX EXPENSE (RECOVERY)
Current
30,966
24,857
Deferred
(15,026)
(1,801)
15,940
23,056
NET INCOME
39,399
58,944
BASIC EARNINGS PER SHARE
2.35
3.46
DILUTED EARNINGS PER SHARE
2.32
3.40
SUMMARY OF FINANCIAL RESULTS BY REPORTABLE SEGMENT
(Expressed in thousands of Canadian dollars, except earnings per share)
Three Months Ended March 31, 2025
easyfinancial
easyhome
Corporate
Total
Revenue
Interest income
285,346
10,483
–
295,829
Lease revenue
–
22,242
–
22,242
Commissions earned
64,625
3,562
–
68,187
Charges and fees
4,848
755
–
5,603
354,819
37,042
–
391,861
Operating expenses
Bad debts
126,467
4,556
–
131,023
Other operating expenses
61,526
13,925
19,874
95,325
Depreciation and amortization
9,736
9,063
1,724
20,523
197,729
27,544
21,598
246,871
Operating income (loss)
157,090
9,498
(21,598)
144,990
Other income
–
Finance costs
(89,651)
Income before income taxes
55,339
Income taxes
15,940
Net income
39,399
Diluted earnings per share
2.32
Three Months Ended March 31, 2024
easyfinancial
easyhome
Corporate
Total
Revenue
Interest income
250,139
9,933
–
260,072
Lease revenue
–
24,741
–
24,741
Commissions earned
60,494
3,470
–
63,964
Charges and fees
7,423
914
–
8,337
318,056
39,058
–
357,114
Operating expenses
Bad debts
101,303
3,892
–
105,195
Other operating expenses
52,011
14,562
26,757
93,330
Depreciation and amortization
9,875
9,283
1,720
20,878
163,189
27,737
28,477
219,403
Operating income (loss)
154,867
11,321
(28,477)
137,711
Other loss
(4,398)
Finance costs
(51,313)
Income before income taxes
82,000
Income taxes
23,056
Net income
58,944
Diluted earnings per share
3.40
SUMMARY OF FINANCIAL RESULTS AND KEY PERFORMANCE INDICATORS
(Expressed in thousands of Canadian dollars, except earnings per share and percentages)
Three Months Ended
March 31,
March 31,
Variance
Variance
2025
2024
$ / bps
% change
Summary Financial Results
Revenue
391,861
357,114
34,747
9.7 %
Bad debts
131,023
105,195
25,828
24.6 %
Other operating expenses
95,325
93,330
1,995
2.1 %
EBITDA1
158,530
147,111
11,419
7.8 %
EBITDA margin1
40.5 %
41.2 %
(70 bps)
(1.7 %)
Depreciation and amortization
20,523
20,878
(355)
(1.7 %)
Operating income
144,990
137,711
7,279
5.3 %
Operating margin
37.0 %
38.6 %
(160 bps)
(4.1 %)
Other loss
–
(4,398)
4,398
(100.0 %)
Finance costs
89,651
51,313
38,338
74.7 %
Effective income tax rate
28.8 %
28.1 %
70 bps
2.5 %
Net income
39,399
58,944
(19,545)
(33.2 %)
Diluted earnings per share
2.32
3.40
(1.08)
(31.8 %)
Return on receivables
3.3 %
6.2 %
(290 bps)
(46.8 %)
Return on assets
3.0 %
5.5 %
(250 bps)
(45.5 %)
Return on equity
13.4 %
21.9 %
(850 bps)
(38.8 %)
Return on tangible common equity1
17.9 %
29.6 %
(1,170 bps)
(39.5 %)
Adjusted Financial Results1
Other operating expenses
102,216
97,685
4,531
4.6 %
Efficiency ratio
26.1 %
27.4 %
(130 bps)
(4.7 %)
Operating income
148,357
143,711
4,646
3.2 %
Operating margin
37.9 %
40.2 %
(230 bps)
(5.7 %)
Net income
60,039
66,288
(6,249)
(9.4 %)
Diluted earnings per share
3.53
3.83
(0.30)
(7.8 %)
Return on receivables
5.1 %
7.0 %
(190 bps)
(27.1 %)
Return on assets
4.6 %
6.2 %
(160 bps)
(25.8 %)
Return on equity
20.4 %
24.6 %
(420 bps)
(17.1 %)
Return on tangible common equity
25.7 %
32.0 %
(630 bps)
(19.7 %)
Key Performance Indicators
Segment Financials
easyfinancial revenue
354,819
318,056
36,763
11.6 %
easyfinancial operating margin
44.3 %
48.7 %
(440 bps)
(9.0 %)
easyhome revenue
37,042
39,058
(2,016)
(5.2 %)
easyhome operating margin
25.6 %
29.0 %
(340 bps)
(11.7 %)
Portfolio Indicators
Gross consumer loans receivable
4,786,525
3,852,079
934,446
24.3 %
Growth in consumer loans receivable
190,410
206,877
(16,467)
(8.0 %)
Gross loan originations
676,770
686,433
(9,663)
(1.4 %)
Total yield on consumer loans (including ancillary products)1
31.3 %
35.0 %
(370 bps)
(10.6 %)
Net charge offs as a percentage of average gross consumer loans receivable
8.9 %
9.1 %
(20 bps)
(2.2 %)
Free cash flows from operations before net growth in gross consumer loans receivable1
31,240
77,142
(45,902)
(59.5 %)
Potential monthly leasing revenue1
6,727
7,377
(650)
(8.8 %)
1 EBITDA, adjusted other operating expenses, adjusted operating income, adjusted net income and free cash flows from operations before net growth in gross consumer loans receivable are non-IFRS measures. EBITDA margin, efficiency ratio, adjusted operating margin, adjusted diluted earnings per share, adjusted return on equity, adjusted return on receivable, adjusted return on assets, reported and adjusted return on tangible common equity and total yield on consumer loans (including ancillary products) are non-IFRS ratios. Refer to “Non-IFRS Measures and Other Financial Measures” section in this press release.
Non-IFRS Measures and Other Financial Measures
The Company uses a number of financial measures to assess its performance. Some of these measures are not calculated in accordance with International Financial Reporting Standards (IFRS) as issued by International Accounting Standards Board (IASB), are not identified by IFRS and do not have standardized meanings that would ensure consistency and comparability among companies using these measures. The Company believes that non-IFRS measures are useful in assessing ongoing business performance and provide readers with a better understanding of how management assesses performance. These non-IFRS measures are used throughout this press release and listed below. An explanation of the composition of non-IFRS measures and other financial measures can be found in the Company’s MD&A, available on www.sedarplus.ca.
Adjusted Net Income and Adjusted Diluted Earnings Per Share
Adjusted net income is a non-IFRS measure and adjusted diluted earnings per share is a non-IFRS ratio. Refer to “Key Performance Indicators and Non-IFRS Measures” section on page 24 of the Company’s MD&A for the three-month period ended March 31, 2025. Items used to calculate adjusted net income and adjusted earnings per share for the three-month periods ended March 31, 2025 and 2024 include those indicated in the chart below:
Three Months Ended
($ in 000’s except earnings per share)
March 31,
2025
March 31,
2024
Net income as stated
39,399
58,944
Impact of adjusting items
Other operating expenses
Integration costs1
92
182
Advisory costs3
–
2,543
Depreciation and amortization
Amortization of acquired intangible assets2
3,275
3,275
Other loss4
–
4,398
Finance costs
Fair value change on prepayment options related to Notes Payable5
24,714
(1,198)
Total pre-tax impact of adjusting items
28,081
9,200
Income tax impact of above adjusting items
(7,441)
(1,856)
After-tax impact of adjusting items
20,640
7,344
Adjusted net income
60,039
66,288
Weighted average number of diluted shares outstanding
17,007
17,319
Diluted earnings per share as stated
2.32
3.40
Per share impact of adjusting items
1.21
(0.43)
Adjusted diluted earnings per share
3.53
3.83
Adjusting items related to the LendCare acquisition
1
Integration costs related to representation and warranty insurance costs, and other integration costs related to the acquisition of LendCare.
2
Amortization of the $131 million intangible asset related to the acquisition of LendCare with an estimated useful life of ten years.
Adjusting items related to the advisory costs
3
Advisory costs for the three-month period ended March 31, 2024 were related to non-recurring advisory, consulting and legal costs.
Adjusting item related to other income
4
For the three-month period ended March 31, 2024, net investment loss was due to fair value changes in the Company’s investments.
Adjusting item related to prepayment options embedded in the Notes Payable
5
For the three-month periods ended March 31, 2025 and 2024, the Company recognized a fair value change on the prepayment options related to Notes Payable.
Adjusted Other Operating Expenses and Efficiency Ratio
Adjusted other operating expenses is a non-IFRS measure and efficiency ratio is a non-IFRS ratio. Refer to “Key Performance Indicators and Non-IFRS Measures” section on page 24 of the Company’s MD&A for the three-month period ended March 31, 2025. Items used to calculate adjusted other operating expenses and efficiency ratio for the three-month periods ended March 31, 2025 and 2024 include those indicated in the chart below:
Three Months Ended
($ in 000’s except earnings per share)
March 31,
2025
March 31,
2024
Other operating expenses as stated
95,325
93,330
Impact of adjusting items1
Other operating expenses
Integration costs
(92)
(182)
Advisory costs
–
(2,543)
Depreciation and amortization
Depreciation of lease assets
6,983
7,080
Total impact of adjusting items
102,216
4,355
Adjusted other operating expenses
102,216
97,685
Total revenue
391,861
357,114
Efficiency ratio
26.1 %
27.4 %
1
For explanation of adjusting items, refer to the corresponding “Adjusted Net Income and Adjusted Diluted Earnings Per Share” section.
Adjusted Operating Margin
Adjusted operating income is a non-IFRS measure and adjusted operating margin is a non-IFRS ratio. Refer to “Key Performance Indicators and Non-IFRS Measures” section on page 24 of the Company’s MD&A for the three-month period ended March 31, 2025. Items used to calculate adjusted operating income and adjusted operating margins for the three-month periods ended March 31, 2025 and 2024 include those indicated in the chart below:
Three Months Ended
($ in 000’s except percentages)
March 31,
2025
March 31,
2025
(adjusted)
March 31,
2024
March 31,
2024
(adjusted)
easyfinancial
Operating income
157,090
157,090
154,867
154,867
Divided by revenue
354,819
354,819
318,056
318,056
easyfinancial operating margin
44.3 %
44.3 %
48.7 %
48.7 %
easyhome
Operating income
9,498
9,498
11,321
11,321
Divided by revenue
37,042
37,042
39,058
39,058
easyhome operating margin
25.6 %
25.6 %
29.0 %
29.0 %
Total
Operating income
144,990
144,990
137,711
137,711
Other operating expenses1
Integration costs
–
92
–
182
Advisory costs
–
–
–
2,543
Depreciation and amortization1
Amortization of acquired intangible assets
–
3,275
–
3,275
Adjusted operating income
144,990
148,357
137,711
143,711
Divided by revenue
391,861
391,861
357,114
357,114
Total operating margin
37.0 %
37.9 %
38.6 %
40.2 %
1
For explanation of adjusting items, refer to the corresponding “Adjusted Net Income and Adjusted Diluted Earnings Per Share” section.
Earnings before Interest, Taxes, Depreciation and Amortization (“EBITDA”) and EBITDA Margin
EBITDA is a non-IFRS measure and EBITDA margin is a non-IFRS ratio. Refer to “Key Performance Indicators and Non-IFRS Measures” section on page 24 of the Company’s MD&A for the three-month period ended March 31, 2025. Items used to calculate EBITDA and EBITDA margin for the three-month periods ended March 31, 2025 and 2024 include those indicated in the chart below:
Three Months Ended
($ in 000’s except percentages)
March 31,
2025
March 31,
2024
Net income as stated
39,399
58,944
Finance cost
89,651
51,313
Income tax expense
15,940
23,056
Depreciation and amortization
20,523
20,878
Depreciation of lease assets
(6,983)
(7,080)
EBITDA
158,530
147,111
Divided by revenue
391,861
357,114
EBITDA margin
40.5 %
41.2 %
Free Cash Flow from Operations before Net Growth in Gross Consumer Loans Receivable
Free cash flow from operations before net growth in gross consumer loans receivable is a non-IFRS measure. Refer to “Key Performance Indicators and Non-IFRS Measures” section on page 24 of the Company’s MD&A for the three-month period ended March 31, 2025. Items used to calculate free cash flow from operations before net growth in gross consumer loans receivable for the three-month periods ended March 31, 2025 and 2024 include those indicated in the chart below:
Three Months Ended
March 31,
2025
March 31,
2024
Cash used in operating activities
(159,170)
(129,735)
Net growth in gross consumer loans receivable during the period
190,410
206,877
Free cash flows from operations before net growth in gross consumer loans receivable
31,240
77,142
Adjusted Return on Receivables
Adjusted return on receivables is a non-IFRS ratio. Refer to “Key Performance Indicators and Non-IFRS Measures” section on page 24 of the Company’s MD&A for the three-month period ended March 31, 2025. Items used to calculate adjusted return on assets for the three-month periods ended March 31, 2025 and 2024 include those indicated in the chart below:
Three Months Ended
($ in 000’s except percentages)
March 31,
2025
March 31,
2025
(adjusted)
March 31,
2024
March 31,
2024
(adjusted)
Net income as stated
39,399
39,399
58,944
58,944
After-tax impact of adjusting items1
–
20,640
–
7,344
Adjusted net income
39,399
60,039
58,944
66,288
Multiplied by number of periods in a year
X 4
X 4
X 4
X 4
Divided by average gross consumer loans receivable
4,709,745
4,709,745
3,778,309
3,778,309
Return on receivables
3.3 %
5.1 %
6.2 %
7.0 %
1
For explanation of adjusting items, refer to the corresponding “Adjusted Net Income and Adjusted Diluted Earnings Per Share” section.
Adjusted Return on Assets
Adjusted return on assets is a non-IFRS ratio. Refer to “Key Performance Indicators and Non-IFRS Measures” section on page 24 of the Company’s MD&A for the three-month period ended March 31, 2025. Items used to calculate adjusted return on assets for the three-month periods ended March 31, 2025 and 2024 include those indicated in the chart below:
Three Months Ended
($ in 000’s except percentages)
March 31,
2025
March 31,
2025
(adjusted)
March 31,
2024
March 31,
2024
(adjusted)
Net income as stated
39,399
39,399
58,944
58,944
After-tax impact of adjusting items1
–
20,640
–
7,344
Adjusted net income
39,399
60,039
58,944
66,288
Multiplied by number of periods in a year
X 4
X 4
X 4
X 4
Divided by average total assets for the period
5,262,032
5,262,032
4,290,098
4,290,098
Return on assets
3.0 %
4.6 %
5.5 %
6.2 %
1
For explanation of adjusting items, refer to the corresponding “Adjusted Net Income and Adjusted Diluted Earnings Per Share” section.
Adjusted Return on Equity
Adjusted return on equity is a non-IFRS ratio. Refer to “Key Performance Indicators and Non-IFRS Measures” section on page 24 of the Company’s MD&A for the three-month period ended March 31, 2025. Items used to calculate adjusted return on equity for the three-month periods ended March 31, 2025 and 2024 include those indicated in the chart below:
Three Months Ended
($ in 000’s except percentages)
March 31,
2025
March 31,
2025
(adjusted)
March 31,
2024
March 31,
2024
(adjusted)
Net income as stated
39,399
39,399
58,944
58,944
After-tax impact of adjusting items1
–
20,640
–
7,344
Adjusted net income
39,399
60,039
58,944
66,288
Multiplied by number of periods in a year
X 4
X 4
X 4
X 4
Divided by average shareholders’ equity for the period
1,176,739
1,176,739
1,078,662
1,078,662
Return on equity
13.4 %
20.4 %
21.9 %
24.6 %
1
For explanation of adjusting items, refer to the corresponding “Adjusted Net Income and Adjusted Diluted Earnings Per Share” section.
Reported and Adjusted Return on Tangible Common Equity
Reported and adjusted return on tangible common equity are non-IFRS ratios. Refer to “Key Performance Indicators and Non-IFRS Measures” section on page 24 of the Company’s MD&A for the three-month period ended March 31, 2025. Items used to calculate reported and adjusted return on tangible common equity for the three-month periods ended March 31, 2025 and 2024 include those indicated in the chart below:
Three Months Ended
($ in 000’s except percentages)
March 31,
2025
March 31,
2025
(adjusted)
March 31,
2024
March 31,
2024
(adjusted)
Net income as stated
39,399
39,399
58,944
58,944
Amortization of acquired intangible assets
3,275
3,275
3,275
3,275
Income tax impact of the above item
(868)
(868)
(868)
(868)
Net income before amortization of acquired intangible assets, net of income tax
41,806
41,806
61,351
61,351
Impact of adjusting items1
Other operating expenses
Integration costs
–
92
–
182
Advisory Costs
–
–
–
2,543
Other loss
–
–
–
4,398
Finance costs
Fair value change on prepayment options related to Notes Payable
–
24,714
–
(1,198)
Total pre-tax impact of adjusting items
–
24,806
–
5,925
Income tax impact of above adjusting items
(6,573)
–
(988)
After-tax impact of adjusting items
–
18,233
–
4,937
Adjusted net income
41,806
60,039
61,351
66,288
Multiplied by number of periods in a year
X 4
X 4
X 4
X 4
Average shareholders’ equity
1,176,739
1,176,739
1,078,662
1,078,662
Average goodwill
(180,923)
(180,923)
(180,923)
(180,923)
Average acquired intangible assets2
(81,329)
(81,329)
(94,429)
(94,429)
Average related deferred tax liabilities
21,552
21,552
25,024
25,024
Divided by average tangible common equity
936,039
936,039
828,334
828,334
Return on tangible common equity
17.9 %
25.7 %
29.6 %
32.0 %
1
For explanation of adjusting items, refer to the corresponding “Adjusted Net Income and Adjusted Diluted Earnings Per Share” section.
2
Excludes intangible assets relating to software.
easyhome Financial Revenue
easyhome financial revenue is a non-IFRS measure. It’s calculated as total company revenue less easyfinancial revenue and leasing revenue. The Company believes that easyhome financial revenue is an important measure of the performance of the easyhome segment. Items used to calculate easyhome financial revenue for the three-month periods ended March 31, 2025 and 2024 include those indicated in the chart below:
($in 000’s)
Three Months Ended
March 31,
2025
March 31,
2024
Total company revenue
391,861
357,114
Less: easyfinancial revenue
(354,819)
(318,056)
Less: leasing revenue
(23,515)
(26,249)
easyhome financial revenue
13,527
12,809
Total Yield on Consumer Loans as a Percentage of Average Gross Consumer Loans Receivable
Total yield on consumer loans as a percentage of average gross consumer loans receivable is a non-IFRS ratio. See description in section “Portfolio Analysis” on page 13 of the Company’s MD&A for the three-month period ended March 31, 2025. Items used to calculate total yield on consumer loans as a percentage of average gross consumer loans receivable for the three-month periods ended March 31, 2025 and 2024 include those indicated in the chart below:
Three Months Ended
($ in 000’s except percentages)
March 31,
2025
March 31,
2024
Total Company revenue
391,861
357,114
Less: Leasing revenue
(23,515)
(26,249)
Financial revenue
368,346
330,865
Multiplied by number of periods in a year
X 4
X 4
Divided by average gross consumer loans receivable
4,709,745
3,778,309
Total yield on consumer loans as a percentage of average gross consumer loans receivable (annualized)
31.3 %
35.0 %
Net Principal Written and Percentage Net Principal Written to New Customers
Net principal written (Net loan advances) is a non-IFRS measure. See description in section “Portfolio Analysis” on page 13 of the Company’s MD&A for the three-month period ended March 31, 2025. The percentage of net loan advances to new customers is a non-IFRS ratio. It is calculated as loan originations to new customers divided by the net principal written. The Company uses percentage of net loan advances to new customers, among other measures, to assess the operating performance of its lending business. Items used to calculate the percentage of net loan advances to new customers for the three-month periods ended March 31, 2025 and 2024 include those indicated in the chart below:
Three Months Ended
($ in 000’s)
March 31,
2025
March 31,
2024
Gross loan originations
676,769
686,433
Loan originations to new customers
431,949
355,881
Loan originations to existing customers
244,821
330,552
Less: Proceeds applied to repay existing loans
(85,711)
(171,082)
Net advance to existing customers
159,110
159,470
Net principal written
591,059
515,351
Percentage net advances to new customers
73.1 %
69.1 %
Debt to Adjusted Tangible Equity
Debt to adjusted tangible equity is a capital management measure. Refer to “Financial Condition” section on page 32 of the Company’s MD&A for the three-month period ended March 31, 2025.
Average Loan Book Per Branch
Average loan book per branch is a supplementary financial measure. It is calculated as gross consumer loans receivable held by easyfinancial branch locations divided by the number of total easyfinancial branch locations.
Weighted Average Interest Rate
Weighted average interest rate is a supplementary financial measure. It is calculated as the sum of individual loan balance multiplied by interest rate divided by gross consumer loans receivable.
SOURCE goeasy Ltd

You may like
Technology
Global Security & Technology Summit Unveils Month-Long Program of Activities Ahead of December Event
Published
6 hours agoon
October 24, 2026By
RIYADH, Saudi Arabia, Oct. 24, 2026 /PRNewswire/ — The Organizing Committee of the Global Security & Technology Summit (GSTS) held an introductory session today at the Ministry of Interior’s headquarters in Riyadh, bringing together representatives from the government, private, and nonprofit sectors to introduce the program of activities leading up to the summit. The upcoming summit will be held in Riyadh under the patronage of HRH Prince Mohammed bin Salman bin Abdulaziz Al Saud, Crown Prince and Prime Minister, under the supervision of HRH Prince Abdulaziz bin Saud bin Naif bin Abdulaziz Al Saud, Minister of Interior, and organized by the Ministry of Interior in cooperation with Tuwaiq Academy.
During the session, the Organizing Committee presented the comprehensive GSTS program, comprising three key components: GSTS Month, running from November 1 to 30, 2026; the Global Security & Innovation Fair (SAIF), taking place from November 24 to 26, 2026; and the main Summit, scheduled for December 18 to 20, 2026, in Riyadh. Together, these events form an integrated program designed to advance security and technology innovation, strengthen national capabilities, and foster international cooperation.
GSTS Month will feature working groups, boot camps, training programs, knowledge-sharing sessions, and technical workshops across Saudi Arabia’s 13 administrative regions, delivered both in person and remotely in collaboration with specialized entities. The month-long program aims to develop national capabilities, identify emerging talent, enrich knowledge-sharing opportunities, and equip professionals with the knowledge and skills needed to develop innovative solutions to future security and technology challenges.
The main Summit will bring together global leaders, decision-makers, experts, and innovators to explore the future of security and technology, promote the integration of advanced technologies within the security sector, strengthen national capabilities, support innovation, and foster international cooperation, further positioning the Kingdom as a global hub for security and technology.
Showcasing the latest technological breakthroughs and security solutions, the summit will bring together government entities, private sector organizations, academic institutions, and research centers to facilitate knowledge exchange and collaboration across key fields, including cybersecurity, artificial intelligence (AI), the Internet of Things (IoT), smart security solutions, emerging technologies, and crisis management. The program will also feature main sessions, specialized discussions, and interactive exhibitions. Registration is available at gsts.sa.
Advisor to HRH the Minister of Interior and Chairman of the GSTS Organizing Committee, Ahmed Altowayan, stated that the summit builds on Saudi Arabia’s efforts to establish an advanced security and technology ecosystem focused on knowledge and innovation, keeping pace with rapid developments and future challenges.
Mr. Altowayan noted that the summit is a global platform for strengthening cooperation and exchanging expertise, anticipating future developments in security and technology, and developing strategic partnerships and innovative solutions that enhance the efficiency and readiness of security systems.
Vice Chairman of the GSTS Organizing Committee, Eng. Abdulaziz Alhammadi, said that the summit will offer a range of integrated programs and activities focused on enhancing national skills, encouraging innovation, and supporting international cooperation.
He added that GSTS Month will help build national capabilities, discover talent, and develop skills, with SAIF providing a platform for innovators and researchers from around the world to showcase leading technological solutions, while the main Summit will bring together leaders and experts to discuss the future of security and technology and explore new strategic partnership opportunities.
SAIF will take place at the Riyadh International Convention & Exhibition Center, bringing together innovators, researchers, technology talents, and industry experts from around the world to showcase promising innovations and projects across 14 fields of technology and innovation. The fair will provide opportunities to engage with project owners, including students, graduates, and entrepreneurs, and explore the different stages of innovation development through interactive zones, panel discussions on emerging security and innovation trends, and knowledge-sharing workshops led by specialists. Visitor registration is open to participants from within and outside the Kingdom through saifair.sa.
The introductory session also featured contributions from representatives of government, private, and nonprofit sector entities, alongside members of the media. Discussions focused on developing national capabilities in security and technology, strengthening students’ technical expertise, translating scientific research into practical solutions, and supporting Saudi companies in developing security and technology solutions and advancing digital transformation.
Organized by the Ministry of Interior in cooperation with Tuwaiq Academy, GSTS is produced by Tahaluf, with the Ministry of Education serving as Strategic Scientific Partner, Tahakom as Founding Partner, and Elm as Principal Partner.
Registration for participants from within and outside the Kingdom is available at gsts.sa.
Click here to view the media kit.
View original content to download multimedia:https://www.prnewswire.co.uk/news-releases/global-security–technology-summit-unveils-month-long-program-of-activities-ahead-of-december-event-302918695.html
Technology
Axon Announces Body 5: Next-Generation Camera Built for the AI Era
Published
11 hours agoon
October 24, 2026By
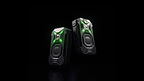
Axon Body 5 delivers 25x the AI processing power of earlier-generation cameras, with upgraded connectivity, audio and battery life to support real-time situational awareness in the field
SCOTTSDALE, Ariz., Oct. 24, 2026 /PRNewswire/ — Axon (Nasdaq: AXON), the global leader in public safety technology, today announced Axon Body 5, its newest body-worn camera designed to bring more powerful intelligence, connectivity and real-time support directly to officers in the field.
For years, Axon body cameras have helped agencies capture critical evidence and create greater transparency. Body 5 is built to help officers during the call, with information, assistance and backup on the spot.
“Officers shouldn’t have to choose between getting information and watching the scene. With Axon Body 5, they don’t,” said Rick Smith, Axon Founder and CEO. “They capture a license or document with the camera, keep their hands free and eyes up, and get information faster than writing it down and calling it in by radio. An officer fully engaged with the person in front of them, not down at a notepad, is a safer officer and a better-served community.”
Axon Body 5: Built for the AI Era
Built from the ground up for the AI era, Axon Body 5 delivers 25x the AI processing power than earlier generation Axon body cameras, alongside advancements in connectivity, audio, video and battery life. Together, these upgrades give the camera the physical power to run smarter AI features — both today and as new AI tools are developed in the future — while also making it more dependable for officers to use every day.
For the first time, Axon is also introducing two versions of its latest flagship camera: Axon Body 5 and Axon Body 5 Pro.
Both models feature several key advancements, including:
25x more processing power for AI: A powerful new computing architecture creates the capacity to support current and future AI features directly on the body camera.Enhanced video: Improved video captures clearer evidence across challenging environments, including better low-light performance.Improved connectivity: Seamless connectivity in urban and remote environments – and more precise location capability – helps officers, cameras and remote support teams stay connected when timely information matters most.Longer battery life: 20% more battery life than the previous generation helps keep the camera ready and connected throughout an officer’s shift.
The Axon Body 5 Pro will continue to gain new AI capabilities as they become available, growing along with the AI Era Plan. Additionally, new hardware features include:
A near-focus camera: An additional dedicated camera lens lets officers scan driver’s licenses to check status and search for wants or warrants in seconds, without returning to the patrol vehicle, with relevant information sent to Axon Fusus to support real-time operations.Front-facing speakers: Four additional speakers project even more powerful audio toward the person an officer is speaking with, helping real-time translations from Axon Assistant carry more clearly over heavy traffic or crowd noise. Additional memory: Extra space lets the camera run several AI tools at once, helping officers stay better informed and work faster.
Bringing More of Axon’s AI Era Into the Field
Axon Body 5 helps officers get more out of the Axon AI Era Plan by bringing smart tools right to the scene. Axon’s portfolio already supports public safety professionals across a growing range of tasks. For example, Draft One helps officers turn body-camera audio into high-quality report drafts and Axon Assistant provides voice-based information access and real-time translation.
Increasingly, Axon is also bringing AI into real-time operations.
Axon Guardian is a new category of AI features within the AI Era Plan that was specifically created to work with an officer’s field-based devices – starting with body cameras and in-car cameras – to improve safety. Guardian is designed to flag potential risks as situations unfold and create alerts when additional attention may be needed. Two of the first features include:
Escalation Detection: When an Axon Body 4 or Axon Body 5 camera is activated and recording, Guardian has the ability to detect potential conflicts in real time and create an alert in Axon Fusus. A human reviews the livestream and decides if additional support or action is needed.Approach Alert: When active on Axon Fleet 3, Guardian can detect if the door of a stopped vehicle opens and alert the officer through the in-car display and their body-worn camera.
Combined, Axon Body 5 and the expanding AI Era portfolio demonstrate the importance of AI as a critical resource to assist public safety professionals before, during and after an incident — reducing administrative burden, improving situational awareness and helping protect more lives.
Innovating Responsibly
Axon’s Responsible Innovation framework guides the development of all of its products. Designed with this in mind, Axon Body 5 and Guardian prioritize human oversight and maintain agency control over data. As a key part of the responsible innovation process, Axon’s independent Ethics and Equity Advisory Council was created to help responsibly develop and deploy new technologies with transparency, while aligning with community expectations.
General availability dates for Axon Body 5 and Axon Guardian will be announced soon. Product features and capabilities vary by configuration. For more information on Axon’s current products and services: Axon Product Catalog – Axon.com.
About Axon
Axon (Nasdaq: AXON) is the global leader in public safety technology supporting state, local, federal and international public safety agencies with technology designed to Protect Life. Complementing its mission, Axon’s growing Enterprise market focuses on protecting critical infrastructure and frontline workers across multiple industries including corporate security, hospitality, retail and healthcare. Founder-led since 1993, Axon builds products with transparency and responsibility. From TASER energy devices to today’s connected network of hardware – including cameras, drones, and robotics – cloud software, sensors, and AI-tools, the Axon ecosystem helps seamlessly protect people and places when it matters most. To ensure these technologies align with community expectations, Axon’s independent Ethics & Equity Advisory Council guides the ethical, inclusive, and accountable design of its products and services. Learn more about the EEAC and Axon’s Responsible Innovation framework at Axon Responsibility.
Non-Axon trademarks are the property of their respective owners. Axon, TASER and the Delta Logo are trademarks of Axon Enterprise, Inc., some of which are registered in the US and other countries. For more information, visit www.axon.com/legal. All rights reserved.
Please visit https://investor.axon.com and https://www.axon.com/newsroom for more information.
Media Contact:
Kate MacKinnon
Vice President, Communications
press@axon.com
View original content to download multimedia:https://www.prnewswire.com/news-releases/axon-announces-body-5-next-generation-camera-built-for-the-ai-era-302918553.html
SOURCE Axon
Technology
In HelloNation, Custom Fabrication Expert Mark Coyle Explains a Common Mistake in Custom Aluminum Design
Published
12 hours agoon
October 24, 2026By
The article explains why smart geometry, not thicker walls, creates stronger, more efficient aluminum components.
ROCHESTER, N.Y., Oct. 24, 2026 /PRNewswire/ — What early design choice causes many custom aluminum projects to become heavier, costlier, or harder to manufacture? That question is addressed in a HelloNation article featuring insights from Custom Fabrication Expert Mark Coyle of American Custom Metals, Inc. in Rochester, New York, that outlines how misunderstanding aluminum behavior leads designers to rely on thick walls instead of stronger geometry.
The article begins by explaining that many people assume thicker walls automatically make aluminum parts stronger. It notes that aluminum does not respond to wall thickness the way steel does. Instead, its performance is shaped by how the metal flows through the extrusion die. The article states that custom aluminum design is more effective when profiles use ribs, chambers, and flanges to create stiffness without adding unnecessary weight. This guidance helps readers understand why adding material often increases cost without improving strength.
The article also highlights that thicker walls change how aluminum moves during extrusion. When heavy areas fill more slowly, the metal cools unevenly and can develop stress that only appears later. The HelloNation piece explains that well-balanced geometry keeps extrusion smooth and predictable. This consistency makes it easier to maintain dimensional accuracy across long production runs. By focusing on geometry, custom aluminum design avoids the problems that come with slow extrusion speeds and uneven cooling.
Another insight in the article centers on how ribs and internal supports influence stability. It describes how a thin wall supported by a properly placed rib often performs better than a thick wall with no reinforcement. This happens because the rib helps distribute load, improve stiffness, and guide the aluminum as it cools. The article explains that this structural approach makes custom aluminum design more efficient and gives designers more control over how the final part behaves under pressure.
The article also shows why early collaboration between designer and fabricator prevents costly changes. It states that a fabricator familiar with extrusion can catch potential issues before a die is built. Small adjustments to corners or transitions can remove weak points or improve metal flow. The article notes that this teamwork keeps the design aligned with real-world production. By working together early, both sides reduce the risk of redesigning the die after the first test run.
Machining is another area where the article explains how wall thickness affects performance. Features such as deep pockets or sharp internal angles may require slow feed rates or special tooling. When walls are thicker than needed, those areas can become difficult to machine cleanly. The article states that thoughtful custom aluminum design makes machining more predictable. Small changes, such as adding radiused edges or sizing features to match standard tools, help shorten cycle times and prevent tool wear.
Thermal behavior receives detailed attention as well. The article explains that aluminum retains heat differently depending on the mass of each section. Thicker walls hold heat longer, which increases the chance of distortion during extrusion, machining, or finishing. When a design uses geometry to create strength, the material cools more evenly. This reduces warping and helps long profiles stay aligned. The article notes that stable cooling is important for components that require a precise fit and consistent shape throughout an entire production run.
Cost is also a key topic in the article. It states that heavier profiles increase material use, extrusion time, and tooling needs. A custom aluminum design that relies on geometry instead of mass lowers material consumption and keeps the fabrication process efficient. The article explains that lighter parts are easier to handle, ship, and assemble. This saves money across multiple stages of production and supports long-term manufacturing efficiency.
The article also notes that smart custom aluminum design creates profiles that behave predictably during extrusion and machining. Smooth transitions, balanced wall dimensions, and structural features help reduce the chance of distortion or dimensional drift. These elements also lower scrap rates and support reliable performance. By using geometry instead of excess material, designers build parts that maintain strength without compromising manufacturability.
As the article concludes, it emphasizes that avoiding thick walls is one of the best ways to improve performance and lower cost. It states that the most dependable custom aluminum components come from designs that use structural features to strengthen the profile. When designers understand how aluminum behaves at each stage of extrusion and machining, they create parts that are strong, efficient, and consistent from batch to batch. This approach turns custom aluminum design into a predictable process rather than a series of uncertain adjustments.
A Common Mistake in Custom Aluminum Design features insights from Mark Coyle, Custom Fabrication Expert of Rochester, NY, in HelloNation.
About HelloNation
HelloNation is America’s Good News Network, a premier media platform built on the idea that good news travels faster when real people tell real stories. Through its community-focused publications and innovative “edvertising” approach, HelloNation delivers content that informs, inspires, and spotlights the leaders making a meaningful impact in their communities.
View original content to download multimedia:https://www.prnewswire.com/news-releases/in-hellonation-custom-fabrication-expert-mark-coyle-explains-a-common-mistake-in-custom-aluminum-design-302918282.html
SOURCE HelloNation


Global Security & Technology Summit Unveils Month-Long Program of Activities Ahead of December Event

Axon Announces Body 5: Next-Generation Camera Built for the AI Era

In HelloNation, Custom Fabrication Expert Mark Coyle Explains a Common Mistake in Custom Aluminum Design

Send Rakhi to UK swiftly with UK Gifts Portal

Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

Nullmax and Renesas Forge Strategic Partnership to Deliver Competitive ADAS Solutions for the Global Market

Why You Should Build on #NEAR – Co-founder Illia Polosukhin at CV Labs
Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

NEAR End of Year Town Hall 2021: The Open Web World, MetaBUILD 2 Hackathon and 2021 recap
Trending
-
 Technology4 days ago
NC AI Officially Releases VARCO Sound, the Generative AI Sound Production Service
-
 Technology4 days ago
Sophont Launches Holon-S1 to Reveal Tumor Biology from Routine Pathology Slides
-
 Technology5 days ago
Trinity Acquires Verix, Adding AI-Powered Next-Best-Action and Omnichannel Orchestration to the TrinityEDGE Platform
-
 Coin Market4 days ago
Stablecoin transfers quadruple to $891B as US banks expand adoption: Report
-
 Technology4 days ago
Workato Launches Self-Serve Platform in Singapore, Opening Enterprise AI to a Broader Community of Builders
-
 Technology2 days ago
Miami Startup BOB Raises $5.5M To Build An AI-Powered Banking Platform
-
 Technology5 days ago
Findem Takes on Candidate Fraud With Authenticity Suite Pro
-
 Technology4 days ago
Fulcra Launches Agent Skill to Build Apps People and Agents Can Use Together