
Technology
Manufacturing PMI® at 52.7%; April 2026 ISM® Manufacturing PMI® Report

Published
6 months agoon
By
New Orders Growing; Production Growing; Employment Contracting; Supplier Deliveries Slowing; Raw Materials Inventories Contracting; Customers’ Inventories Too Low; Prices Increasing; Imports Growing; Exports Contracting
TEMPE, Ariz., May 1, 2026 /PRNewswire/ — Economic activity in the manufacturing sector expanded in April for the fourth consecutive month, say the nation’s supply executives in the latest ISM® Manufacturing PMI® Report.
The report was issued today by Susan Spence, MBA, Chair of the Institute for Supply Management® (ISM®) Manufacturing Business Survey Committee.
“The Manufacturing PMI® registered 52.7 percent in April, the same reading as March. The overall economy continued in expansion for the 18th month in a row. (A Manufacturing PMI® above 47.5 percent, over a period of time, generally indicates an expansion of the overall economy.) The New Orders Index expanded for the fourth straight month after four straight readings in contraction, registering 54.1 percent, up 0.6 percentage point compared to March’s figure of 53.5 percent. The April reading of the Production Index (53.4 percent) is 1.7 percentage points lower than March’s reading of 55.1 percent. The Prices Index remained in expansion (or ‘increasing’ territory), registering 84.6 percent, a 6.3-percentage point jump from March’s reading of 78.3 percent. In the last three months, the Prices Index has increased 25.6 percentage points to reach its highest level since April 2022 (84.6 percent). The Backlog of Orders Index registered 51.4 percent, down 3 percentage points compared to the 54.4 percent recorded in March. The Employment Index registered 46.4 percent, down 2.3 percentage points from March’s figure of 48.7 percent,” says Spence.
“The Supplier Deliveries Index indicated slowing performance for the fifth month in a row after one month in ‘faster’ territory. The reading of 60.6 percent is up 1.7 percentage points from the 58.9 percent recorded in March; the index has risen in each of the last five months, meaning delivery times are increasingly slowing. (Supplier Deliveries is the only ISM® PMI® Reports index that is inversed; a reading of above 50 percent indicates slower deliveries, which is typical as the economy improves and customer demand increases.)
“The Inventories Index registered 49 percent, up 1.9 percentage points compared to March’s reading of 47.1 percent. The Customers’ Inventories Index reading of 39.1 percent is a 1-percentage point decrease compared to March.
“The New Export Orders Index reading of 47.9 percent is 2 percentage points lower than the reading of 49.9 percent registered in March, making it the second month in a row in contraction territory. The Imports Index registered 50.3 percent, 2.3 percentage points lower than March’s reading of 52.6 percent.”
Spence continues, “In April, U.S. manufacturing activity remained in expansion territory, growing at the same pace as the month before. Of the five subindexes that make up the PMI®, the New Orders and Supplier Deliveries indexes indicated faster growth compared to the previous month, the Production Index grew at a slower rate, and the Employment and Inventories indexes remained in contraction.
“In this second month of the Iran War (at the time of data collection), 31 percent of the comments were positive and 69 percent negative, with a positive to negative sentiment ratio of 1 to 2.2. Among comments, the war was mentioned in 47 percent and tariffs in 18 percent. As was the case last month, some panelists referenced both topics within a single comment or in mixed sentiment.
“Two of four demand indicators (the New Orders and Backlog of Orders indexes) remain in expansion, although the Backlog of Orders Index dropped 3 percentage points compared to March. The New Export Orders Index remained in contraction with a 2-percentage point decrease, and the Customers’ Inventories Index remains in ‘too low’ territory, contracting at a slightly faster rate. A ‘too low’ status for the Customers’ Inventories Index is usually considered positive for future production.
“Regarding output, the Production Index is in expansion for the sixth month in a row (although it lost ground compared to March), and the Employment Index decreased by 2.3 percentage points and remains in contraction. Among panelists, 60 percent indicated that managing head counts remains the norm at their companies as opposed to hiring, and of those managing head counts, 34 percent are using layoffs and 43 percent using attrition or not backfilling positions.
“Finally, inputs (defined as supplier deliveries, inventories, prices, and imports) had another month of mixed results. The Supplier Deliveries Index indicated increasingly slowing deliveries, the Inventories Index contracted at a slower rate, and the Prices Index vaulted again — up another 6.3 percentage points to 84.6 percent, from 78.3 percent in March, and the highest reading from April 2022, when it was also at 84.6 percent. The Imports Index lost 2.3 percentage points for a reading of 50.3 percent, compared to 52.6 percent in March.
“Looking at the manufacturing economy, 19 percent of the sector’s gross domestic product (GDP) contracted in April, compared to 16 percent in March, and the percentage of manufacturing GDP in strong contraction (defined as a composite PMI® of 45 percent or lower) decreased to 2 percent, compared to 4 percent in March. The share of sector GDP with a PMI® at or below 45 percent is a good metric to gauge overall manufacturing weakness. Of the six largest manufacturing industries, four (Transportation Equipment; Machinery; Computer & Electronic Products; and Chemical Products) expanded in April,” says Spence.
The 13 manufacturing industries reporting growth in April — listed in order — are: Textile Mills; Nonmetallic Mineral Products; Primary Metals; Plastics & Rubber Products; Miscellaneous Manufacturing; Transportation Equipment; Machinery; Electrical Equipment, Appliances & Components; Paper Products; Fabricated Metal Products; Computer & Electronic Products; Chemical Products; and Furniture & Related Products. The three industries reporting contraction in April are: Wood Products; Petroleum & Coal Products; and Food, Beverage & Tobacco Products.
WHAT RESPONDENTS ARE SAYING
“Demand for manufactured goods is trending higher versus last year; however, geopolitical uncertainty and rising oil and diesel prices continue to weigh on demand. Many customers are exercising caution and remain in a wait-and-watch mode.” [Transportation Equipment]”Continued tariffs on products utilized in our product lines are being monitored by the business, with the business working to mitigate or limit tariff risk. Geopolitical risk, especially in the Middle East, as it pertains to commodity and energy markets remains a concern and is being monitored by the business. Supply chain risk concerns pertaining to increased cost and transit time for rerouted shipments due to conflict in the Red Sea, Strait of Hormuz and Suez Canal. These conditions are being monitored by the business and rerouting measures have been implemented where possible.” [Transportation Equipment]”Continuing fluctuation in U.S. tariffs as well as market constraints for certain materials are affecting our current business. U.S. support of AI-related industry is also in flux which is causing some customer and investment hesitancy.” [Computer & Electronic Products]”All products tied to crude, polyethylene resin or energy (liquified natural gas) have seen multiple increase spikes tied to the Iran crisis and market supply inflation.” [Chemical Products]”Revenues are very strong. However, price increases are similar to a few years ago with the supply chain crisis. All imports from China are up 15 percent to 25 percent, which is impossible for us to absorb or to fully pass along. Our suppliers in China are telling us that oil is at an all-time high, which is putting huge challenges on their cost structures.” [Chemical Products]”General uncertainty over the total impact of the U.S.-Iran war. Have not yet started to see the full impact of fuel increases but are aware they are coming.” [Machinery]”Business levels have been decent this year, in line with the same period last year and improved from the second half of 2025. However, higher cost pressures are impacting margins.” [Fabricated Metal Products]”Commodity markets remain mixed, with pockets of easing offset by ongoing volatility. Dairy and some soft commodities have cooled, while oils and grain-related inputs remain elevated given biofuel demand and feed costs. Pricing is still sensitive to policy changes, weather and global trade dynamics.” [Food, Beverage & Tobacco Products]”Our business remains strong and stable, but there are a lot of concerns in the geopolitical arena. If the Iran conflict persists, the impact on market pricing and supply continuity could be extreme. Electronics component market remains very volatile (pricing and continuity) based on AI.” [Miscellaneous Manufacturing]
April 2026
Index
Series
Index
Apr
Series
Index
Mar
Percentage
Point
Change
Direction
Rate of
Change
Trend*
(Months)
Manufacturing
PMI®
52.7
52.7
0.0
Growing
Same
4
New Orders
54.1
53.5
+0.6
Growing
Faster
4
Production
53.4
55.1
-1.7
Growing
Slower
6
Employment
46.4
48.7
-2.3
Contracting
Faster
31
Supplier
Deliveries
60.6
58.9
+1.7
Slowing
Faster
5
Inventories
49.0
47.1
+1.9
Contracting
Slower
12
Customers’
Inventories
39.1
40.1
-1.0
Too Low
Faster
19
Prices
84.6
78.3
+6.3
Increasing
Faster
19
Backlog of
Orders
51.4
54.4
-3.0
Growing
Slower
4
New Export
Orders
47.9
49.9
-2.0
Contracting
Faster
2
Imports
50.3
52.6
-2.3
Growing
Slower
3
OVERALL ECONOMY
Growing
Same
18
Manufacturing Sector
Growing
Same
4
ISM® Manufacturing PMI® Report data is seasonally adjusted for the New Orders, Production, Employment and Inventories indexes.
*Number of months moving in current direction.
COMMODITIES REPORTED UP/DOWN IN PRICE AND IN SHORT SUPPLY
Commodities Up in Price
Acrylic Products; Adhesives; Aluminum (29); Aluminum Products; Caustic Soda; Chemical Products (2); Cooking Fats and Oils (2); Copper (10); Copper Based Products (5); Corn (2); Corrugated Products; Diesel Fuel (2); Electronic Components (4); Freight (2); Fuel (2); High Density Polyethylene (HDPE); Logistics Services; Memory Components (2); Metal Products; Methanol (2); Nickel Products; Nylon; Oil; Oil Based Products; Packaging; Paint; Paper Products; Petroleum Based Products; Plastic Based Products; Plastics (2); Polyester; Polyethylene Resins; Polyethylene Terephthalate; Polyvinyl Chloride; Resins (3); Solvents; Soybean Products (2); Steel (6); Steel — Carbon; Steel — Hot Rolled (4); Steel — Stainless (3); Steel Products (5); Sulfur Products; Transportation Costs; Tungsten Products (3); and Wire and Cable.
Commodities Down in Price
Natural Gas.
Commodities in Short Supply
Aluminum; Bearing Components (2); Electrical Components (10); Electronic Components (14); Memory (4); Propylene Glycol; and Semiconductors (2).
Note: The number of consecutive months the commodity is listed is indicated after each item.
APRIL 2026 MANUFACTURING INDEX SUMMARIES
Manufacturing PMI®
The U.S. manufacturing sector expanded in April for the fourth straight month following a 10-month period of contraction, registering 52.7 percent, the same reading as March. Of the five subindexes that directly factor into the Manufacturing PMI®, three (New Orders, Production and Supplier Deliveries) were in expansion territory, the same as in March. The Employment and Inventories indexes stayed in contraction, with Employment in decline compared to March. Of the six largest manufacturing industries, four (Transportation Equipment; Machinery; Computer & Electronic Products; and Chemical Products) expanded in April. A reading above 50 percent indicates that the manufacturing sector is generally expanding; below 50 percent indicates that it is generally contracting.
A Manufacturing PMI® above 47.5 percent, over a period of time, generally indicates an expansion of the overall economy. Therefore, the April Manufacturing PMI® indicates the overall economy grew for the 18th straight month. “The past relationship between the Manufacturing PMI® and the overall economy indicates that the April reading (52.7 percent) corresponds to a 1.8-percent increase in real gross domestic product (GDP) on an annualized basis,” says Spence.
THE LAST 12 MONTHS
Month
Manufacturing
PMI®
Month
Manufacturing
PMI®
Apr 2026
52.7
Oct 2025
48.8
Mar 2026
52.7
Sep 2025
48.9
Feb 2026
52.4
Aug 2025
48.9
Jan 2026
52.6
Jul 2025
48.4
Dec 2025
47.9
Jun 2025
49.0
Nov 2025
48.0
May 2025
48.6
Average for 12 months – 49.9
High – 52.7
Low – 47.9
New Orders
ISM®’s New Orders Index expanded in April with a reading of 54.1 percent, an increase of 0.6 percentage point compared to March’s reading of 53.5 percent. “Of the six largest manufacturing industries, four (Transportation Equipment; Computer & Electronic Products; Machinery; and Chemical Products) reported increased new orders. Demand sentiment was positive, with a 1.6-to-1.0 ratio of positive to negative comments in April. A number of the positive comments noted, however, that customers were ordering to get ahead of price increases,” says Spence. A New Orders Index above 51.9 percent, over time, is generally consistent with an increase in the Census Bureau’s series on manufacturing orders (in constant 2000 dollars).
The 12 manufacturing industries that reported growth in new orders in April, in order, are: Apparel, Leather & Allied Products; Nonmetallic Mineral Products; Textile Mills; Plastics & Rubber Products; Transportation Equipment; Miscellaneous Manufacturing; Computer & Electronic Products; Primary Metals; Machinery; Electrical Equipment, Appliances & Components; Fabricated Metal Products; and Chemical Products. The three industries reporting a decline in new orders in April are: Printing & Related Support Activities; Wood Products; and Food, Beverage & Tobacco Products.
New Orders
%Higher
%Same
%Lower
Net
Index
Apr 2026
31.6
53.2
15.2
+16.4
54.1
Mar 2026
29.1
56.3
14.6
+14.5
53.5
Feb 2026
30.3
56.9
12.8
+17.5
55.8
Jan 2026
31.4
51.0
17.6
+13.8
57.1
Production
The Production Index expanded in April for the sixth month in a row, registering 53.4 percent, a 1.7-percentage point decrease compared to March’s reading of 55.1 percent. “Of the six largest manufacturing industries, four (Transportation Equipment; Machinery; Computer & Electronic Products; and Chemical Products) reported increased production. For a second month in a row, panelists had a 2-to-1 ratio of positive to negative comments regarding output,” says Spence. An index above 52 percent, over time, is generally consistent with an increase in the Federal Reserve Board’s Industrial Production figures.
The 11 industries reporting growth in production during the month of April — listed in order — are: Nonmetallic Mineral Products; Textile Mills; Plastics & Rubber Products; Transportation Equipment; Electrical Equipment, Appliances & Components; Primary Metals; Machinery; Miscellaneous Manufacturing; Computer & Electronic Products; Chemical Products; and Fabricated Metal Products. The two industries reporting a decrease in production in April are: Wood Products; and Food, Beverage & Tobacco Products.
Production
%Higher
%Same
%Lower
Net
Index
Apr 2026
28.3
58.7
13.0
+15.3
53.4
Mar 2026
24.5
62.8
12.7
+11.8
55.1
Feb 2026
25.2
58.8
16.0
+9.2
53.5
Jan 2026
25.7
58.8
15.5
+10.2
55.9
Employment
ISM®’s Employment Index registered 46.4 percent in April, 2.3 percentage points lower than March’s reading of 48.7 percent. “The index posted its 31st consecutive month of contraction after expanding in September 2023. Since January 2023, the Employment Index has contracted in 39 of 40 months. Of the six big manufacturing industries, three (Transportation Equipment; Computer & Electronic Products; and Machinery) reported higher levels of employment in April. For every comment on hiring, there was 1.7 on reducing head counts,” says Spence. An Employment Index above 50.3 percent, over time, is generally consistent with an increase in the Bureau of Labor Statistics (BLS) data on manufacturing employment.
Of the 18 manufacturing industries, five reported employment growth in April: Printing & Related Support Activities; Transportation Equipment; Miscellaneous Manufacturing; Computer & Electronic Products; and Machinery. The eight industries reporting a decrease in employment in April, in the following order, are: Apparel, Leather & Allied Products; Textile Mills; Wood Products; Petroleum & Coal Products; Food, Beverage & Tobacco Products; Electrical Equipment, Appliances & Components; Plastics & Rubber Products; and Chemical Products.
Employment
%Higher
%Same
%Lower
Net
Index
Apr 2026
17.5
62.3
20.2
-2.7
46.4
Mar 2026
14.2
70.8
15.0
-0.8
48.7
Feb 2026
18.8
60.8
20.4
-1.6
48.8
Jan 2026
13.7
68.0
18.3
-4.6
48.1
Supplier Deliveries†
Delivery performance of suppliers to manufacturing organizations was slower in April for the fifth consecutive month after one month of faster deliveries. “The Supplier Deliveries Index registered 60.6 percent, a 1.7-percentage point increase compared to the reading of 58.9 percent reported in March. Of the six big industries, five (Food, Beverage & Tobacco Products; Machinery; Chemical Products; Computer & Electronic Products; and Transportation Equipment) reported slower supplier deliveries” says Spence. A reading below 50 percent indicates faster deliveries, while a reading above 50 percent indicates slower deliveries.
The 14 manufacturing industries reporting slower supplier deliveries in April, in order, are: Textile Mills; Paper Products; Plastics & Rubber Products; Primary Metals; Fabricated Metal Products; Food, Beverage & Tobacco Products; Nonmetallic Mineral Products; Machinery; Electrical Equipment, Appliances & Components; Chemical Products; Furniture & Related Products; Miscellaneous Manufacturing; Computer & Electronic Products; and Transportation Equipment. No industry reported faster deliveries in April.
Supplier
Deliveries
%Slower
%Same
%Faster
Net
Index
Apr 2026
22.6
75.9
1.5
+21.1
60.6
Mar 2026
19.5
78.8
1.7
+17.8
58.9
Feb 2026
14.0
82.2
3.8
+10.2
55.1
Jan 2026
12.7
83.3
4.0
+8.7
54.4
Inventories
The Inventories Index registered 49 percent in April, up 1.9 percentage points compared to the reading of 47.1 percent in March. “Only one (Chemical Products) of the six big industries expanded inventories in April,” says Spence. An Inventories Index greater than 44.5 percent, over time, is generally consistent with expansion in the Bureau of Economic Analysis (BEA) figures on overall manufacturing inventories (in chained 2000 dollars).
Of 18 manufacturing industries, the five reporting higher inventories in April are: Textile Mills; Primary Metals; Miscellaneous Manufacturing; Electrical Equipment, Appliances & Components; and Chemical Products. The eight industries reporting lower inventories in April — listed in order — are: Wood Products; Nonmetallic Mineral Products; Computer & Electronic Products; Plastics & Rubber Products; Fabricated Metal Products; Food, Beverage & Tobacco Products; Transportation Equipment; and Machinery.
Inventories
%Higher
%Same
%Lower
Net
Index
Apr 2026
14.5
68.3
17.2
-2.7
49.0
Mar 2026
16.7
64.3
19.0
-2.3
47.1
Feb 2026
14.2
71.8
14.0
+0.2
48.8
Jan 2026
14.0
66.4
19.6
-5.6
47.6
Customers’ Inventories†
ISM®’s Customers’ Inventories Index remained in “too low” territory in April with reading of 39.1 percent, a decrease of 1 percentage point compared to the 40.1 percent reported in March. In the last four months, this index has averaged 39.2 percent, its lowest levels since it averaged 33.1 percent over a 25-month period ending in August 2022. (For more information about the Customers’ Inventories Index, see the “Data and Method of Presentation” section below.)
The only industry to report that customers’ inventories were too high in April was Miscellaneous Manufacturing. The 11 industries reporting customers’ inventories as too low in April, in order, are: Nonmetallic Mineral Products; Primary Metals; Electrical Equipment, Appliances & Components; Transportation Equipment; Plastics & Rubber Products; Computer & Electronic Products; Furniture & Related Products; Food, Beverage & Tobacco Products; Machinery; Chemical Products; and Fabricated Metal Products. Six industries reported no change in customers’ inventories in April compared to March.
Customers’
Inventories
%
Reporting
%Too High
%About Right
%Too Low
Net
Index
Apr 2026
73
7.6
62.9
29.5
-21.9
39.1
Mar 2026
74
6.9
66.3
26.8
-19.9
40.1
Feb 2026
76
5.7
66.1
28.2
-22.5
38.8
Jan 2026
69
5.5
66.3
28.2
-22.7
38.7
Prices†
The ISM® Prices Index registered 84.6 percent in April, an increase of 6.3 percentage points over its March reading of 78.3 percent, indicating raw materials prices increased for the 19th straight month. The Prices Index has risen 25.6 percentage points in the last three months to hit its highest reading since April 2022 (84.6 percent). All the six largest manufacturing industries — Chemical Products; Petroleum & Coal Products; Machinery; Food, Beverage & Tobacco Products; Computer & Electronic Products; and Transportation Equipment, in that order — reported price increases in April. “As was the case in March, the Prices Index reading continues to be driven by (1) increases in steel and aluminum prices that impact the entire value chain, (2) tariffs applied to many imported goods and now (3) increases in petroleum-based products as a result of the Middle East conflict. Higher prices were reported by 70.3 percent of respondents in April, up 10.9 percentage points from March’s 59.4 percent,” says Spence. A Prices Index above 52.8 percent, over time, is generally consistent with an increase in the Bureau of Labor Statistics (BLS) Producer Price Index for Intermediate Materials.
In April, the 17 industries that reported paying increased prices for raw materials, in order, are: Nonmetallic Mineral Products; Paper Products; Plastics & Rubber Products; Textile Mills; Wood Products; Primary Metals; Furniture & Related Products; Chemical Products; Fabricated Metal Products; Electrical Equipment, Appliances & Components; Petroleum & Coal Products; Miscellaneous Manufacturing; Machinery; Food, Beverage & Tobacco Products; Computer & Electronic Products; Transportation Equipment; and Apparel, Leather & Allied Products. No industries reported paying decreased prices for raw materials in April.
Prices
%Higher
%Same
%Lower
Net
Index
Apr 2026
70.3
28.5
1.2
+69.1
84.6
Mar 2026
59.4
37.8
2.8
+56.6
78.3
Feb 2026
45.4
50.2
4.4
+41.0
70.5
Jan 2026
29.0
59.9
11.1
+17.9
59.0
Backlog of Orders†
ISM®’s Backlog of Orders Index registered 51.4 percent in April, a decrease of 3 percentage points compared to the March reading of 54.4 percent. Of the six largest manufacturing industries, two (Computer & Electronic Products; and Chemical Products) reported expansion in order backlogs in April.
The eight industries reporting higher backlogs in April — listed in order — are: Textile Mills; Fabricated Metal Products; Nonmetallic Mineral Products; Miscellaneous Manufacturing; Paper Products; Primary Metals; Computer & Electronic Products; and Chemical Products. The five industries reporting lower backlogs in April are: Petroleum & Coal Products; Machinery; Plastics & Rubber Products; Transportation Equipment; and Wood Products.
Backlog of
Orders
% Reporting
%Higher
%Same
%Lower
Net
Index
Apr 2026
90
22.1
58.6
19.3
+2.8
51.4
Mar 2026
90
24.6
59.6
15.8
+8.8
54.4
Feb 2026
90
26.8
59.5
13.7
+13.1
56.6
Jan 2026
90
22.2
58.8
19.0
+3.2
51.6
New Export Orders†
ISM®’s New Export Orders Index registered 47.9 percent, down 2 percentage points from March’s reading of 49.9 percent. “Trade and war frictions continue to be a major concern. For every positive comment on exports, there was 1.6 negative comments,” says Spence.
Of the 18 manufacturing industries, the three that reported growth in new export orders in April are: Miscellaneous Manufacturing; Primary Metals; and Computer & Electronic Products. The 10 industries that reported a decrease in new export orders in April — in the following order — are: Wood Products; Petroleum & Coal Products; Paper Products; Furniture & Related Products; Apparel, Leather & Allied Products; Food, Beverage & Tobacco Products; Plastics & Rubber Products; Electrical Equipment, Appliances & Components; Machinery; and Chemical Products.
New Export
Orders
%
Reporting
%Higher
%Same
%Lower
Net
Index
Apr 2026
75
10.4
75.0
14.6
-4.2
47.9
Mar 2026
74
12.1
75.5
12.4
-0.3
49.9
Feb 2026
74
9.2
82.2
8.6
+0.6
50.3
Jan 2026
73
11.5
77.3
11.2
+0.3
50.2
Imports†
ISM®’s Imports Index decreased in April to 50.3 percent, a 2.3-percentage point drop compared to March’s reading of 52.6 percent.
The eight industries reporting higher imports in April — in the following order — are: Apparel, Leather & Allied Products; Textile Mills; Transportation Equipment; Food, Beverage & Tobacco Products; Electrical Equipment, Appliances & Components; Computer & Electronic Products; Miscellaneous Manufacturing; and Machinery. The four industries that reported lower volumes in April are: Paper Products; Wood Products; Furniture & Related Products; and Chemical Products. Six industries reported no change in imports in April compared to March.
Imports
%
Reporting
%Higher
%Same
%Lower
Net
Index
Apr 2026
85
10.6
79.3
10.1
+0.5
50.3
Mar 2026
87
15.1
75.0
9.9
+5.2
52.6
Feb 2026
87
15.8
78.1
6.1
+9.7
54.9
Jan 2026
85
11.3
77.4
11.3
0.0
50.0
†The Supplier Deliveries, Customers’ Inventories, Prices, Backlog of Orders, New Export Orders, and Imports indexes do not meet the accepted criteria for seasonal adjustments.
Buying Policy
The average commitment lead time for Capital Expenditures in April was 174 days, an increase of four days compared to March. The average lead time in April for Production Materials was 81 days, a decrease of one day compared to March. The average lead time for Maintenance, Repair and Operating (MRO) Supplies was 46 days, an increase of two days compared to March.
Percent Reporting
Capital
Expenditures
Hand-to-
Mouth
30 Days
60 Days
90 Days
6 Months
1 Year+
Average
Days
Apr 2026
15
4
7
13
35
26
174
Mar 2026
17
3
10
12
32
26
170
Feb 2026
18
3
7
14
27
31
179
Jan 2026
18
5
9
10
30
28
172
Percent Reporting
Production
Materials
Hand-to-
Mouth
30 Days
60 Days
90 Days
6 Months
1 Year+
Average
Days
Apr 2026
7
26
25
28
10
4
81
Mar 2026
8
26
27
26
7
6
82
Feb 2026
9
25
26
26
10
4
79
Jan 2026
8
26
26
27
9
4
79
Percent Reporting
MRO Supplies
Hand-to-
Mouth
30 Days
60 Days
90 Days
6 Months
1 Year+
Average
Days
Apr 2026
27
36
18
14
4
1
46
Mar 2026
29
38
15
13
4
1
44
Feb 2026
29
37
18
11
3
2
46
Jan 2026
31
37
15
12
5
0
41
About This Report
DO NOT CONFUSE THIS NATIONAL REPORT with the various regional purchasing reports released across the country. The national report’s information reflects the entire U.S., while the regional reports contain primarily regional data from their local vicinities. Also, the information in the regional reports is not used in calculating the results of the national report. The information compiled in this report is for the month of April 2026.
The data presented herein is obtained from a survey of manufacturing supply executives based on information they have collected within their respective organizations. ISM® makes no representation, other than that stated within this release, regarding the individual company data collection procedures. The data should be compared to all other economic data sources when used in decision-making.
Data and Method of Presentation
The ISM® Manufacturing PMI® Report is based on data compiled from purchasing and supply executives nationwide. The composition of the Manufacturing Business Survey Panel is stratified according to the North American Industry Classification System (NAICS) and each of the following NAICS-based industries’ contribution to gross domestic product (GDP): Food, Beverage & Tobacco Products; Textile Mills; Apparel, Leather & Allied Products; Wood Products; Paper Products; Printing & Related Support Activities; Petroleum & Coal Products; Chemical Products; Plastics & Rubber Products; Nonmetallic Mineral Products; Primary Metals; Fabricated Metal Products; Machinery; Computer & Electronic Products; Electrical Equipment, Appliances & Components; Transportation Equipment; Furniture & Related Products; and Miscellaneous Manufacturing (products such as medical equipment and supplies, jewelry, sporting goods, toys and office supplies). The data are weighted based on each industry’s contribution to GDP. According to U.S. Bureau of Economic Analysis (BEA) estimates (the average of the fourth quarter 2024 GDP estimate and the GDP estimates for first, second, and third quarter 2025, as released on January 22, 2026), the six largest manufacturing industries are: Chemical Products; Transportation Equipment; Food, Beverage & Tobacco Products; Computer & Electronic Products; Machinery; and Petroleum & Coal Products.
Survey responses reflect the change, if any, in the current month compared to the previous month. For nine indicators (New Orders, Backlog of Orders, New Export Orders, Imports, Production, Supplier Deliveries, Inventories, Employment, and Prices), this report shows the percentage reporting each response, the net difference between the number of responses in the positive economic direction (higher, better and slower for Supplier Deliveries) and the negative economic direction (lower, worse and faster for Supplier Deliveries), and the diffusion index. For Customers’ Inventories, respondents report their assessment of their customers’ stock levels of respondent companies’ products this month (rather than last month): too high, about right, and too low. Responses are raw data and are never changed. The diffusion index includes the percent of positive responses plus one-half of those responding the same (considered positive).
The resulting single index number for those meeting the criteria for seasonal adjustments (Manufacturing PMI®, New Orders, Production, Employment and Inventories) is then seasonally adjusted to allow for the effects of repetitive intra-year variations resulting primarily from normal differences in weather conditions, various institutional arrangements, and differences attributable to non-moveable holidays. All seasonal adjustment factors are subject annually to relatively minor changes when conditions warrant them. The Manufacturing PMI® is a composite index based on the diffusion indexes of five of the indexes with equal weights: New Orders (seasonally adjusted), Production (seasonally adjusted), Employment (seasonally adjusted), Supplier Deliveries, and Inventories (seasonally adjusted).
Diffusion indexes have the properties of leading indicators and are convenient summary measures showing the prevailing direction of change and the scope of change. A Manufacturing PMI® reading above 50 percent indicates that the manufacturing economy is generally expanding; below 50 percent indicates that it is generally declining. A Manufacturing PMI® above 47.5 percent, over a period of time, indicates that the overall economy, or gross domestic product (GDP), is generally expanding; below 47.5 percent, it is generally declining. The distance from 50 percent or 47.5 percent is indicative of the extent of the expansion or decline. With some of the indicators within this report, ISM® has indicated the departure point between expansion and decline of comparable government series, as determined by regression analysis. For the Customers’ Inventories Index, numerically, a reading: above 50 percent is “too high,” equal to 50 percent is “about right,” and below 50 percent is “too low.” However, in practice and in the context of other data, customers’ inventories may be considered to be “about right” if the diffusion index is between 52 percent (the high side of about right) and 48 percent (the low side of about right).
The ISM® Manufacturing PMI® Report survey is sent out to Manufacturing Business Survey Panel respondents the first part of each month. Respondents are asked to report on information for the current month for U.S. operations only. ISM® receives survey responses throughout most of any given month, with the majority of respondents generally waiting until late in the month to submit responses to give the most accurate picture of current business activity. ISM® then compiles the report for release on the first business day of the following month.
The industries reporting growth, as indicated in the ISM® Manufacturing PMI® Report, are listed in the order of most growth to least growth. For the industries reporting contraction or decreases, those are listed in the order of the highest level of contraction/decrease to the least level of contraction/decrease.
Responses to Buying Policy reflect the percent reporting the current month’s lead time, the approximate weighted number of days ahead for which commitments are made for Capital Expenditures; Production Materials; and Maintenance, Repair and Operating (MRO) Supplies, expressed as hand-to-mouth (five days), 30 days, 60 days, 90 days, six months (180 days), a year or more (360 days), and the weighted average number of days. These responses are raw data, never revised, and not seasonally adjusted.
ISM PMI® Content
The Institute for Supply Management® (“ISM®”) PMI® Reports, formerly Report On Business®, (Manufacturing and Services reports) (“ISM PMI®”) contain information, text, files, images, video, sounds, musical works, works of authorship, applications, and any other materials or content (collectively, “Content”) of ISM (“ISM PMI® Content”). ISM PMI® Content is protected by copyright, trademark, trade secret, and other laws, and as between you and ISM, ISM owns and retains all rights in the ISM PMI® Content. ISM hereby grants you a limited, revocable, nonsublicensable license to access and display on your individual device the ISM PMI® Content (excluding any software code) solely for your personal, non-commercial use. The ISM PMI® Content shall also contain Content of users and other ISM licensors. Except as provided herein or as explicitly allowed in writing by ISM, you shall not copy, download, stream, capture, reproduce, duplicate, archive, upload, modify, translate, publish, broadcast, transmit, retransmit, distribute, perform, display, sell, or otherwise use any ISM PMI® Content.
Except as explicitly and expressly permitted by ISM, you are strictly prohibited from creating works or materials (including but not limited to tables, charts, data streams, time-series variables, fonts, icons, link buttons, wallpaper, desktop themes, online postcards, montages, mashups and similar videos, greeting cards, and unlicensed merchandise) that derive from or are based on the ISM PMI® Content. This prohibition applies regardless of whether the derivative works or materials are sold, bartered, or given away. You shall not either directly or through the use of any device, software, internet site, web-based service, or other means remove, alter, bypass, avoid, interfere with, or circumvent any copyright, trademark, or other proprietary notices marked on the Content or any digital rights management mechanism, device, or other content protection or access control measure associated with the Content including geo-filtering mechanisms. Without prior written authorization from ISM, you shall not build a business utilizing the Content, whether or not for profit.
You shall not create, recreate, distribute, incorporate in other work, or advertise an index of any portion of the Content unless you receive prior written authorization from ISM. Requests for permission to reproduce or distribute ISM PMI® Content can be made by contacting in writing at: ISM Research, Institute for Supply Management, 309 West Elliot Road, Suite 113, Tempe, Arizona 85284-1556, or by emailing kcahill@ismworld.org. Subject: Content Request.
ISM shall not have any liability, duty, or obligation for or relating to the ISM PMI® Content or other information contained herein, any errors, inaccuracies, omissions or delays in providing any ISM PMI® Content or for any actions taken in reliance thereon. In no event shall ISM be liable for any special, incidental, or consequential damages arising out of the use of the ISM PMI®. Report On Business®, PMI®, Manufacturing PMI® and Services PMI® are registered trademarks of Institute for Supply Management®. Institute for Supply Management® and ISM® are registered trademarks of Institute for Supply Management, Inc.
About Institute for Supply Management® (ISM®)
Institute for Supply Management® (ISM®) is the first and leading not-for-profit professional supply management organization worldwide. Its community of more than 50,000 in more than 100 countries around the world manage about US$1 trillion in corporate and government supply chain procurement annually. Founded in 1915 by practitioners, ISM is committed to advancing the strategy and practice of integrated, end-to-end supply chain management through leading edge data-driven resources, community, and education to empower individuals, create organizational value and to drive competitive advantage. ISM’s vision is to foster a prosperous, sustainable world. ISM empowers and leads the profession through the ISM® PMI® Reports (formerly Report On Business®), its highly regarded certification and training programs, corporate services, events and assessments. The ISM® PMI® Reports — Manufacturing and Services — are two of the most reliable economic indicators available, providing guidance to supply management professionals, economists, analysts, and government and business leaders. For more information, please visit: www.ismworld.org.
The full text version of the ISM® Manufacturing PMI® Report is posted on ISM®’s website at www.ismrob.org on the first business day* of every month after 10:00 a.m. ET. The one exception is in January when the report is released on the second business day of the month.
The next ISM® Manufacturing PMI® Report featuring May 2026 data will be released at 10:00 a.m. ET on Monday, June 1, 2026.
*Unless the New York Stock Exchange is closed.
Contact:
Kristina Cahill
PMI® Reports Analyst
ISM®, PMI®/Research Manager
Tempe, Arizona
+1 480.455.5910
Email: kcahill@ismworld.org
View original content to download multimedia:https://www.prnewswire.com/news-releases/manufacturing-pmi-at-52-7-april-2026-ism-manufacturing-pmi-report-302759226.html
SOURCE Institute for Supply Management
You may like
Technology
Linktel Technologies Highlights Breakthrough 1.6T LPO Performance & Strong Market Pull at OCP 2026
Published
18 minutes agoon
October 18, 2026By

SAN JOSE, Calif., Oct. 18, 2026 /PRNewswire/ — At the recent 2026 OCP Global Summit, Linktel Technologies showcased its cutting-edge optical interconnect portfolios engineered specifically for next-generation AI computing networks. Among the heavy lineup, Linktel’s 1.6T Linear Pluggable Optics (LPO) solutions commanded immense industry attention, drawing heavy customer interest for their unprecedented energy efficiency, ultra-low latency, and supply-chain resilience.
Spotlight: 1.6T LPO Performance & High Customer Traction
AI data centers face immense scaling pressures, demanding higher bandwidth densities with tighter thermal and power budgets. Linktel’s 1.6T LPO solutions—highlighted by the 1.6T LPO 2DR4—delivered standout performance metrics that captured the spotlight at the summit:
Ultra-Low Power Consumption: Operates with power consumption as low as an impressive 10W, drastically mitigating data center cooling and power loads.Minimal Latency: Features a linear optics architecture that cuts down signal processing delays, making it a critical asset for high-performance AI scale-out fabrics.Enhanced Supply-Chain Resilience: Eliminating the optical DSP mitigates component choke points, ensuring robust scalability for mass deployments.Proven Interoperability: Following its breakthrough performance and multi-switch platform interoperability at the early September 2026 1.6T LPO-MSA Plugfest, Linktel has laid a solid foundation for the 200G-per-wavelength ecosystem.
Surging Market Interest
Throughout OCP 2026, Linktel’s live demonstrations of its 1.6T LPO, LRO, and FRO modules drew crowds of data center architects and industry partners. With volume production already in place, Linktel is fully equipped to meet the exploding market demand for energy-efficient, high-density 1.6T connectivity.
Overview of Other Innovations at OCP 2026
In addition to the heavily requested 1.6T LPO lineup, Linktel showcased two other major high-speed architectural pillars:
12.8T Liquid-Cooled XPO:Featured a live thermal demonstration integrating advanced liquid cooling to guarantee stable operations in high-density AI nodes.As a founding member of the XPO MSA, Linktel is actively scaling XPO series with FRO, LRO, and LPO variants for comprehensive scale-up, scale-out, and scale-across frameworks.6.4T/7.2T NPO Modules:Displayed with covers removed to reveal internal architectural designs supporting both ELS and ILS configurations.Combines compact high density with low power and low latency, backed by an established 6.4T/7.2T NPO roadmap.DMD Technology & Executive Presentation:Linktel Engineer Director Dr. Grace Zhang hosted a heavily attended Executive Session titled “Dispersion Managed Transceiver for Next-Gen AI Fabrics,” detailing cost-effective 800G (20km) and 1.6T (10km) solutions for OCS SuperPOD architectures, as well as the feasibility of 400G per lambda (3km).With its DMD product line already in volume production, Linktel actively calls upon ecosystem partners to join forces in collaborative development. To drive ecosystem maturity, Linktel is open to sharing its U.S.-filed patents, paving the way for industry-wide adoption and advancements in next-gen AI fabrics.
About Linktel Technologies
Linktel Technologies is a global leader in optical transceiver development and manufacturing, supplying high-speed optical I/O connectivity—including pluggable transceivers, optical engines, and ODM/JDM services.
For more information, visit www.linktel.com or follow Linktel Technologies on LinkedIn.
View original content:https://www.prnewswire.com/news-releases/linktel-technologies-highlights-breakthrough-1-6t-lpo-performance–strong-market-pull-at-ocp-2026–302911973.html
SOURCE Linktel Technologies
Technology
Advanced Manufacturing in Focus: Smart Life and Robotics Take the Spotlight at 140th Canton Fair
Published
1 hour agoon
October 18, 2026By
GUANGZHOU, China, Oct. 18, 2026 /CNW/ — Phase 1 of the 140th Canton Fair, themed “Advanced Manufacturing,” opened on October 15 and will run through October 19. As one of the event’s most closely watched sections, the Consumer Electronics and Information Products zone once again serves as a showcase for the latest achievements in China’s manufacturing and technology industries.
Smart Life Solutions Address an Aging and Globalized Market
A highlight of this section is the focus on smart living, which brings together smart solutions designed to support healthier, safer, and more independent lifestyles.
For example, wearable devices and continuous glucose monitoring systems enable convenient tracking of key health indicators such as heart rate and blood glucose levels. Meanwhile, wearable exoskeletons and other AI-powered devices support mobility training and functional recovery. For home and elderly care, companion robots, electric nursing beds and home-use hyperbaric oxygen chambers, offer a combination of daily care, wellness support and lifestyle assistance. All these solutions highlight a growing shift toward technology-enabled living, where health management, personal care, and independent living are becoming more accessible and connected.
Service Robots Demonstrate Expanding Real-World Applications
The Service Robot Zone remains one of the fair’s most popular attractions in this edition.
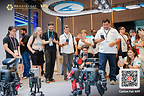
Among the crowd favorites is a humanoid robot standing roughly 70–80 centimeters tall. With its expressive movements and playful appearance, the robot draws constant attention as it dances, approaches visitors and occasionally performs flips to the delight of onlookers. Behind the product is a company that has overcome key challenges in compact joint modules and modular humanoid robot development. Its independently developed high-power-density joints deliver remarkable agility and explosive movement, while modular architecture provides flexibility for a wide range of future applications.
More broadly, the Service Robot Zone features exhibits spanning a wide range of application areas, including embodied intelligence, specialized operations, urban services, and smart living. Full-size humanoid robots, dexterous hands with multimodal sensing capabilities and wheeled robots highlight the latest advances in artificial intelligence, perception technologies and motion control. For demanding industrial and emergency environments, exhibitors are presenting robotic inspection systems, live-line maintenance robots and underwater propulsion robots designed to improve safety and operational efficiency.
The commercial services sector is also well represented through reception robots, façade-cleaning robots and fully automated coffee kiosks, while everyday life applications include wearable exoskeletons, robotic lawn mowers and educational robots for home use. Together, these exhibits demonstrate how China’s robotics industry is accelerating its transition from technological innovation to large-scale commercialization.
As the 140th Canton Fair gets underway, the showcased innovations highlight China’s growing strength in advanced manufacturing, turning cutting-edge technologies into practical, market-ready solutions for global customers.
For more convenient attendance, please click here for pre-registration:
https://buyer.cantonfair.org.cn/register/buyer/email?source_type=16
View original content to download multimedia:https://www.prnewswire.com/news-releases/advanced-manufacturing-in-focus-smart-life-and-robotics-take-the-spotlight-at-140th-canton-fair-302911955.html
SOURCE Canton Fair
Technology
October 2026 Global Sources Hong Kong Shows Phase II Opens Today
Published
1 hour agoon
October 18, 2026By
Asia’s first dedicated B2B Pre-Owned Mobile Devices focus pavilion
Tencent Brings AI Ecosystem Products to the Show
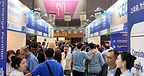
HONG KONG, Oct. 18, 2026 /PRNewswire/ — Phase II of the October 2026 Global Sources Hong Kong Shows opened today at AsiaWorld-Expo, running from October 18 to 21. The four-day event focuses on four core tracks — mobile electronics, smart home security and appliances, lifestyle electronics, and sports and outdoor — bringing together more than 2,100 quality Asian suppliers across more than 4,000 booths, showcasing approximately 160,000 new products including mobile devices, smart wearables, AR/VR, smart home, energy storage and charging, personal health care, pet products, and sports and outdoor equipment.
John Kao, Vice President of Hong Kong Shows & Overseas Shows at Global Sources, said: “Hong Kong possesses a regulatory framework aligned with international standards, efficient intellectual property protection, and proximity to the Greater Bay Area’s manufacturing heartland — enabling it to meet buyers’ dual demands for compliance and efficiency. Buyers no longer need to travel to multiple locations: right here in Hong Kong, they can assess Asian manufacturing supply, complete compliance reviews, and place orders — all in a single visit. The trust established between buyers and sellers on site is often difficult to achieve through months of email exchanges. We aim to continuously strengthen Hong Kong’s role as an international trade hub, enabling genuinely capable suppliers and serious buyers to connect efficiently on this platform.”
Asia’s First B2B Phone Trade Focus Pavilion Officially Debuts
Hong Kong has long been an important transit hub for the global second-hand phone trade. According to IDC data, global used smartphone shipments reached 225.7 million units in 2024 and are projected to maintain a compound annual growth rate of 4.9% through 2029. While the market continues to expand, compliant distribution capability remains the key threshold for entering this space.
For the first time, the show has partnered with the Hong Kong International Communications Electronic Chamber (HKICEC) to unveil the “HKICEC Global Mobile Exchange Pavilion,” Asia’s first dedicated B2B pavilion for Pre-Owned Mobile Devices. The pavilion brings together nearly 60 leading companies from Chinese Mainland, Hong Kong SAR, India, Japan, the United Arab Emirates, the United States, the United Kingdom, and beyond — including Zhuan Zhuan, ATRenew, US Mobile Phones Inc., Belong Inc., and ecoATM LLC — exhibits and services span new mobile devices, professionally tested and data-sanitized refurbished smart devices compliant with EU WEEE standards, intelligent testing technologies, recycling solutions, and compliant export services. The pavilion offers buyers from Europe, North America, and Southeast Asia a trusted and comprehensive sourcing platform, creating a green trade corridor that connects Chinese Mainland’s manufacturing strengths, Hong Kong SAR’s international platform, and global markets.
Tencent AI Makes Show Debut; AI Mass Production Enters the Delivery Phase
The product selection logic for AI products has undergone a marked shift in the second half of the year. The focus has moved entirely from “What new AI products are available?” to deployment capability and delivery efficiency — no longer chasing feature gimmicks alone, buyers place greater emphasis on whether products can effectively address real needs and ship reliably on schedule. Suppliers’ overall fulfillment capability has surpassed mere product highlights to become the primary assessment criterion in sourcing decisions. The Phase II “AI+ Theme Zone” features over 1,200 booths spanning seven segments: AI terminal devices, AI wearables, AI glasses, AI toys, AI pet products, AI personal health devices, and AI-integrated products, showcasing suppliers’ proven ability to move from concept to mass production. The zone also extends to lifestyle electronics including wearable electronics, smart pet products, personal care and beauty tech, sports, outdoor and fitness tech, gifts, and smart living, covering a wide range of real-world application scenarios.
Tencent joins forces with its ecosystem partners to exhibit under the theme “AI-Empowered Business Growth,” showcasing Tencent’s AI office assistant WorkBuddy alongside enterprise-grade AI solutions from ecosystem partners, including the AI-powered business growth tool Buda.im and Busabase. Running concurrently with the fair, the “AI Agent Summit” brings together over 100 industry, investment and technology leaders to explore how AI Agents are moving beyond demos into real-world deployment and revenue generation, with in-depth discussions on commercialisation pathways, industry standardisation and emerging opportunities across the AI Agent ecosystem. In addition, the show has partnered with the Taiwan Electrical and Electronic Manufacturers’ Association (TEEMA) to launch a Taiwan AI Supply Chain Theme Pavilion, showcasing the region’s established industrial cluster strengths in AI modules, components, and contract manufacturing.
Vietnamese Manufacturing and Mobile Accessories Take Center Stage; Diverse Sourcing Zones Debut
Phase II features a dedicated “Vietnam Sourcing Fair” zone, bringing together approximately 50 Vietnamese manufacturers with mature export capabilities, covering three product categories: fashion products and apparel, home and kitchenware, and gifts and packaging. For buyers seeking to diversify sourcing risks, the zone enables them to simultaneously access China’s main supply chain and Vietnam’s emerging production capacity at the same show, and negotiate directly face-to-face with Vietnamese factories.
With new-generation flagship smartphones from major brands hitting the market, demand for compatible mobile accessories is ramping up. The show floor features over 2,000 mobile-accessory booths showcasing new offerings including phone cases, charging gear, stands, and data cables, providing global buyers with an extensive range of options. The event also hosts the “Global Buyer’s Top Picks” creative phone-case contest to identify case designs with strong market potential.
The concurrent Hong Kong Security Tech Show, supported by the China Chamber of Commerce for Import and Export of Machinery and Electronic Products (CCCME), showcases products and solutions spanning security surveillance, smart access control, and cybersecurity.
Best of Innovation Awards Recognize Outstanding Products; Global New Product Launches Converge in Hong Kong
The Phase II Best of Innovation Awards focus on products across mobile electronics, smart home, security and appliances, lifestyle electronics, and sports and outdoor categories, with judging criteria emphasizing practicality, cost-effectiveness, technological maturity, and market relevance — identifying innovative products with genuine commercial deployment potential. Phase II also introduces a dedicated “AI Innovation Award” to recognize exhibits with outstanding applications of AI technology. The awards program continues its partnership with the internationally renowned European Product Design Award (EPDA)™ to present the “Best Product Design Award,” honoring products that combine innovative thinking with exceptional design. The show also serves as the preferred launch platform for multiple exhibitors’ annual new products, featuring heavyweight global and Asia premieres that further consolidate Hong Kong’s position as the world’s premier stage for consumer electronics product debuts.
About Global Sources
Global Sources is an internationally recognized multi-channel trade platform, connecting Asia with the world for 55 years. The company has been dedicated to facilitating global trade by connecting verified suppliers with qualified buyers worldwide. To date, it has successfully served more than 14 million registered buyers and users globally, providing efficient and convenient trade solutions.
View original content to download multimedia:https://www.prnewswire.com/apac/news-releases/october-2026-global-sources-hong-kong-shows-phase-ii-opens-today-302911972.html
SOURCE Global Sources

Linktel Technologies Highlights Breakthrough 1.6T LPO Performance & Strong Market Pull at OCP 2026

Advanced Manufacturing in Focus: Smart Life and Robotics Take the Spotlight at 140th Canton Fair

October 2026 Global Sources Hong Kong Shows Phase II Opens Today

Send Rakhi to UK swiftly with UK Gifts Portal

Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

Nullmax and Renesas Forge Strategic Partnership to Deliver Competitive ADAS Solutions for the Global Market

Why You Should Build on #NEAR – Co-founder Illia Polosukhin at CV Labs
Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

NEAR End of Year Town Hall 2021: The Open Web World, MetaBUILD 2 Hackathon and 2021 recap
Trending
-
 Technology5 days ago
Cresta Launches Deputy Agent: an AI Agent That Keeps Working Long After the Customer Hangs Up
-
 Technology5 days ago
Collective X Health Launches With a $3.2 Million Pre-Seed Round to Close the Women’s Health Data Gap
-
 Technology5 days ago
SUBSCRIBE Launches 1031 DST Exchange Transaction Platform
-
 Technology5 days ago
MassPay Adds Paymode Virtual Card and Premium ACH to Its Platform
-
 Coin Market5 days ago
Digital cash offers ‘cash-like privacy,’ but bank data breaches threaten users: BIS
-
 Technology5 days ago
Celebree School Rises on the 2026 Franchise Times Top 400 for a Third Straight Year
-
Technology5 days ago
Voxel Advances System of Reality Capabilities and Fuels Global Expansion with Addition of Ventral AI
-
 Technology5 days ago
Speakeasy and Tailscale bring private networking to enterprise MCP