Connect with us

Technology

Gold Loan EMI or Bullet Repayment: Muthoot Finance Helps Choose Right in 2026

Published

on

NEW DELHI, July 27, 2026 /PRNewswire/ — With India’s updated gold loan regulations now in effect, Muthoot Finance has issued a market advisory highlighting how borrowers can make informed repayment choices by selecting between EMI and Bullet Repayment options based on their financial needs. As borrowers adapt to the revised regulatory framework in 2026, the company emphasises that choosing the right repayment structure is as important as selecting the loan itself.

Muthoot Finance notes that with the gold rate today exhibiting notable fluctuations driven by shifting global economic cycles, unlocking the latent value of gold ornaments has become an increasingly sophisticated financial strategy. As borrowers weigh how to convert this idle wealth into working capital in 2026, Muthoot Finance, one of India’s long-established gold loan financing companies, is drawing attention to a decision that often matters as much as the loan itself: how the money is repaid. Accessing equity is only half the equation; structuring the payback framework wisely is what preserves long-term financial health. The company notes that the choice between an Equated Monthly Instalment (EMI) framework and a lump-sum Bullet Repayment scheme has become a critical crossroads for everyday credit seekers, and one that demands even greater scrutiny today given the comprehensive regulatory changes now governing the asset class.

Unpacking the Operational Frameworks

The advisory explains that a gold loan functions as a secured credit facility where physical jewellery serves as collateral to secure short-term funds. The total eligible credit amount is determined by the Loan-to-Value (LTV) ratio, which reflects the maximum percentage of the metal’s market worth that a lender can advance.

Under a conventional monthly structure, the company explains, the borrower pays structured installments containing both interest and principal components. This systematic reduction steadily shrinks the outstanding liability over the agreed tenure. Conversely, a Bullet Repayment scheme permits the borrower to defer the entirety of the principal and accrued interest until the final day of the loan agreement, leaving monthly operational cash flows completely untouched.

The 2026 Regulatory Landscape and Asset Protection

Muthoot Finance points out that the financial decision-making process for credit seekers has shifted profoundly due to the comprehensive regulatory framework enforced by the Reserve Bank of India (RBI). The updated directives have instituted a strict tiered LTV structure tailored to the size of the borrowing request. For smaller, micro-ticket credit lines up to ₹2.5 lakh, the allowed LTV ratio scales up to 85%, providing deeper liquidity for small traders and households. Mid-tier advances between ₹2.5 lakh and ₹5 lakh operate under an 80% LTV cap, while larger credit requirements exceeding ₹5 lakh are capped strictly at 75%.

For bullet options, the advisory notes, the guidelines have established a firm 12-month tenure cap on consumption-driven bullet loans to prevent systemic debt cycles. Crucially, the calculation of the LTV for a bullet loan must factor in the total maturity value—encompassing both the initial principal and the projected interest accumulation—ensuring that total liabilities remain well-cushioned against unexpected drops in precious metal values.

Direct Comparison: Structural Trade-Offs

Muthoot Finance suggests that utilizing an online gold loan calculator can offer instant clarity on monthly obligations before finalizing structural terms. The advisory sets out how these paths diverge:

Evaluation Metrics

Monthly EMI Repayment Plan

Bullet Repayment Plan

Repayment Frequency

Fixed monthly outlays

Single lump-sum at maturity

Maximum Tenure Cap

Flexible (up to 24–36 months)

Capped tightly at 12 months

Interest Cost Over Time

Lower total outgo via reducing balance

Higher overall interest cost because interest continues to accrue on the outstanding principal until repayment.

Cash Flow Impact

Requires disciplined monthly budgeting

Keeps short-term monthly revenue completely free

Ideal Demographics

Salaried employees with predictable income

Seasonal business owners, agricultural traders

Muthoot Finance notes that, generally, EMI repayment tends to suit borrowers with predictable monthly income, while Bullet Repayment may be more suitable for those expecting a defined future inflow, such as seasonal business earnings or a scheduled payment.

“The rate a customer is quoted matters, but the repayment structure decides what that rate actually costs them,” said George Alexander Muthoot, Managing Director, Muthoot Finance. “A bullet repayment protects monthly cash flow, and for a farmer or a trader waiting on a seasonal inflow, that is the right choice. For a salaried borrower with predictable income, an EMI usually works out lower across the full tenure. We would rather customers weigh that trade-off before they sign than discover it at maturity.”

Debunking Core Market Myths

The advisory also addresses a persistent myth among borrowing circles: that a bullet plan is inherently more economical because it lacks immediate monthly obligations. In reality, because interest generally continues to accrue on the outstanding principal throughout the loan tenure, the total interest payable may be higher than under a reducing-balance EMI structure, depending on the lender’s interest calculation method.

Another common anxiety the advisory addresses involves operational delays in reclaiming physical jewellery once a liability is cleared. Under the updated regulatory environment, any institution failing to return the pledged ornaments within seven working days of full loan closure must pay a daily compensation of ₹5,000 to the customer. This mandate highlights the value of dealing with an established national financial institution like Muthoot Finance. Their highly reliable branch infrastructure handles documentation seamlessly, supporting secure custody of pledged jewellery and timely release after loan closure, subject to applicable regulatory requirements.

Strategic Steps for Informed Choice

Muthoot Finance recommends that borrowers work through the following before committing to a repayment structure:

Analyse Revenue Velocity: If a small business owner anticipates a guaranteed capital inflow or a seasonal invoice clearance within 6 to 9 months, a bullet structure keeps immediate operational funds liquid.Measure Absolute Costs: Running precise scenarios on a standardized gold loan calculator allows a side-by-side evaluation of the absolute interest weight under each path.Leverage Favourable Windows: Exercise gentle urgency when monitoring market movements. Since the gold price influences the valuation of pledged jewellery under the applicable LTV framework, higher market prices may increase the eligible loan amount, subject to lender policies and RBI guidelines.Examine the Key Fact Statement: Carefully audit the annualized gold loan interest rates and upfront processing fees stated on the mandatory KFS document before signing.

Navigating Tomorrow with Financial Confidence

Muthoot Finance concludes that choosing the appropriate credit structure relies on aligning repayment terms with predictable revenue streams. Balancing immediate cash flow relief against the long-term interest burden prevents unnecessary financial strain. For individuals looking to accurately evaluate their options under the modern regulatory rules, accessing an interactive gold loan EMI calculator serves as an invaluable diagnostic tool. Partnering with an established financial institution that follows applicable regulatory requirements can help borrowers access transparent processes and secure gold loan servicing.

About Muthoot Finance:

Muthoot Finance is India’s largest gold loan NBFC, dedicated to providing seamless credit access to millions of customers. With a vast national branch network, the company offers gold loans, foreign exchange, and wealth management services.

Media Contact: mails@muthootgroup.com

View original content to download multimedia:https://www.prnewswire.com/in/news-releases/gold-loan-emi-or-bullet-repayment-muthoot-finance-helps-choose-right-in-2026-302835251.html

Continue Reading

Technology

LianLian Global and PayPal Power Cross-Border Payouts for Social Commerce, Marketplace, and eCommerce Customers

Published

on

By

Social commerce, marketplaces and eCommerce players served by LianLian Global can now pay creators, influencers, developers, and independent contractors directly to their PayPal and Venmo wallets.

NEW YORK, Oct. 22, 2026 /PRNewswire/ — LianLian Global  today announced it has partnered with PayPal (NASDAQ: PYPL) to enable its social commerce, marketplace and e-commerce clients to send payouts directly to PayPal accounts globally and to Venmo accounts in the U.S.

The creator and gig economy runs on fast, low-friction payouts. Brands are expected to spend $32.6 billion on creators in 2026 and roughly 50 million people worldwide create content professionally or semi-professionally (Gigapay Global Creator Economy Report 2026). Many of these recipients already hold a PayPal or Venmo account: PayPal had over 400 million active accounts across approximately 200 markets at the end of Q2 2026, and Venmo reached 67 million monthly active accounts in Q4 2025.

Paypal Payouts is live in 96 global markets and 24 currencies. It allows merchants to send to any email address, mobile number, or Venmo user handle, with or without an existing PayPal or Venmo account.

To support enterprises expanding globally, LianLian Global provides digital payment services including pay-in, pay-out, acquiring, foreign exchange, virtual cards and payment aggregation. To date, its parent company Lianlian DigiTech has served more than 13.3 million clients. Its services reach more than 200 countries and regions, support transactions and settlement in more than 140 currencies, and connect with more than 180 global e-commerce platforms.

The partnership combines LianLian Global’s cross-border collection, FX and compliance infrastructure with PayPal’s global wallet network. Key offerings include:

Pay to PayPal: Payouts from LianLian Global clients to PayPal account holders in 96 markets, using only the recipient’s email or phone numberPay to Venmo: Domestic U.S. payouts to Venmo users, including creators, influencers and independent contractorsPayPal Payouts for Platforms: Mass disbursements for social commerce, marketplaces and affiliate platforms paying large numbers of sellers, creators and contractorsSpeed to settle: Save time and money by eliminating check runs and postage; no need for routing numbers and bank accounts.

Sandra Lam, Deputy CEO of US at LianLian Global: “Social commerce is creating a new economy, where creators, influencers and independent sellers drive discovery and sales alongside the platforms they sell on. Paying these participants fast, across borders and in small amount is what powers the network effect of social commerce. We see our work with Paypal as a key step in building the payout rails for the global gig economy.”

The collaboration expands LianLian Global’s payout coverage and supports its growth in the U.S. and global markets as cross-border platforms scale their creator and contractor programs.

View original content:https://www.prnewswire.com/news-releases/lianlian-global-and-paypal-power-cross-border-payouts-for-social-commerce-marketplace-and-ecommerce-customers-302917635.html

SOURCE LianLian Global

Continue Reading

Technology

Crab2B Debuts as Hong Kong’s First Dedicated B2B Platform for Mobile Electronics

Published

on

By

HONG KONG, Oct. 23, 2026 /PRNewswire/ — With the global population surpassing 8 billion, mobile electronics have become essential to modern life, with smartphones now used by billions of people. Across approximately 13,861 cities worldwide, electronics wholesalers play a vital role in the supply chain. Among the world’s three major wholesale hubs for digital electronics, Dubai serves the Middle East and Africa, Miami connects markets across Latin America, and Hong Kong draws strength from its unique position linking mainland China with global markets. According to Hong Kong Customs data, re-exports of used mobile phones from Hong Kong reached 51.5 million units in 2025, while the total value of electronics exports hit HK$3.9216 trillion. Yet despite its value running into the trillions of Hong Kong dollars, it has long lacked a dedicated online platform.

Crab2B was created to fill this gap as Hong Kong’s first B2B platform dedicated to mobile electronics. Inspired by Alibaba’s online B2B marketplace model, the platform focuses on consumer electronics, bringing together hundreds of thousands of buyers and sellers worldwide and enabling them to connect directly.

Crab2B covers a broad range of products, including smartphones, tablets, laptops and other smart devices. Listings span brand-new and used devices, as well as certified pre-owned (CPO) and as-is products. The platform also connects buyers and suppliers with service providers offering product inspection, international logistics and repair services. Users can search for products by brand and model, while all merchants undergo rigorous verification before joining the platform. With these safeguards in place, Crab2B is designed to meet the needs of businesses across the value chain, protect the interests of both buyers and sellers, and facilitate mutually beneficial transactions.

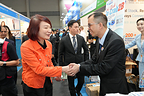
Building on Hong Kong’s established trading network, Crab2B made its debut at the HKICEC Global Mobile Exchange Pavilion during the Global Sources Hong Kong Shows, held at AsiaWorld-Expo from October 18 to 21, 2026, where it also launched the Crab2B app. Looking ahead, Crab2B will remain firmly rooted in Hong Kong while expanding its global reach, continuing to refine the platform to deliver a smarter, more comprehensive digital marketplace for mobile electronics. By helping international buyers identify suitable suppliers, simplifying cross-border sourcing and reducing transaction costs, Crab2B aims to support the continued growth of Hong Kong’s digital trade sector and contribute to the city’s long-term prosperity and stability.

View original content to download multimedia:https://www.prnewswire.com/apac/news-releases/crab2b-debuts-as-hong-kongs-first-dedicated-b2b-platform-for-mobile-electronics-302917652.html

SOURCE CRAB 2B TECHNOLOGY INVESTMENT CO., LIMITED

Continue Reading

Technology

AiMOGA Launches Global Robot Innovation: Mobo Debuts from Wuhu, Empowering Homes and Businesses

Published

on

By

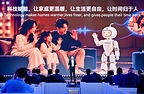
KUALA LUMPUR, Malaysia, Oct. 23, 2026 /PRNewswire/ — AiMOGA Robotics has officially launched Mobo, its first consumer-grade humanoid family companion robot, marking a new chapter in intelligent living for Malaysian households and enterprises. Unveiled globally from AiMOGA’s headquarters in Wuhu, China, during a joint international users summit with its sister brands, this groundbreaking product reflects the company’s commitment to worldwide innovation and technological excellence.

Standing 0.9 meters tall with 22 degrees of freedom, Mobo supports over 20 languages—including Bahasa Malaysia—and delivers rich, personalized interactions. Designed for family life, it offers children interactive learning, storytelling, and object recognition, while providing elders with conversational companionship and customizable reminders. Powered by MoAgent, AiMOGA’s embodied intelligence system, Mobo features a dual-brain architecture enabling real-time responses, multi-tasking capabilities, and adaptive learning through facial recognition and secure MogaCloud integration.

Peng Xia, AiMOGA Robotics Executive Vice President, said Mobo’s spatial perception, interaction, execution, decision-making, and cognition layers form a perception-decision-execution-feedback loop. Spatial memory enables object retrieval, while social navigation recognizes pedestrian paths and interaction zones. Multimodal technologies coordinate language, facial expressions, and movement for natural interaction.

Beyond home use, Mobo shows strong potential in professional settings—from customer service to logistics—supporting AiMOGA’s vision of integrating robotics into everyday workflows.

Since its debut in August 2026, Mobo has attracted over 10,000 prospective users. Thirty-five were selected as Global User Experience Officers, receiving one year of complimentary use to help shape future improvements.

At the event, Guibin Zhang, AiMOGA Robotics General Manager, outlined strategies in R&D, cost optimization, sales and leasing. The “Platform Institute + Scenario Institute” model drives validation for bipedal, quadruped, and wheeled robots. Plans include 300 global experience centers and “Jia Tian Xia”, a robot leasing brand launching in Wuhu. Leveraging Chery’s manufacturing and platform resources enhances cost efficiency and scalability.

Notably, AiMOGA’s impact in Malaysia is amplified through strategic collaboration with sister brands Chery, OMODA & JAECOO, iCAUR, and LEPAS. Their partnership extends far beyond vehicle showrooms and daily operations—jointly developing integrated smart ecosystems that span mobility, retail, smart offices, and connected living.

As part of a global rollout with over 3,000 units deployed across 60+ markets, this initiative aims to bring intelligent, accessible robotics to more Malaysian families and businesses—enhancing productivity, convenience, and quality of life.

View original content to download multimedia:https://www.prnewswire.com/apac/news-releases/aimoga-launches-global-robot-innovation-mobo-debuts-from-wuhu-empowering-homes-and-businesses-302917658.html

SOURCE AiMOGA Robotics

Continue Reading

Trending