
Technology
goeasy Ltd. Reports Results for the Second Quarter 2026

Published
3 months agoon
By
Gross Consumer Loans Receivable of $5.00 billion at Q2/26 end, down 2% from $5.11 billion at Q2/25
Revenue of $390 million in Q2/26, down 10% compared to $431 million in Q2/25
Net Charge Off Rate1 of 16.7% in Q2/26, up 800 bps from 8.7% in Q2/25
Diluted Earnings Per Share of $0.96 in Q2/26, down from diluted EPS of $5.49 in Q2/25
Adjusted Diluted Earnings Per Share1 of $1.02 in Q2/26, down from Adj. Dil. EPS1 of $4.40 in Q2/25
MISSISSAUGA, ON, Aug. 6, 2026 /CNW/ — goeasy Ltd. (TSX: GSY), (“goeasy” or the “Company”), one of Canada’s leading consumer lenders focused on delivering a full suite of financial services to Canadians with non-prime credit scores, today reported results for the second quarter ended June 30, 2026.
“We continued to methodically execute our six-point action plan in the second quarter, including managing our origination activity to prioritize liquidity. Compared to the first quarter of 2026, we reduced our net charge off rate by 110 basis points and strengthened our debt-to-adjusted tangible equity ratio from 5.30x to 4.95x,” said Patrick Ens, goeasy’s Chief Executive Officer. “We generated $585.4 million cash from operating activities before net principal written, repaid the full $314.0 million balance outstanding on our revolving credit facility and regained access to incremental draws on that facility as of July 1. We believe in the strength and durability of our business, and the actions we took in the second quarter have helped to reestablish our financial foundation to prudently grow originations.”
Second Quarter Results
During the quarter, the Company funded $272.1 million in gross loan originations, down 70% compared to $903.7 million in the second quarter of 2025. The decrease in lending, consistent with the Company’s six-point action plan, was primarily due to a reduction in merchant-originated automotive and powersports loan originations attributable to the implementation of tighter credit underwriting measures as those portfolios continued to exhibit unfavourable credit risk performance, and a moderation in direct-to-consumer loan originations, implemented to manage the Company’s liquidity.
Gross consumer loans receivable decreased 2% to $5.00 billion as at June 30, 2026 from $5.11 billion at the end of the second quarter of 2025, and decreased 7% from $5.36 billion at the end of the first quarter of 2026. The decrease in the Company’s average consumer loans receivable and lower total yield on consumer loans (including ancillary products) were the main drivers of the 10% decrease in revenue from $431.3 million in the second quarter of 2025 to $390.0 million in the second quarter of 2026. Total yield on consumer loans (including ancillary products) realized by the Company on its average consumer loans receivable1 was 28.3% in the quarter, down 340 bps from the same period in 2025, but up 40 bps from the first quarter of 2026. Total annualized yield decreased year-over-year mainly due to the impact of higher allowance for credit losses on interest receivable; credit tightening in merchant-originated loan originations and a moderate reduction in direct-to-consumer loan originations; the continued impact of the lowered maximum allowable rate of interest on the Company’s unsecured lending product; and a higher proportion of larger dollar value loans, which have lower yields on certain ancillary products.
During the quarter, net charge offs as a percentage of average gross consumer loans receivable1 was 16.7%, up 800 bps from 8.7% in the second quarter of 2025, but down 110 bps from the first quarter of 2026. Net charge offs as a percentage of average gross consumer loans receivable1 increased year-over-year primarily due to higher charge offs in the merchant-originated automotive and powersports loan portfolios, higher charge offs in the direct-to-consumer portfolio and lower average gross consumer loans receivable.
The total allowance for credit losses on gross consumer loans increased to $499.5 million from $406.7 million as at June 30, 2025, mainly due to the Company’s current view of collectability and an increase in the credit loss outlook for merchant-originated automotive and powersports loans. The rate of allowance for expected credit losses, defined as the allowance for credit losses on gross consumer loans receivable as a percentage of the ending gross consumer loans receivable, declined from 10.09% as at March 31, 2026 to 9.99% as at June 30, 2026, driven mainly by the favourable changes in the macroeconomic outlook incorporated into the Company’s IFRS 9 expected credit loss model. For the three-month period ended June 30, 2026, the net change in allowance for credit losses on gross consumer loans was negative $41.6 million, compared to $21.0 million in the same period of 2025, a decrease of $62.6 million. This decrease was primarily driven by the release of provision for credit losses resulting from the decline in gross consumer loans receivable during the three-month period ended June 30, 2026, as discussed above.
Operating income for the second quarter of 2026 was $99.6 million, down 41% from $167.7 million in the second quarter of 2025. After adjusting for unusual and non-recurring items, the Company reported adjusted operating income2 of $102.9 million, a decrease from $171.1 million in the second quarter of 2025. The efficiency ratio1 for the second quarter of 2026 was 25.5%, relatively flat from 25.6% in the second quarter of 2025.
Net income for the second quarter of 2026 was $15.9 million, down from net income of $91.5 million in the second quarter of 2025. Diluted earnings per share was $0.96, down from diluted earnings per share of $5.49 reported in the second quarter of 2025. Adjusted net income2 for the second quarter of 2026 was $16.8 million, down from adjusted net income2 of $73.4 million in the second quarter of 2025. The decrease in adjusted net income was primarily driven by lower adjusted operating income from lower total yield on consumer loans (including ancillary products), elevated credit losses and a higher cost of borrowing. Adjusted diluted earnings per share1 was $1.02, down from adjusted diluted earnings per share1 of $4.40 in the second quarter of 2025.
Balance Sheet and Liquidity
Total assets were $5.48 billion as at June 30, 2026, a decrease of 3% from $5.63 billion as at June 30, 2025, related primarily to a $224.5 million decrease in net consumer loans receivable, driven by lower originations during the period, higher charge offs recognized from the fourth quarter of 2025 to the second quarter of 2026, and impairment of goodwill related to the LendCare cash-generating unit. Cash provided by operating activities before net principal written2 in the second quarter of 2026 was $585.4 million, compared to $489.1 million in the second quarter of 2025. The Company’s debt-to-adjusted tangible equity ratio3, a capital management measure for leverage, was 4.95x as at June 30, 2026, compared to 3.71x as at June 30, 2025 and 5.30x as at March 31, 2026. The average blended coupon interest rate for the Company’s debt as at June 30, 2026 was 6.8%.
As at June 30, 2026, goeasy had liquidity (cash on hand plus unused contractual borrowing capacity) of $1.37 billion, of which $1.06 billion was not available to be drawn by the Company. On July 1, 2026, goeasy regained the ability to make incremental draws on its $550 million Revolving Credit Facility. In July 2026, the Company also received confirmation from the applicable lenders under its amended Revolving Securitization Facility I (the “Securitization Facility”) that the audit report required under that facility had been accepted and the related condition precedent to regaining access to the Securitization Facility (which is one of two such conditions) had been fulfilled. The Company has also meaningfully advanced steps to replace the backup servicer under the Securitization Facility and does not expect any impediments to meeting this condition, completion of which will permit additional draws on the Securitization Facility. Discussions between the Company and its lenders have also been initiated to extend the Securitization Facility for one year, however these discussions are preliminary and there is no assurance that such an extension will be agreed upon nor certainty as to the timing or terms of such an extension. The Company was in compliance with all of its covenants (including financial covenants) under its Revolving Credit Facility as at June 30, 2026. The Company was not subject to financial covenant compliance, and was in compliance with all other applicable covenants, for the Securitization Facility as at June 30, 2026.
Selected Additional Second Quarter Information
(June 30, 2026 relative to June 30, 2025, where applicable)
45% of gross consumer loans receivable secured, down from 48%Total number of active lending customers at 438,000, down 2%62% of net loan advances1 in the quarter were issued to new customers, down from 73%Weighted average interest rate4 on consumer loans of 26.3%, up from 26.1%87.9% of gross consumer loans receivable, on a dollar-weighted basis, carried an interest rate less than or equal to a 35% Annual Percentage Rate, being the maximum allowable interest rate for new loans written after January 1, 2025
Six Months Results
For the first six months of 2026, the Company funded $823.4 million in loan originations, down 48% from $1.58 billion in the same period of 2025. Total yield on consumer loans (including ancillary products) realized by the Company on its average consumer loans receivable1 was 28.1% in the first six months of 2026, down 340 bps from the same period in 2025. Net charge offs for the first six months of 2026, as a percentage of average gross consumer loans receivable1, was 17.3%, up 850 bps from 8.8% in the same period of 2025.
For the first six months of 2026, the Company produced revenues of $802.9 million, down 4% compared to $836.3 million in the same period of 2025. Operating income for the period was $128.5 million compared with $311.8 million in the first six months of 2025, a decrease of $183.3 million or 59%. Adjusted operating income2 for the first six months of 2026 was $139.8 million, 56% lower compared to $318.5 million in the same period of 2025. Efficiency ratio1 for the first six months of 2026 was 25.0%, an improvement of 90 bps from 25.9% in the same period of 2025.
Net loss for the first six months of 2026 was $37.1 million and diluted loss per share was $2.26 compared with net income of $130.2 million or $7.73 per share in the same period of 2025. Adjusted net loss2 for the first six months of 2026 was $14.5 million and adjusted diluted loss per share1 was $0.88, compared with adjusted net income2 of $132.7 million or $7.88 per share, both decreases of 111%.
Updated 2026 Outlook
The Company’s Q2 2026 outlook, and the relevant assumptions and risk factors, were disclosed in its March 31, 2026 MD&A. The Company’s actual second quarter performance was consistent with its second quarter 2026 outlook across all three measures. The Company continues to focus on prudent management of liquidity, strengthening of credit performance, and alignment of its capital structure. Management remains confident in goeasy’s ability to return to its long track record of strong credit performance and returns that will reinforce confidence among shareholders and other stakeholders.
The Company has updated its Q3 2026 outlook for gross consumer loans receivable and total yield on consumer loans for the full year 2026. This update assumes the continued implementation of the Company’s 6-point plan and reflects the Company’s expectations for the balance of the year. Refer to “Q3 2026 Outlook and Full Year 2026 Commentary” in the Company’s June 30, 2026 MD&A for more detail and to the assumptions and risks set out below under “Forward Looking Statements”.
Q3 2026 Outlook
Full Year 2026 Commentary
Gross consumer loans receivable at period end
$4.8 to $5.0 billion
Expected to be broadly in line with Q2 levels
Total yield on consumer loans (including ancillary products)1
26.5% to 28.0%
Expected to be broadly in line with H1 results
Net charge offs as a percentage of average gross consumer loans receivable1
14.5% to 16.0%
Expected to be in the mid-teens for full year 2026; improvement expected to continue as the year progresses
Chief Risk Officer Transition
The Company also announced today that Jason Appel will be leaving his role as Chief Risk Officer to pursue an external opportunity and will remain with goeasy through the end of August, to support an orderly transition. “I would like to thank Jason for his leadership and many contributions to goeasy over the past 13 years and wish him every success in the future,” said Patrick Ens, Chief Executive Officer. “Jason has played an important role in helping build and strengthen our Risk and Analytics capabilities and support goeasy’s growth and evolution.”
The Company has identified a successor and expects to announce the appointment before Jason Appel concludes his tenure with goeasy.
Share Repurchases and Dividend Payments
In consideration of recent developments that affected earnings in 2025, the Board of Directors made the decision to suspend the regular quarterly dividend on the Company’s Common Shares and to suspend share repurchases under its normal course issuer bid on an indefinite basis. These actions are aligned with management’s focus on prudently preserving capital and maintaining liquidity.
Forward-Looking Statements
This press release includes forward-looking statements about goeasy, including, but not limited to, its business operations, strategy and expected financial performance and condition. Forward-looking statements include, but are not limited to, statements with respect to forecasts for growth of the consumer loans receivable, annual revenue growth forecasts, strategic initiatives, new product offerings and new delivery channels, anticipated cost savings, planned capital expenditures, anticipated capital requirements and the Company’s ability to secure sufficient capital, liquidity of the Company, plans and references to future operations and results, critical accounting estimates, expected future yields and net charge off rates on loans, the dealer relationships, the size and characteristics of the Canadian non-prime lending market, the continued development of the type and size of competitors in the market. In certain cases, forward-looking statements that are predictive in nature, depend upon or refer to future events or conditions, and/or can be identified by the use of words such as “expect”, “continue”, “anticipate”, “intend”, “aim”, “plan”, “believe”, “budget”, “estimate”, “forecast”, “foresee”, “target” or negative versions thereof and similar expressions, and/or state that certain actions, events or results “may”, “could”, “would”, “might” or “will” be taken, occur or be achieved.
Forward-looking statements are based on certain factors and assumptions, including expected growth, results of operations and business prospects and are inherently subject to, among other things, risks, uncertainties and assumptions about the Company’s operations, economic factors and the industry generally. There can be no assurance that forward-looking statements will prove to be accurate as actual results and future events could differ materially from those expressed or implied by forward-looking statements made by the Company. Some important factors that could cause actual results to differ materially from those expressed in the forward-looking statements include, but are not limited to, goeasy’s ability to enter into new lease and/or financing agreements, collect on existing lease and/or financing agreements, open new locations on favourable terms, offer products which appeal to customers at a competitive rate, respond to changes in legislation, react to uncertainties related to regulatory action, raise capital under favourable terms, compete, manage the impact of litigation (including shareholder litigation), control costs at all levels of the organization and maintain and enhance the system of internal controls.
The Company cautions that the foregoing list is not exhaustive. These and other factors could cause actual results to differ materially from our expectations expressed in the forward-looking statements, and further details and descriptions of these and other factors are disclosed in the Company’s Management’s Discussion and Analysis (“MD&A”) for the year ended December 31, 2025, and for the quarter ended June 30, 2026 including under the section entitled “Risk Factors”.
The reader is cautioned to consider these, and other factors carefully and not to place undue reliance on forward-looking statements, which may not be appropriate for other purposes. The Company is under no obligation (and expressly disclaims any such obligation) to update or alter the forward-looking statements whether as a result of new information, future events or otherwise, unless required by law.
The Company particularly cautions that the Q3 2026 outlook and full year 2026 commentary presented above under the heading “Updated 2026 Outlook” (the “2026 Outlook Information”) constitutes forward-looking information and that in formulating its outlook, the Company makes a series of assumptions, which include, but are not limited to, assumptions about Environmental Conditions (Stability in the macroeconomic environment; Continued demand for non-prime credit across); Portfolio Growth (Loan originations adjust as underwriting criteria are tightened, particularly within indirect channels); Liquidity & Funding (The Company prioritizes liquidity and covenant compliance; Continued access to funding at acceptable rates; Continued strong free cash flow from its existing portfolio); Revenue Yield (Portfolio yield expected to be negatively impacted by bad debts on interest receivable; Business mix shift to include more unsecured personal loan originations at higher yields; Total portfolio yield and net charge off as a percentage of gross consumer loans receivable on its lending products are as estimated in the Company’s budget and strategic plan); Credit Performance (Net charge offs as a percentage of gross consumer loans receivable perform in line with the Company’ budget and forecasts generated through the use of its proprietary credit and underwriting models; The mixture of customers acquired through each of the Company’s acquisition channels and the mixture of new and existing borrowers are as estimated in the Company’s forecast); Investment Performance (No material changes are assumed in the fair value of investments, and no forecast is made regarding the timing of realization of the investment portfolio); and Mergers and Acquisitions (No mergers or acquisitions are contemplated within the outlook period). These assumptions and expectations are subject to a number of risks, including the following, as well as those set out the section entitled “Risk Factors” in the Company’s MD&A: Environmental & Market Conditions (Uncertainty in consumer demand or broader economic conditions may adversely impact loan originations and portfolio performance; Deterioration in employment levels or economic stability could negatively affect credit performance and increase net charge off rates; Competitive dynamics or pricing pressures may impact margins and growth); Access to Capital & Funding (The Company’s ability to access capital on acceptable terms and maintain adequate liquidity to support operations and strategic priorities); Regulatory Environment (Changes to laws and regulations governing consumer lending that could impact product offerings, pricing or operations); Credit Performance (A material increase in net charge off as a percentage of gross consumer loans receivable beyond expectations, including adverse performance from prior vintages or new originations); and Operating Execution (The Company’s ability to successfully execute on its Action Plan, including underwriting changes, and operating model alignment and platform consolidation; Risks associated with transitioning originations and customer portfolios toward the easyfinancial platform). The 2026 Outlook Information constitutes targets established by the Company and is subject to change as plans and business conditions vary. Accordingly, investors are cautioned not to place undue reliance on the 2026 Outlook Information. Actual results may differ materially.
About goeasy
goeasy Ltd. is a leading Canadian provider of non-prime consumer lending solutions, offering a suite of financial products through its easyfinancial, easyhome, and LendCare brands. goeasy offers unsecured and secured instalment loans, point-of-sale financing, and lease-to-own merchandise through its omni-channel model, which spans online, mobile, and hundreds of locations nationwide.
Driven by its team members’ dedication to expand access to credit for underserved communities and helping customers strengthen their financial futures, goeasy has proudly served more than 1.6 million customers while building an award-winning culture. Shares of goeasy Ltd. are listed on the Toronto Stock Exchange (TSX) under the symbol GSY. For more information, visit www.goeasy.com.
For investor inquiries, contact:
James Obright
Senior Vice President, Investor Relations & Capital Markets
investor_relations@goeasy.com
For media inquiries, contact:
mediainquiries@goeasy.com
Notes:
1 These are non-IFRS ratios. Refer to “Non-IFRS Measures and Other Financial Measures” section in this press release.
2 These are non-IFRS measures. Refer to “Non-IFRS Measures and Other Financial Measures” section in this press release.
3 These are capital management measures. Refer to “Non-IFRS Measures and Other Financial Measures” section in this press release.
4 These are supplementary financial measures. Refer to “Non-IFRS Measures and Other Financial Measures” section in this press release.
INTERIM CONDENSED CONSOLIDATED STATEMENTS OF FINANCIAL POSITION
(Unaudited)
(Expressed in thousands of Canadian dollars)
As At
As At
June 30,
December 31,
2026
2025
ASSETS
Cash
312,100
152,661
Accounts receivable
37,544
42,361
Prepaid expenses
9,601
9,159
Income taxes recoverable
139,504
90,559
Consumer loans receivable, net
4,647,742
5,155,360
Investments
23,117
29,103
Lease assets, net
30,523
36,656
Derivative financial assets
52,429
11,146
Deferred income tax assets
28,269
22,250
Property and equipment, net
26,201
30,788
Right-of-use assets, net
52,431
52,510
Intangible assets, net
102,371
104,142
Goodwill
21,310
21,310
TOTAL ASSETS
5,483,142
5,758,005
LIABILITIES AND SHAREHOLDERS’ EQUITY
Liabilities
Revolving credit facility
(3,031)
175,052
Accounts payable and other liabilities
126,121
107,842
Dividends payable
–
23,398
Unearned revenue
30,317
31,219
Accrued interest payable
68,811
68,533
Deferred income tax liabilities
3,887
5,367
Lease liabilities
58,972
59,451
Secured borrowings
54,608
88,783
Revolving securitization warehouse facilities
610,907
611,015
Derivative financial liabilities
9,683
46,107
Notes payable
3,726,742
3,690,818
TOTAL LIABILITIES
4,687,017
4,907,585
Shareholders’ equity
Share capital
431,206
430,325
Contributed surplus
27,708
26,782
Accumulated other comprehensive loss
(32,346)
(13,367)
Retained earnings
369,557
406,680
TOTAL SHAREHOLDERS’ EQUITY
796,125
850,420
TOTAL LIABILITIES AND SHAREHOLDERS’ EQUITY
5,483,142
5,758,005
INTERIM CONDENSED CONSOLIDATED STATEMENTS OF INCOME (LOSS)
(Unaudited)
(Expressed in thousands of Canadian dollars, except earnings (loss) per share)
Three Months Ended
Six Months Ended
June 30,
June 30,
June 30,
June 30,
2026
2025
2026
2025
Restated
Restated
REVENUE
Interest income
305,493
328,523
623,403
637,414
Lease revenue
19,198
21,822
39,243
44,064
Commissions earned
61,391
73,621
131,454
141,808
Charges and fees
3,954
7,383
8,793
12,986
390,036
431,349
802,893
836,272
OPERATING EXPENSES
BAD DEBTS
179,658
142,742
446,858
287,764
OTHER OPERATING EXPENSES
Salaries and benefits
49,646
52,112
102,310
101,575
Share-based compensation
3,075
5,706
2,013
10,147
Technology costs
10,970
12,583
22,340
24,803
Underwriting and collections
7,592
8,671
16,977
15,833
Occupancy
5,424
5,330
11,138
11,002
Advertising and promotion
2,096
8,338
5,359
17,024
Restructuring charges
–
–
4,763
–
Other expenses
12,167
7,567
22,857
15,249
90,970
100,307
187,757
195,633
DEPRECIATION AND AMORTIZATION
Depreciation of lease assets
6,270
6,947
12,755
13,930
Amortization of intangible assets
5,599
5,655
11,124
11,301
Depreciation of right-of-use assets
5,351
5,292
10,693
10,589
Depreciation of property and equipment
2,575
2,665
5,217
5,262
19,795
20,559
39,789
41,082
TOTAL OPERATING EXPENSES
290,423
263,608
674,404
524,479
OPERATING INCOME
99,613
167,741
128,489
311,793
OTHER LOSS
–
–
(5,986)
–
FINANCE COSTS
(78,426)
(43,033)
(171,589)
(132,684)
INCOME BEFORE INCOME TAXES
21,187
124,708
(49,086)
179,109
INCOME TAX EXPENSE (RECOVERY)
Current
6,326
33,884
(12,582)
64,779
Deferred
(1,005)
(628)
619
(15,831)
5,321
33,256
(11,963)
48,948
NET INCOME (LOSS)
15,866
91,452
(37,123)
130,161
BASIC EARNINGS PER SHARE
0.96
5.55
(2.26)
7.83
DILUTED EARNINGS PER SHARE
0.96
5.49
(2.26)
7.73
SUMMARY OF FINANCIAL RESULTS BY REPORTABLE SEGMENT
(Expressed in thousands of Canadian dollars, except earnings per share)
Three Months Ended June 30, 2026
easyfinancial
easyhome
Corporate
Total
Revenue
Interest income
291,499
13,994
–
305,493
Lease revenue
–
19,198
–
19,198
Commissions earned
57,340
4,051
–
61,391
Charges and fees
3,183
771
–
3,954
352,022
38,014
–
390,036
Operating expenses
Bad debts
171,884
7,774
–
179,658
Other operating expenses
54,720
12,174
24,076
90,970
Depreciation and amortization
9,972
8,274
1,549
19,795
236,576
28,222
25,625
290,423
Operating income (loss)
115,446
9,792
(25,625)
99,613
Other loss
–
Finance costs
(78,426)
Income before income taxes
21,187
Income tax expense
5,321
Net income
15,866
Diluted earnings per share
0.96
Three Months Ended June 30, 2025
(As restated)
easyfinancial
easyhome
Corporate
Total
Revenue
Interest income
317,396
11,127
–
328,523
Lease revenue
–
21,822
–
21,822
Commissions earned
69,812
3,809
–
73,621
Charges and fees
6,684
699
–
7,383
393,892
37,457
–
431,349
Operating expenses
Bad debts
137,429
5,313
–
142,742
Other operating expenses
64,178
13,253
22,876
100,307
Depreciation and amortization
9,952
8,966
1,641
20,559
211,559
27,532
24,517
263,608
Operating income (loss)
182,333
9,925
(24,517)
167,741
Other income
–
Finance costs
(43,033)
Income before income taxes
124,708
Income tax expense
33,256
Net income
91,452
Diluted earnings per share
5.49
Six Months Ended June 30, 2026
easyfinancial
easyhome
Corporate
Total
Revenue
Interest income
595,081
28,322
–
623,403
Lease revenue
–
39,243
–
39,243
Commissions earned
123,346
8,108
–
131,454
Charges and fees
7,250
1,543
–
8,793
725,677
77,216
–
802,893
Operating expenses
Bad debts
428,683
18,175
–
446,858
Other operating expenses
118,628
24,878
44,251
187,757
Depreciation and amortization
19,888
16,762
3,139
39,789
567,199
59,815
47,390
674,404
Operating income (loss)
158,478
17,401
(47,390)
128,489
Other loss
(5,986)
Finance costs
(171,589)
Loss before income taxes
(49,086)
Income taxes (recovery)
(11,963)
Net loss
(37,123)
Diluted loss per share
(2.26)
Six Months Ended June 30, 2025
(As restated)
easyfinancial
easyhome
Corporate
Total
Revenue
Interest income
615,804
21,610
–
637,414
Lease revenue
–
44,064
–
44,064
Commissions earned
134,437
7,371
–
141,808
Charges and fees
11,532
1,454
–
12,986
761,773
74,499
–
836,272
Operating expenses
Bad debts
277,895
9,869
–
287,764
Other operating expenses
125,705
27,177
42,751
195,633
Depreciation and amortization
19,688
18,030
3,364
41,082
423,288
55,076
46,115
524,479
Operating income (loss)
338,484
19,423
(46,115)
311,793
Other income
–
Finance costs
(132,684)
Income before income taxes
179,109
Income taxes
48,948
Net income
130,161
Diluted earnings per share
7.73
SUMMARY OF FINANCIAL RESULTS AND KEY PERFORMANCE INDICATORS
Three Months Ended
($ in 000’s except earnings per share and percentages)
June 30,
2026
June 30,
2025
(As restated)
Variance
$ / bps
Variance
% Change
Summary Financial Results
Revenue
390,036
431,349
(41,313)
(9.6 %)
Bad debts
179,658
142,742
36,916
25.9 %
Other operating expenses
90,970
100,307
9,337
(9.3 %)
EBITDA1
113,138
181,354
(68,216)
(37.6 %)
EBITDA margin1
29.0 %
42.0 %
(1,300 bps)
(31.0 %)
Depreciation and amortization
19,795
20,559
(764)
(3.7 %)
Operating income
99,613
167,741
(68,128)
(40.6 %)
Operating margin
25.5 %
38.9 %
(1,340 bps)
(34.4 %)
Finance costs
78,426
43,033
35,393
82.2 %
Effective income tax rate
25.1 %
26.7 %
(160 bps)
(5.8 %)
Net income
15,866
91,452
(75,586)
(82.7 %)
Diluted earnings per share
0.96
5.49
(4.53)
(82.5 %)
Return on receivables
1.2 %
7.3 %
(610 bps)
(83.6 %)
Return on assets
1.1 %
6.7 %
(560 bps)
(83.6 %)
Return on equity
7.9 %
31.4 %
(2,350 bps)
(74.8 %)
Return on tangible common equity1
10.0 %
40.5 %
(3,050 bps)
(75.3 %)
Adjusted Financial Results1
Other operating expenses
97,240
107,162
(9,922)
(9.3 %)
Efficiency ratio
25.5 %
25.6 %
(10 bps)
(0.4 %)
Operating income
102,888
171,108
(68,220)
(39.9 %)
Operating margin
26.4 %
39.7 %
(1,330 bps)
(33.5 %)
Net income
16,768
73,366
(56,598)
(77.1 %)
Diluted earnings per share
1.02
4.40
(3.38)
(76.8 %)
Return on receivables
1.3 %
5.9 %
(460 bps)
(78.0 %)
Return on assets
1.2 %
5.3 %
(410 bps)
(77.4 %)
Return on equity
8.4 %
25.2 %
(1,680 bps)
(66.7 %)
Return on tangible common equity
9.2 %
31.7 %
(2,250 bps)
(71.0 %)
Key Performance Indicators
Segment Financials
easyfinancial revenue
352,022
393,892
(41,870)
(10.6 %)
easyfinancial operating margin
32.8 %
46.3 %
(1,350 bps)
(29.2 %)
easyhome revenue
38,014
37,457
557
1.5 %
easyhome operating margin
25.8 %
26.5 %
(70 bps)
(2.6 %)
Portfolio Indicators
Gross consumer loans receivable
5,000,735
5,107,648
(106,913)
(2.1 %)
Growth in consumer loans receivable
(362,721)
312,261
(674,982)
(216.2 %)
Gross loan originations
272,060
903,718
(631,658)
(69.9 %)
Total yield on consumer loans (including ancillary products)1
28.3 %
31.7 %
(340 bps)
(10.8 %)
Net charge offs as a percentage of average gross consumer loans receivable1
16.7 %
8.7 %
800 bps
91.6 %
Cash provided by operations before net principal written1
585,360
489,103
96,257
19.7 %
Potential monthly leasing revenue1
5,511
6,478
(967)
(14.9 %)
Six Months Ended
($ in 000’s except earnings per share and percentages)
June 30,
2026
June 30,
2025
(As restated)
Variance
$ / bps
Variance
% Change
Summary Financial Results
Revenue
802,893
836,272
(33,379)
(4.0 %)
Bad debts
446,858
287,764
159,094
55.3 %
Other operating expenses
187,757
195,632
(7,875)
(4.0 %)
EBITDA1
149,537
338,945
(189,408)
(55.9 %)
EBITDA margin1
18.6 %
40.5 %
(2,190 bps)
(54.1 %)
Depreciation and amortization
39,789
41,082
(1,293)
(3.1 %)
Operating income
128,489
311,793
(183,304)
(58.8 %)
Operating margin
16.0 %
37.3 %
(2,130 bps)
(57.1 %)
Other income (loss)
(5,986)
–
(5,986)
(100.0 %)
Finance costs
171,589
132,684
38,905
29.3 %
Effective income tax rate
24.4 %
27.3 %
(290 bps)
(10.8 %)
Net income (loss)
(37,123)
130,161
(167,284)
(128.5 %)
Diluted earnings (loss) per share
(2.26)
7.73
(9.99)
(129.2 %)
Return on receivables
(1.4 %)
5.4 %
(680 bps)
(125.9 %)
Return on assets
(1.3 %)
4.8 %
(610 bps)
(127.1 %)
Return on equity
(9.1 %)
22.2 %
(3,130 bps)
(141.0 %)
Return on tangible common equity1
(8.7 %)
29.0 %
(3,770 bps)
(130.0 %)
Adjusted Financial Results1
Other operating expenses
195,749
209,377
(13,628)
(6.5 %)
Efficiency ratio
25.0 %
25.9 %
(90 bps)
(3.5 %)
Operating income
139,802
318,527
(178,725)
(56.1 %)
Operating margin
17.4 %
38.1 %
(2,070 bps)
(54.3 %)
Net income (loss)
(14,546)
132,715
(147,261)
(111.0 %)
Diluted earnings (loss) per share
(0.88)
7.88
(8.76)
(111.2 %)
Return on receivables
(0.6 %)
5.5 %
(610 bps)
(110.9 %)
Return on assets
(0.5 %)
4.9 %
(540 bps)
(110.2 %)
Return on equity
(3.6 %)
22.7 %
(2,630 bps)
(115.9 %)
Return on tangible common equity
(3.9 %)
28.5 %
(3,240 bps)
(113.7 %)
Key Performance Indicators
Segment Financials
easyfinancial revenue
725,677
761,773
(36,095)
(4.7 %)
easyfinancial operating margin
21.8 %
44.4 %
(2,260 bps)
(50.9 %)
easyhome revenue
77,216
74,499
(2,717)
3.6 %
easyhome operating margin
22.5 %
26.1 %
(360 bps)
(13.8 %)
Portfolio Indicators
Gross consumer loans receivable
5,000,735
5,107,648
(106,913)
(2.1 %)
Growth in consumer loans receivable
(512,732)
505,211
(1,017,943)
(201.5 %)
Gross loan originations
823,374
1,580,488
(757,114)
(47.9 %)
Total yield on consumer loans (including ancillary products)1
28.1 %
31.5 %
(340 bps)
(10.7 %)
Net charge offs as a percentage of average gross consumer loans receivable1
17.3 %
8.8 %
850 bps
96.0 %
Cash provided by operations before net principal written1
1,145,468
899,850
245,618
27.3 %
Potential monthly leasing revenue1
5,511
6,478
(967)
(14.9 %)
1 EBITDA, adjusted other operating expenses, adjusted operating income, adjusted net income and cash provided by operations before net principal written are non-IFRS measures. EBITDA margin, efficiency ratio, adjusted operating margin, adjusted diluted earnings per share, adjusted return on equity, adjusted return on receivable, adjusted return on assets, reported and adjusted return on tangible common equity, net charge offs as a percentage of average gross consumer loans receivable and total yield on consumer loans (including ancillary products) are non-IFRS ratios. Refer to “Non-IFRS Measures and Other Financial Measures” section in this press release.
Non-IFRS Measures and Other Financial Measures
The Company uses a number of financial measures to assess its performance. Some of these measures are not calculated in accordance with International Financial Reporting Standards (IFRS) as issued by International Accounting Standards Board (IASB), are not identified by IFRS and do not have standardized meanings that would ensure consistency and comparability among companies using these measures. The Company believes that non-IFRS measures are useful in assessing ongoing business performance and provide readers with a better understanding of how management assesses performance. These non-IFRS measures are used throughout this press release and listed below. An explanation of the composition of non-IFRS measures and other financial measures can be found in the Company’s MD&A, available on www.sedarplus.ca.
Adjusted Net Income (Loss) and Adjusted Diluted Earnings (Loss) Per Share
Adjusted net income (loss) is a non-IFRS measure and adjusted diluted earnings (loss) per share is a non-IFRS ratio. Refer to “Key Performance Indicators and Non-IFRS Measures” section on page 44 of the Company’s MD&A for the three and six-month periods ended June 30, 2026. Items used to calculate adjusted net income (loss) and adjusted diluted earnings (loss) per share for the three and six-month periods ended June 30, 2026 and 2025 include those indicated in the chart below:
Three Months Ended
Six Months Ended
($ in 000’s except earnings per share)
June 30,
2026
June 30, 2025
(As restated)
June 30,
2026
June 30, 2025
(As restated)
Net income (loss)
15,866
91,452
(37,123)
130,161
Impact of adjusting items
Other operating expenses
Restructuring charges1
–
–
4,763
–
Integration costs2
–
92
–
184
Depreciation and amortization
Amortization of acquired intangible assets3
3,275
3,275
6,550
6,550
Other loss (income)4
–
–
5,986
–
Finance costs
Fair value change on prepayment options related to Notes Payable5
(2,048)
(27,974)
11,260
(3,260)
Total pre-tax impact of adjusting items
1,227
(24,607)
28,559
3,474
Income tax impact of above adjusting items
(325)
6,521
(5,982)
(920)
After-tax impact of adjusting items
902
(18,086)
22,577
2,554
Adjusted net income (loss)
16,768
73,366
(14,546)
132,715
Weighted average number of diluted shares outstanding
16,504
16,673
16,462
16,840
Diluted earnings (loss) per share
0.96
5.49
(2.26)
7.73
Per share impact of adjusting items
0.06
(1.09)
1.38
0.15
Adjusted diluted earnings (loss) per share
1.02
4.40
(0.88)
7.88
Adjusting item related to restructuring charges
1 The Company completed a restructuring exercise in March 2026 and incurred a total of $4.8 million related to severance costs, settlement claims and consulting fees.
Adjusting items related to the LendCare acquisition
2 Integration costs related to representation and warranty insurance costs, and other integration costs related to the acquisition of LendCare.
3 Amortization of the $131 million intangible asset related to the acquisition of LendCare, with an estimated useful life of ten years.
Adjusting item related to other loss
4 For the six-month period ended June 30, 2026, net investment loss was due to fair value changes in the Company’s investments.
Adjusting item related to prepayment options embedded in the Notes Payable
5 For the three and six-month periods ended June 30, 2025 and 2026, the Company recognized a fair value change on the prepayment options related to Notes Payable.
Adjusted Other Operating Expenses and Efficiency Ratio
Adjusted other operating expenses is a non-IFRS measure and efficiency ratio is a non-IFRS ratio. Refer to “Key Performance Indicators and Non-IFRS Measures” section on page 44 of the Company’s MD&A for the three and six-month periods ended June 30, 2026. Items used to calculate adjusted other operating expenses and efficiency ratio for the three and six-month periods ended June 30, 2026 and 2025 include those indicated in the chart below:
Three Months Ended
Six Months Ended
($ in 000’s except percentages)
June 30,
2026
June 30,
2025
(As restated)
June 30,
2026
June 30,
2025
(As restated)
Other operating expenses as stated
90,970
100,307
187,757
195,632
Impact of adjusting items1
Other operating expenses
Restructuring charges
–
–
(4,763)
–
Integration costs
–
(92)
–
(184)
Depreciation and amortization
Depreciation of lease assets
6,270
6,947
12,755
13,930
Total impact of adjusting items
6,270
6,855
7,992
13,746
Adjusted other operating expenses
97,240
107,162
195,749
209,378
Total revenue
390,036
431,349
802,893
836,272
Less: Bad debts on interest receivable
(8,540)
(13,227)
(19,419)
(26,966)
381,496
418,122
783,474
809,307
Efficiency ratio
25.5 %
25.6 %
25.0 %
25.9 %
1 For explanation of adjusting items, refer to the corresponding “Adjusted Net Income and Adjusted Diluted Earnings Per Share” section.
Adjusted Operating Margin
Adjusted operating margin is a non-IFRS measure and adjusted operating margin is a non-IFRS ratio. Refer to “Key Performance Indicators and Non-IFRS Measures” section on page 44 of the Company’s MD&A for the three and six-month periods ended June 30, 2026. Items used to calculate adjusted operating income (loss) and adjusted operating margins for the three and six-month periods ended June 30, 2026 and 2025 include those indicated in the chart below:
Three Months Ended
($ in 000’s except percentages)
June 30,
2026
June 30,
2026 (adjusted)
June 30,
2025
(As restated)
June 30,
2025
(adjusted)
(As restated)
easyfinancial
Operating income (loss)
115,446
115,446
182,332
182,332
Divided by revenue
352,022
352,022
393,892
393,892
easyfinancial operating margin
32.8 %
32.8 %
46.3 %
46.3 %
easyhome
Operating income
9,792
9,792
9,925
9,925
Divided by revenue
38,014
38,014
37,457
37,457
easyhome operating margin
25.8 %
25.8 %
26.5 %
26.5 %
Total
Operating income (loss)
99,613
99,613
167,741
167,741
Other operating expenses1
Restructuring charges
–
–
–
–
Integration costs
–
–
–
92
Depreciation and amortization1
Amortization of acquired intangible assets
–
3,275
–
3,275
Adjusted operating income (loss)
99,613
102,888
167,741
171,108
Divided by revenue
390,036
390,036
431,349
431,349
Total operating margin
25.5 %
25.5 %
38.9 %
39.7 %
1 For explanation of adjusting items, refer to the corresponding “Adjusted Net Income and Adjusted Diluted Earnings Per Share” section.
Six Months Ended
($ in 000’s except percentages)
June 30,
2026
June 30,
2026 (adjusted)
June 30,
2025
(As restated)
June 30,
2025
(adjusted)
(As restated)
easyfinancial
Operating income (loss)
158,481
158,481
338,484
338,484
Divided by revenue
725,677
725,677
761,773
761,773
easyfinancial operating margin
21.8 %
21.8 %
44.4 %
44.4 %
easyhome
Operating income
17,401
17,401
19,423
19,423
Divided by revenue
77,216
77,216
74,499
74,499
easyhome operating margin
22.5 %
22.5 %
26.1 %
26.1 %
Total
Operating income (loss)
128,489
128,489
311,793
311,793
Other operating expenses1
Restructuring charges
–
4,763
–
–
Integration costs
–
–
–
184
Depreciation and amortization1
Amortization of acquired intangible assets
–
6,550
–
6,550
Adjusted operating income (loss)
128,489
139,802
311,793
318,527
Divided by revenue
802,893
802,893
836,272
836,272
Total operating margin
16.0 %
17.4 %
37.3 %
38.1 %
1 For explanation of adjusting items, refer to the corresponding “Adjusted Net Income and Adjusted Diluted Earnings Per Share” section.
Earnings before Interest, Taxes, Depreciation and Amortization (“EBITDA”) and EBITDA Margin
EBITDA is a non-IFRS measure, while EBITDA margin is a non-IFRS ratio. Refer to “Key Performance Indicators and Non-IFRS Measures” section on page 44 of the Company’s MD&A for the three and six-month periods ended June 30, 2026. Items used to calculate EBITDA and EBITDA margin for the three and six-month periods ended June 30, 2026 and 2025 include those indicated in the chart below:
Three Months Ended
Six Months Ended
($ in 000’s except percentages)
June 30,
2026
June 30,
2025
(As restated)
June 30,
2026
June 30,
2025
(As restated)
Net income (loss)
15,866
91,452
(37,123)
130,161
Finance cost
78,426
43,033
171,589
132,684
Income tax expense
5,321
33,257
(11,963)
48,948
Depreciation and amortization
19,795
20,559
39,789
41,082
Depreciation of lease assets
(6,270)
(6,947)
(12,755)
(13,930)
EBITDA
113,138
181,354
149,537
338,945
Divided by revenue
390,036
431,349
802,893
836,272
EBITDA margin
29.0 %
42.0 %
18.6 %
40.5 %
Cash Provided by Operating Activities before Net Principal Written
Cash provided by operating activities before net principal written is a non-IFRS measure. Refer to “Key Performance Indicators and Non-IFRS Measures” section on page 44 of the Company’s MD&A for the three and six-month periods ended June 30, 2026. Items used to calculate cash provided by operating activities before net principal written for the three and six-month periods ended June 30, 2026 and 2025 include those indicated in the chart below:
Three Months Ended
Six Months Ended
($ in 000’s)
June 30,
2026
June 30,
2025
(As restated)
June 30,
2026
June 30,
2025
(As restated)
Cash provided by (used in) operating activities
377,905
(274,170)
500,201
(454,482)
Net principal written
207,455
763,273
645,267
1,354,332
Cash provided by operating activities before net principal written
585,360
489,103
1,145,468
899,850
Adjusted Return on Receivables
Adjusted return on receivables is a non-IFRS ratio. Refer to “Key Performance Indicators and Non-IFRS Measures” section on page 44 of the Company’s MD&A for the three and six-month periods ended June 30, 2026. Items used to calculate adjusted return on receivables for the three and six-month periods ended June 30, 2026 and 2025 include those indicated in the chart below:
Three Months Ended
($ in 000’s except percentages)
June 30,
2026
June 30,
2026
(adjusted)
June 30,
2025
(As restated)
June 30,
2025
(adjusted)
(As restated)
Net income (loss)
15,866
15,866
91,452
91,452
After-tax impact of adjusting items1
–
902
–
(18,086)
Adjusted net income (loss)
15,866
16,768
91,452
73,366
Multiplied by number of periods in a year
X 4
X 4
X 4
X 4
Divided by average gross consumer loans receivable
5,101,112
5,101,112
4,980,397
4,980,397
Return on receivables
1.2 %
1.3 %
7.3 %
5.9 %
1 For explanation of adjusting items, refer to the corresponding “Adjusted Net Income and Adjusted Diluted Earnings Per Share” section.
Six Months Ended
($ in 000’s except percentages)
June 30,
2026
June 30,
2026
(adjusted)
June 30,
2025
(As restated)
June 30,
2025
(adjusted)
(As restated)
Net income (loss)
(37,123)
(37,123)
130,161
130,161
After-tax impact of adjusting items1
–
22,577
–
2,554
Adjusted net income (loss)
(37,123)
(14,546)
130,161
132,715
Multiplied by number of periods in a year
X 4/2
X 4/2
X 4/2
X 4/2
Divided by average gross consumer loans receivable
5,277,695
5,277,695
4,846,548
4,846,548
Return on receivables
(1.4 %)
(0.6 %)
5.4 %
5.5 %
1 For explanation of adjusting items, refer to the corresponding “Adjusted Net Income and Adjusted Diluted Earnings Per Share” section.
Adjusted Return on Assets
Adjusted return on assets is a non-IFRS ratio. Refer to “Key Performance Indicators and Non-IFRS Measures” section on page 44 of the Company’s MD&A for the three and six-month periods ended June 30, 2026. Items used to calculate adjusted return on assets for the three and six-month periods ended June 30, 2026 and 2025 include those indicated in the chart below:
Three Months Ended
($ in 000’s except percentages)
June 30,
2026
June 30,
2026
(adjusted)
June 30,
2025
(As restated)
June 30,
2025
(adjusted)
(As restated)
Net income (loss)
15,866
15,866
91,452
91,452
After-tax impact of adjusting items1
–
902
–
(18,086)
Adjusted net income (loss)
15,866
16,768
91,452
73,366
Multiplied by number of periods in a year
X 4
X 4
X 4
X 4
Divided by average total assets for the period
5,652,415
5,652,415
5,487,102
5,487,102
Return on assets
1.1 %
1.2 %
6.7 %
5.3 %
1 For explanation of adjusting items, refer to the corresponding “Adjusted Net Income and Adjusted Diluted Earnings Per Share” section.
Six Months Ended
($ in 000’s except percentages)
June 30,
2026
June 30,
2026
(adjusted)
June 30,
2025
(As restated)
June 30,
2025
(adjusted)
(As restated)
Net income (loss)
(37,123)
(37,123)
130,161
130,161
After-tax impact of adjusting items1
–
22,577
–
2,554
Adjusted net income (loss)
(37,123)
(14,546)
130,161
132,715
Multiplied by number of periods in a year
X 4/2
X 4/2
X 4/2
X 4/2
Divided by average total assets for the period
5,687,611
5,687,611
5,395,080
5,395,080
Return on assets
(1.3 %)
(0.5 %)
4.8 %
4.9 %
1 For explanation of adjusting items, refer to the corresponding “Adjusted Net Income and Adjusted Diluted Earnings Per Share” section.
Adjusted Return on Equity
Adjusted return on equity is a non-IFRS ratio. Refer to “Key Performance Indicators and Non-IFRS Measures” section on page 44 of the Company’s MD&A for the three and six-month periods ended June 30, 2026. Items used to calculate adjusted return on equity for the three and six-month periods ended June 30, 2026 and 2025 include those indicated in the chart below:
Three Months Ended
($ in 000’s except percentages)
June 30,
2026
June 30,
2026
(adjusted)
June 30,
2025
(As restated)
June 30,
2025
(adjusted)
(As restated)
Net income (loss)
15,866
15,866
91,452
91,452
After-tax impact of adjusting items1
–
902
–
(18,086)
Adjusted net income (loss)
15,866
16,768
91,452
73,366
Multiplied by number of periods in a year
X 4
X 4
X 4
X 4
Divided by average shareholders’ equity for the period
798,682
798,682
1,165,244
1,165,244
Return on equity
7.9 %
8.4 %
31.4 %
25.2 %
1 For explanation of adjusting items, refer to the corresponding “Adjusted Net Income and Adjusted Diluted Earnings Per Share” section.
Six Months Ended
($ in 000’s except percentages)
June 30,
2026
June 30,
2026
(adjusted)
June 30,
2025
(As restated)
June 30,
2025
(adjusted)
(As restated)
Net income (loss)
(37,123)
(37,123)
130,161
130,161
After-tax impact of adjusting items1
–
22,577
–
2,554
Adjusted net income (loss)
(37,123)
(14,546)
130,161
132,715
Multiplied by number of periods in a year
X 4/2
X 4/2
X 4/2
X 4/2
Divided by average shareholders’ equity for the period
815,928
815,928
1,170,889
1,170,889
Return on equity
(9.1 %)
(3.6 %)
22.2 %
22.7 %
1 For explanation of adjusting items, refer to the corresponding “Adjusted Net Income and Adjusted Diluted Earnings Per Share” section.
Reported and Adjusted Return on Tangible Common Equity
Reported and adjusted return on tangible common equity are non-IFRS ratios. Refer to “Key Performance Indicators and Non-IFRS Measures” section on page 44 of the Company’s MD&A for the three and six-month periods ended June 30, 2026. Items used to calculate reported and adjusted return on tangible common equity for the three and six-month periods ended June 30, 2026 and 2025 include those indicated in the chart below:
Three Months Ended
($ in 000’s except percentages)
June 30,
2026
June 30,
2026
(adjusted)
June 30,
2025
(As restated)
June 30,
2025
(adjusted)
(As restated)
Net income
15,866
15,866
91,452
91,452
Amortization of acquired intangible assets
3,275
3,275
3,275
3,275
Income tax impact of the above item
(868)
(868)
(868)
(868)
Net income before amortization of acquired intangible assets, net of income tax
18,273
18,273
93,859
93,859
Impact of adjusting items1
Other operating expenses
Restructuring charges
–
–
–
–
Integration costs
–
–
–
92
Other loss
–
–
–
–
Finance costs
Fair value change on prepayment options related to Notes Payable
–
(2,048)
–
(27,974)
Total pre-tax impact of adjusting items
–
(2,048)
–
(27,882)
Income tax impact of above adjusting items
–
543
–
7,389
After-tax impact of adjusting items
–
(1,505)
–
(20,493)
Adjusted net income (loss)
18,273
16,768
93,859
73,366
Multiplied by number of periods in a year
X 4
X 4
X 4
X 4
Average shareholders’ equity
798,682
798,682
1,165,244
1,165,244
Average goodwill
(21,310)
(21,310)
(180,923)
(180,923)
Average acquired intangible assets2
(64,954)
(64,954)
(78,054)
(78,054)
Average related deferred tax liabilities
17,213
17,213
20,684
20,684
Divided by average tangible common equity
729,631
729,631
926,951
926,951
Return on tangible common equity
10.0 %
9.2 %
40.5 %
31.7 %
1 For explanation of adjusting items, refer to the corresponding “Adjusted Net Income and Adjusted Diluted Earnings Per Share” section.
2 Excludes intangible assets relating to software.
Six Months Ended
($ in 000’s except percentages)
June 30,
2026
June 30,
2026
(adjusted)
June 30,
2025
(As restated)
June 30,
2025
(adjusted)
(As restated)
Net income (loss)
(37,123)
(37,123)
130,161
130,161
Amortization of acquired intangible assets
6,550
6,550
6,550
6,550
Income tax impact of the above item
(1,736)
(1,736)
(1,736)
(1,736)
Net income before amortization of acquired intangible assets, net of income tax
(32,309)
(32,309)
134,975
134,975
Impact of adjusting items1
Other operating expenses
Restructuring charges
–
4,763
–
–
Integration costs
–
–
–
184
Other loss
–
5,986
–
–
Finance costs
Fair value change on prepayment options related to Notes Payable
–
11,260
–
(3,260)
Total pre-tax impact of adjusting items
–
22,009
–
(3,076)
Income tax impact of above adjusting items
–
(4,246)
–
816
After-tax impact of adjusting items
–
17,763
–
(2,260)
Adjusted net income (loss)
(32,309)
(14,546)
134,975
132,715
Multiplied by number of periods in a year
X 4/2
X 4/2
X 4/2
X 4/2
Average shareholders’ equity
815,928
815,928
1,170,889
1,170,889
Average goodwill
(21,310)
(21,310)
(180,923)
(180,923)
Average acquired intangible assets2
(66,592)
(66,592)
(79,692)
(79,692)
Average related deferred tax liabilities
17,647
17,647
21,118
21,118
Divided by average tangible common equity
745,673
745,673
931,392
931,392
Return on tangible common equity
(8.7 %)
(3.9 %)
29.0 %
28.5 %
1 For explanation of adjusting items, refer to the corresponding “Adjusted Net Income and Adjusted Diluted Earnings Per Share” section.
2 Excludes intangible assets relating to software.
Total Yield on Consumer Loans as a Percentage of Average Gross Consumer Loans Receivable
Total yield on consumer loans as a percentage of average gross consumer loans receivable is a non-IFRS ratio. See description in section “Portfolio Analysis” on page 30 of the Company’s MD&A for the three and six-month periods ended June 30, 2026. Items used to calculate total yield on consumer loans as a percentage of average gross consumer loans receivable for three and six-month periods ended June 30, 2026 and 2025 include those indicated in the chart below:
Three Months Ended
Six Months Ended
($ in 000’s except percentages)
June 30,
2026
June 30,
2025
(As restated)
June 30,
2026
June 30,
2025
(As restated)
Total Company revenue
390,036
431,349
802,893
836,272
Less: Leasing revenue
(20,386)
(23,059)
(41,659)
(46,574)
Less: Bad debts on interest income
(8,540)
(13,227)
(19,419)
(26,965)
Adjusted financial revenue
361,110
395,063
741,815
762,733
Multiplied by number of periods in a year
X 4
X 4
X 4/2
X 4/2
Divided by average gross consumer loans receivable
5,101,112
4,980,397
5,277,695
4,846,548
Total yield on consumer loans as a percentage of average gross consumer loans receivable (annualized)
28.3 %
31.7 %
28.1 %
31.5 %
Net Charge Offs as a Percentage of Average Gross Consumer Loans Receivable
Net charge Offs as a percentage of average gross consumer loans receivable is a non-IFRS ratio. See description in section “Portfolio Analysis” on page 30 of the Company’s MD&A for the three and six-month periods ended June 30, 2026. Items used to calculate net charge Offs as a percentage of average gross consumer loans receivable for the three and six-month periods ended June 30, 2026. and 2025 include those indicated in the chart below:
Three Months Ended
($in 000’s except percentages)
June 30,
2026
June 30,
2025
(As restated)
Net charge offs on gross consumer loans receivable
212,741
108,545
Multiplied by number of periods in a year
X 4
X 4
Divided by average gross consumer loans receivable
5,101,112
4,980,397
Net charge offs as a percentage of average gross consumer loans receivable (annualized)
16.7 %
8.7 %
Six Months Ended
($in 000’s except percentages)
June 30,
2026
June 30,
2025
(As restated)
Net charge offs on gross consumer loans receivable
455,322
213,304
Multiplied by number of periods in a year
X4/2
X4/2
Divided by average gross consumer loans receivable
5,277,695
4,846,548
Net charge offs as a percentage of average gross consumer loans receivable (annualized)
17.3 %
8.8 %
Net Principal Written and Percentage Net Principal Written to New Customers
Net principal written (Net loan advances) is a non-IFRS measure. See description in section “Portfolio Analysis” on page 30 of the Company’s MD&A for the three and six-month periods ended June 30, 2026. The percentage of net loan advances to new customers is a non-IFRS ratio. It is calculated as loan originations to new customers divided by the net principal written. The Company uses percentage of net loan advances to new customers, among other measures, to assess the operating performance of its lending business. Items used to calculate the percentage of net loan advances to new customers for the three-month periods ended for the three and six-month periods ended June 30, 2026 include those indicated in the chart below:
Three Months Ended
Six Months Ended
($ in 000’s)
June 30, 2026
June 30, 2025
June 30, 2026
June 30, 2025
Gross loan originations
272,060
903,718
823,374
1,580,487
Loan originations to new customers
128,567
557,894
441,261
989,843
Loan originations to existing customers
143,493
345,824
382,113
590,644
Less: Proceeds applied to repay existing loans
(64,605)
(140,445)
(178,107)
(226,155)
Net advance to existing customers
78,888
205,379
204,006
364,489
Net principal written
207,455
763,273
645,267
1,354,332
Percentage net advances to new customers
62.0 %
73.1 %
68.4 %
73.1 %
Debt to Adjusted Tangible Equity
Debt to adjusted tangible equity is a capital management measure. Refer to “Financial Condition” section on page 55 of the Company’s MD&A for the three and six-month periods ended June 30, 2026.
Weighted Average Interest Rate
Weighted average interest rate is a supplementary financial measure. It is calculated as the sum of individual loan balance multiplied by interest rate divided by gross consumer loans receivable.
SOURCE goeasy Ltd.

You may like
Technology
Western Sydney International Airport Opens After Bechtel-Led Delivery Program Completes Major Construction Works Seven Months Early
Published
15 minutes agoon
November 11, 2026By
Australia’s first major greenfield international airport in more than 50 years delivered ahead of schedule: a role model for future infrastructure delivery in Australia
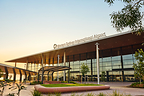
SYDNEY, Nov. 11, 2026 /PRNewswire/ — Western Sydney International (Nancy-Bird Walton) Airport (WSI) opened to passengers on October 25, 2026, following a design, construction, and commissioning program led by Western Sydney Airport Corporation with Bechtel Australia as Delivery Partner that finished months ahead of schedule. The opening marks a new era of aviation, trade, and economic activity for Western Sydney and Australia.
Jetstar operated the airport’s first commercial passenger service, flying from WSI to the Gold Coast. Passenger operations follow the start of freight services in July and cap 15 years of planning, seven years of construction, and a year of testing and operational readiness.
A Delivery Model Built for Complexity
“I offer my warm congratulations to our partner, Western Sydney Airport Corporation, our contractors, and all the colleagues and partners who have come together to make this project such a success,” said Darren Mort President of Infrastructure and Executive Director at Bechtel. “WSI shows what the integrated model can achieve when a customer, delivery partner, and contractors work as one team around a clear vision. Together, we transformed a 1,780-hectare greenfield site into a modern international airport, months ahead of schedule.”
Key project achievements include:
Completing major construction works almost seven months ahead of schedule.More than 21 million work hours, most of them in high-risk construction, completed with strong safety performance and supported by more than 42,000 proactive safety activities.Delivering Australia’s largest earthworks program, moving approximately 28 million cubic metres of material across the site.Reusing nearly 6 million tonnes of sandstone from Sydney tunnelling projects, diverting material from landfill.Installing a 4.5-megawatt solar system that will offset more than 4,000 tonnes of carbon dioxide each year, alongside all-electric heating, rainwater harvesting, and electric-vehicle infrastructure.Integrating more than 60 software platforms supporting airport operations, including passenger processing, security, retail, and office systems.Exceeding sustainability targets on all construction packages, each receiving a 4- or 5-Star rating.
Since 2018, Bechtel has served as Delivery Partner to Western Sydney Airport Corporation, the company responsible for building and operating WSI. Under this model, Bechtel:
Worked as an integrated partner of the customer’s team.Helped set the program’s scope, cost, and schedule baseline.Procured and managed contractors across the earthworks, terminal, runway, landside, and technology packages, and managed the interfaces between them.Controlled the program budget, keeping every package moving toward the same completion date that resulted in finishing months early and within budget.
Innovation from the Ground Up
The program combined large-scale engineering with new approaches to sustainability and technology. It delivered Australia’s largest earthworks program and reused nearly 6 million tonnes of sandstone from Sydney tunnelling projects that would otherwise have gone to landfill. More than 60 software platforms were integrated into one operating environment covering passenger processing, security, retail, and office systems. A 4.5-megawatt solar system, all-electric heating, and rainwater harvesting are built into the airport. And the new terminal includes extensive innovative elements, from the integrated domestic/international check-in area, a state-of-the art baggage system, and departure/arrival gates able to be used for both domestic and international flights.
The airport is designed to initially serve up to 10 million passengers a year, with capacity to expand as demand grows. It has already helped catalyze AU$19 billion in surrounding infrastructure investment and is projected to contribute AU$23.9 billion to Australia’s gross domestic product by 2060.
Building on Bechtel’s Commitment to Australia
“Today marks years of hard work, collaboration, and commitment from thousands of people, including more than 330 Bechtel colleagues across design, engineering, procurement, and project delivery,” said Richard Freer, Managing Director of Bechtel’s Public Infrastructure Business in Australia. “Excellent project set up, led by the Federal Infrastructure Department, strong front-end planning, disciplined project controls, and new ways of integrating complex systems kept multiple contractors and interconnected packages moving towards the same completion date. That’s how we finished ahead of the schedule set back in 2018. Just as important, more than half of the workforce came from Western Sydney, so this airport was built by the community it now serves.”
Bechtel has been serving Australian communities and customers for more than 70 years with projects spanning airports, rail, mines, mineral processing facilities, LNG installations, refineries, chemical plants, power stations, and telecommunications infrastructure. At peak construction on WSI, the project team brought together around 4,000 people; across the full construction period, more than 11,000 people worked on the project, with more than half drawn from Western Sydney. The program also engaged more than 360 local businesses and exceeded its workforce participation targets for local, diverse, First Nations and learner workers.
WSI is Australia’s new 24-hour global gateway, providing domestic, international, and freight services, supporting Western Sydney’s long-term growth and Australia’s future aviation capacity.
About Bechtel
Bechtel is a trusted engineering, construction, procurement, and project management partner to industry and government. Differentiated by the quality of our people and our relentless drive to deliver the most successful outcomes, we align our capabilities to our customers’ objectives to create a lasting positive impact. Since 1898, we have helped customers complete more than 25,000 projects in 160 countries on all seven continents that have created jobs, grown economies, improved the resiliency of the world’s infrastructure, increased access to energy, resources and vital services, and made the world a safer, cleaner place.
Bechtel serves the Energy; Infrastructure; Manufacturing & Technology; Mining & Metals; and Nuclear, Security & Environmental markets. Our services span from initial planning and investment through start-up and operations.
Media Contact: Molly Edwards, medwards@bechtel.com
View original content to download multimedia:https://www.prnewswire.com/apac/news-releases/western-sydney-international-airport-opens-after-bechtel-led-delivery-program-completes-major-construction-works-seven-months-early-302935697.html
SOURCE Bechtel
Technology
cynapse.ai Wins Agentic AI Innovation Award at AINext Awards 2026
Published
15 minutes agoon
November 11, 2026By

ARLINGTON, Va., Nov. 11, 2026 /PRNewswire/ — cynapse.ai has been named the winner of the Agentic AI Innovation Award in the Excellence in AI & Technology Industry category at the AINext Awards 2026, presented by Next Business Media. The award recognizes organizations and leaders demonstrating innovation, talent, and impact across the AI and technology industries.
For most organizations, video has long been a record of what has already happened. Only around 1% of recorded footage is typically reviewed, so risks, threats, and operational insights stay buried until someone goes looking for them. At the core of cynapse.ai’s award-winning innovation is its Agentic Video Intelligence platform, in which AI goes beyond detecting events to contextual understanding of scenes, applying reasoning, and using AI agents to enable complex actions. Powered by cyNeuron, cynapse.ai’s agentic framework combines Vision AI with domain-specific Vision Language Models (VLMs) and custom AI agents, turning existing camera networks from a passive record into a source of real-time and offline operational intelligence.
The cynapse Copilot lets operators search footage, get insights, and generate summaries and reports, all in natural language. Most significantly, teams are no longer limited to predefined use cases. They can create their own events of interest simply by describing them, such as “alert when a delivery truck causes traffic obstruction at office building A drop-off point during working hours” and the platform starts detecting them right away.
“We’re honored to receive this recognition. In today’s complex world, mission-critical operations must unlock the full potential of their video data, whether to strengthen security, improve safety, boost operational efficiency, ensure compliance, or all of the above,” said Guy Ron, Founder and CEO of cynapse.ai. “Physical AI is bringing intelligence into the real world, and Agentic Video Intelligence is how mission-critical operations put it to work. Our innovation not only brings critical information buried in video footage to the surface but also lets operators interact directly with the system to get the answers they need, when they need them, enabling better-informed decisions and faster responses.”
The impact extends across industries where operation is mission critical. Security teams can respond to threats as they unfold, data center operators can detect threats early across every ring of the facility, transportation agencies can identify incidents and violations in real time, and port operators can strengthen safety and compliance.
cynapse.ai delivers this through industry-specific solutions: cySecurity, cyDataCenter, cyRoad and cyPort. As a software-only platform, it runs on existing cameras, in the cloud or on-premises, with no need to replace existing infrastructure.
About cynapse.ai
cynapse.ai is a leading provider of Verticalized Agentic AI Video Intelligence solutions, enabling organizations to enhance safety, security, compliance and operational efficiency. The cynapse.ai solutions are designed to detect and respond to risks, threats, and violations while uncovering opportunities across transportation networks, seaports and data centers. Offering human-like video understanding through cyNeuron and 150+ field-proven, predefined analytics, and turning it into everyday value through AI agents and an intuitive copilot, cynapse.ai is making video intelligence more powerful and accessible than ever before. www.cynapse.ai
View original content:https://www.prnewswire.com/apac/news-releases/cynapseai-wins-agentic-ai-innovation-award-at-ainext-awards-2026-302934415.html
SOURCE cynapse.ai
Technology
NIDS Co., Ltd. Expands ‘Airvom’ Supply to High-Traffic Facilities, Strengthening Its Air Quality Management Solutions Business
Published
15 minutes agoon
November 11, 2026By

Company leverages in-house precision sensors and plasma modules to target hospitals, schools, and welfare facilities in B2G and B2B markets
SEOUL, South Korea, Nov. 10, 2026 /PRNewswire/ — NIDS Co., Ltd. is expanding its air quality management business for high-traffic public facilities with Airvom, its in-house air purification and sterilization brand. The company plans to broaden its public- and private-sector supply network, targeting hospitals, nursing homes, schools, welfare facilities, and subway stations.
According to NIDS, Airvom is an air care product that combines a precision sensor that detects indoor air conditions with a plasma module. The company explained that the system links purification and sterilization functions to the air quality data measured by the sensor, applying its environmental measurement component technology to air quality management in real spaces.
The core of what NIDS is presenting to the high-traffic facility market is the link between measurement and operation. Built on a structure that identifies air conditions in real time and reflects them in how the product operates, the company aims to address air quality management needs within facilities. The company said it applied plasma technology targeting airborne viruses and harmful bacteria in addition to its purification function.
Airvom uses dielectric barrier discharge (DBD) low-temperature plasma technology. NIDS said the product combines its independently developed plasma radical technology with its sensing technology. The company cites owning both the sensor and the sterilization module as proprietary technology as a key competitive strength in product development and operation.
This structure of directly handling core components also ties into how the company develops finished products. NIDS explained that it can control sensor sensitivity and tune operating algorithms to suit the system. It plans to use this tuning capability when linking the sensor and plasma module, developing products in a direction that improves performance and quality stability.
The product line is organized by usage space, ranging from vehicle and personal models to residential and office units and models for hospitals and high-traffic facilities. Among these, the company identified hospitals, nursing homes, schools, welfare facilities, and subway stations as targets for future supply expansion. NIDS plans to establish Airvom in the market through B2G and B2B business aimed at facilities.
Airvom’s business offering also includes S+Link, an Internet of Things (IoT) platform for real-time air quality management. NIDS presents a solution that connects sensors, finished products, and the platform to monitor and manage air conditions. The company aims to extend its business scope beyond supplying individual devices to the management domain that makes use of air quality data.
The foundation of the Airvom business is NIDS’s experience in environmental sensor manufacturing and plasma module development. Founded in 2000, NIDS has designed and mass-produced particulate matter sensors, optical gas sensors, and composite environmental sensor modules in-house. The company has also been developing and supplying plasma ionizers for odor removal in domestic automotive air conditioners since 2000, a technology that was developed to eliminate bacteria and viruses. By applying its experience developing core air-measurement components to finished air purification and sterilization products, the company is pursuing its own-brand business.
This represents a move to secure customer touchpoints distinct from its sensor component supply. While the component business primarily targets home appliance, automotive, and HVAC companies, Airvom seeks supply opportunities with public institutions and facility operators that run actual spaces. The company plans to operate the sensor supply business and the Airvom business as two pillars and expand its presence in the finished-product market.
NIDS is also exploring the potential for supplying its air quality management solutions overseas. It plans to contact buyers and identify local partnership opportunities through its existing overseas branch network in the United States, Japan, and China. Alongside expanding supply to domestic high-traffic facilities, the company intends to pursue overseas sales channels in parallel.
Going forward, NIDS will promote the product competitiveness of its combined sensor and plasma technologies and continue supply discussions with public and private facilities. Its goal is to extend its in-house component technology into a finished air care product business and secure a market foundation for Airvom.
The company is also preparing to build a business foundation for its entry into the U.S. market through exchanges with Yale University and Johns Hopkins University.
“Airvom will expand its supply network centered on high-traffic facilities such as hospitals, nursing homes, schools, welfare facilities, and subway stations (B2G/B2B),” a NIDS representative said.
View original content:https://www.prnewswire.com/news-releases/nids-co-ltd-expands-airvom-supply-to-high-traffic-facilities-strengthening-its-air-quality-management-solutions-business-302934649.html
SOURCE NIDS Co., Ltd.


Western Sydney International Airport Opens After Bechtel-Led Delivery Program Completes Major Construction Works Seven Months Early
cynapse.ai Wins Agentic AI Innovation Award at AINext Awards 2026
NIDS Co., Ltd. Expands ‘Airvom’ Supply to High-Traffic Facilities, Strengthening Its Air Quality Management Solutions Business

Send Rakhi to UK swiftly with UK Gifts Portal

Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

Nullmax and Renesas Forge Strategic Partnership to Deliver Competitive ADAS Solutions for the Global Market

Why You Should Build on #NEAR – Co-founder Illia Polosukhin at CV Labs
Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

NEAR End of Year Town Hall 2021: The Open Web World, MetaBUILD 2 Hackathon and 2021 recap
Trending
-

 Technology4 days ago
Diamond Foundry Announces First-Ever D200mm Single-Crystal Diamond
-

 Coin Market5 days ago
Crypto exchanges tout cold storage ratios after Binance attack
-

 Technology5 days ago
ASTRI Establishes Advisory Board for Smart Mobility Technology Alliance
-

 Technology5 days ago
2026 World Internet Conference Wuzhen Summit Opens
-

 Coin Market5 days ago
Bitcoin, Ether ETFs post $530M outflows as election gains evaporate
-

 Technology4 days ago
Home Companion Robot Mobo to Debut Globally and Open Pre-orders as AiMOGA Showcases Its Robot Family at the 2026 OMODA & JAECOO International User Summit
-
 Technology4 days ago
Datavault AI Founder Nathaniel Bradley Sues Board
-

 Coin Market4 days ago
Suspicious prediction market activity seen before election poll release: NYT