
Technology
ePlus Reports Third Quarter and First Nine Months Results

Published
2 years agoon
By
Third Quarter Gross Profit Increased 5.3% And Gross Margin Expanded Year Over Year
Third Quarter Fiscal Year 2025
•
Net sales increased 0.4% to $511.0 million; technology business net sales declined 0.2% to $493.1 million; service revenues increased 52.2% to $113.6 million.
•
Technology business gross billings increased 6.6% to $849.5 million.
•
Consolidated gross profit increased 5.3% to $140.9 million.
•
Consolidated gross margin was 27.6%, compared with 26.3% last year.
•
Net earnings decreased 11.5% to $24.1 million.
•
Adjusted EBITDA decreased 15.2% to $39.1 million.
•
Diluted earnings per share decreased 10.8% to $0.91. Non-GAAP diluted earnings per share decreased 10.2% to $1.06.
First Nine Months of Fiscal Year 2025
•
Net sales decreased 6.0% to $1,570.7 million; technology business net sales decreased 6.7% to $1,521.9 million; service revenues increased 38.6% to $295.5 million.
•
Technology business gross billings decreased 0.2% to $2,491.5 million.
•
Consolidated gross profit increased 0.7% to $423.4 million.
•
Consolidated gross margin was 27.0%, compared with 25.2% last year.
•
Net earnings decreased 11.7% to $82.8 million.
•
Adjusted EBITDA decreased 12.5% to $134.4 million.
•
Diluted earnings per share decreased 11.9% to $3.10. Non-GAAP diluted earnings per share decreased 10.8% to $3.56.
HERNDON, Va., Feb. 5, 2025 /PRNewswire/ — ePlus inc. (NASDAQ: PLUS), a leading provider of technology and financing solutions, today announced financial results for the three months and nine months ended December 31, 2024.
Management Comment
“Our third quarter results reflect the benefit of our investment in services and the continuing industry shift toward ratable, subscription and ‘as a service’ revenue recognition,” said Mark Marron, president and CEO of ePlus. “Our services business, driven by organic and inorganic growth, increased 52% in the third quarter, across both managed and professional services. We are also benefitting from acquisitions completed over the past two years which have enhanced our suite of service offerings. This strong services performance in our technology business, however, was offset by lower product sales and a higher proportion of netted down product revenues given the acceleration of the industry shift underway.
“Technology business gross billings increased 6.6% underscoring solid customer demand for our suite of solutions offerings. Consolidated gross profit increased 5.3% and consolidated gross margin expanded 130 basis points, on a lower revenue base as we benefitted from higher proportion of netted down revenues, and increased contribution from higher margin services. We continue to maintain our strong positioning in the fast-growing categories that our customers require and our strong balance sheet positions us well to advance our organic and inorganic growth strategy over time.”
Third Quarter Fiscal Year 2025 Results
For the third quarter ended December 31, 2024, as compared to the third quarter ended December 31, 2023:
Consolidated net sales increased 0.4% to $511.0 million, from $509.1 million.
Technology business net sales declined slightly to $493.1 million, from $494.2 million, as lower product sales were offset by higher service revenues. Technology business gross billings increased 6.6% to $849.5 million, from $797.0 million.
Product sales declined 9.5% to $379.5 million, from $419.5 million and, product margin was 22.1%, up from 21.9% last year, both due to a higher proportion of third-party maintenance, software subscriptions, and services sold in the current quarter, which are recorded on a net basis. Product sales to certain enterprise customers at lower overall margins decreased product margins but was offset by contribution from the netted down revenues.
Professional service revenues increased 73.6% from last year to $69.5 million, from $40.0 million, primarily due to the acquisition of Bailiwick Services, LLC. Gross margins declined to 40.1%, from 43.3% due to a shift in the mix of services provided.
Managed service revenues increased 27.5% to $44.2 million due to ongoing growth in these offerings, including Enhanced Maintenance Support and Cloud services. Gross profit from managed services increased 19.5% from last year due to the increase in revenues. Managed service margins declined to 29.8%, from 31.8%.
Financing business segment net sales increased 19.8% to $17.8 million primarily due to increased proceeds from sales of equipment. Gross profit in the financing business segment increased $2.3 million, from $13.5 million last year to $15.8 million this year, due to the increase in net sales.
Consolidated gross profit increased 5.3% to $140.9 million, from $133.8 million. Technology business gross profit increased 4.0% to $125.0 million due to increased gross profit from the professional and managed services segments offset by a decline in gross profit from the product segment. The financing business segment gross profit increased 16.9% to $15.8 million. Consolidated gross margin was 27.6%, compared with 26.3% last year.
Operating expenses were $112.4 million, up 17.3% from $95.8 million last year, primarily due to increases in salaries and benefits from additional headcount. Our headcount at the end of the third quarter of 2025 was 2,291, up 394 from a year ago, due to the acquisition of Bailiwick Services, LLC on August 19, 2024, and Peak Resources on January 27, 2024. Of the 394 additional employees, 355 were customer facing employees.
Consolidated operating income decreased 25.1% to $28.5 million and earnings before tax decreased 16.3% to $32.2 million. Other income was $3.7 million compared to $0.4 million last year due to higher interest income and foreign currency transaction gains.
Our effective tax rate for the current quarter was 25.0%, lower than the prior year quarter of 29.0%, primarily due to lower state taxes.
Net earnings decreased 11.5% to $24.1 million.
Adjusted EBITDA in the technology business declined 25.1% and increased 23.1% in the financing business segment, and when combined, resulted in a consolidated decrease of 15.2% to $39.1 million.
Diluted earnings per share was $0.91, compared with $1.02 in the prior year quarter. Non-GAAP diluted earnings per share was $1.06, compared with $1.18 in the prior year quarter.
First Nine Months of Fiscal Year 2025 Results
For the nine months ended December 31, 2024, as compared to the nine months ended December 31, 2023:
Consolidated net sales decreased 6.0% to $1,570.7 million, from $1,670.8 million.
Technology business net sales decreased 6.7% to $1,521.9 million, from $1,631.8 million, due to lower product sales, offset by higher service revenues. Technology business gross billings decreased 0.2% to $2,491.5 million, from $2,495.5 million.
Product sales decreased 13.5% to $1,226.4 million, from $1,418.6 million, due to declines in customer demand, as well as a shift in mix. Gross profit from product segment sales decreased 11.7% to $271.9 million, from $308.1 million, due to lower sales combined with a shift in mix towards third-party maintenance and services, which are recorded on a net basis.
Professional service revenues increased 48.1% primarily due to the acquisition of Bailiwick Services, LLC. Gross margins declined slightly to 40.8% from 42.0% for the same period in the prior year.
Managed service revenues increased 27.7% to $126.8 million, from $99.3 million, due to ongoing growth in these offerings, including Enhanced Maintenance Support, Cloud and Service Desk services. Gross profit from managed services increased 23.6% to $38.3 million, from $31.0 million, due to the increase in revenues. Gross margins declined slightly to 30.2% from 31.2% last year.
Financing business segment net sales increased 24.9% to $48.8 million, from $39.1 million, due to higher transactional gains and portfolio earnings offset by lower post-contract earnings. Gross profit in the financing business segment increased $10.7 million primarily due to the increase in sales.
Consolidated gross profit increased to $423.4 million, from $420.4 million. Consolidated gross margin was 27.0%, compared with last year’s gross margin of 25.2%, due to higher product margins.
Operating expenses were $316.7 million, up 8.7% from $291.2 million last year, primarily due to increases in salaries and benefits and general and administrative costs, both of which were due to increases in personnel. The increase in depreciation and amortization was due to the acquisition of Bailiwick Services, LLC.
Consolidated operating income decreased 17.4% to $106.7 million. Earnings before tax decreased 13.0% to $113.0 million. Other income was $6.3 million compared to $0.7 million last year, primarily due to higher interest income.
Our effective tax rate for the current year period was 26.7%, slightly lower than last year’s 27.8%.
Net earnings decreased 11.7% to $82.8 million.
Adjusted EBITDA decreased 12.5% to $134.4 million.
Diluted earnings per common share was $3.10 for the nine months ended December 31, 2024, compared with $3.52 in the prior year. Non-GAAP diluted earnings per common share was $3.56, compared with $3.99 in the prior year.
Balance Sheet Highlights
As of December 31, 2024, cash and cash equivalents increased slightly to $253.1 million, from $253.0 million as of March 31, 2024, as cash generated from operations was used for working capital needs, the acquisition of Bailiwick Services, LLC and repurchases of our common stock. Inventory decreased 29.1% to $99.0 million compared with $139.7 million as of March 31, 2024. Total stockholders’ equity as of December 31, 2024 was $962.3 million, compared with $901.8 million as of March 31, 2024. Total shares outstanding were 26.7 million as of December 31, 2024, and 27.0 million as of March 31, 2024.
Fiscal Year 2025 Guidance
Fiscal year 2025 net sales are now expected to be in the range of $2.07 billion to $2.11 billion, and the adjusted EBITDA range is now expected to be $165.0 million to $171.0 million. ePlus cannot predict with reasonable certainty and without unreasonable effort, the ultimate outcome of unusual gains and losses, the occurrence of matters creating GAAP tax impacts, fluctuations in interest expense or interest income and share-based compensation, and acquisition-related expenses. These items are uncertain, depend on various factors, and could be material to the ePlus’ results computed in accordance with GAAP. Accordingly, ePlus is unable to provide a reconciliation of GAAP net earnings to adjusted EBITDA for the full year 2025 forecast.
Summary and Outlook
“Looking ahead, we are excited about the opportunities we see in areas including AI, cybersecurity and cloud, and are confident in our strategy of investing in these faster growth offerings. We will continue to prioritize investments in these areas as we build upon our broad suite of solutions. Importantly, our cash position is strong and our balance sheet is healthy which provides flexibility to support our growth initiatives, including organic growth in customer facing headcount and acquisitions,” concluded Mr. Marron.
Recent Corporate Developments/Recognitions
In the third quarter, ePlus:
Achieved ISO 9001 CertificationLaunched Secure GenAI AcceleratorAdditionally, effective January 3, 2025, ePlus welcomed Melissa Ballenger as a new member of the Board of Directors.
Conference Call Information
ePlus will hold a conference call and webcast at 4:30 p.m. ET on February 5, 2025:
Date:
February 5, 2025
Time:
4:30 p.m. ET
Audio Webcast (Live & Replay):
https://events.q4inc.com/attendee/412924671
Live Call:
(888) 596-4144 (toll-free/domestic)
(646) 968-2525 (international)
Archived Call:
(800) 770-2030 (toll-free/domestic)
(609) 800-9909 (international)
Conference ID:
5394845# (live call and replay)
A replay of the call will be available approximately two hours after the call through February 12, 2025. A transcript of the call will also be available on the ePlus Investor Relations website at https://www.eplus.com/investors.
About ePlus inc.
ePlus is a customer-first, services-led, and results-driven industry leader offering transformative technology solutions and services to provide the best customer outcomes. Offering a full portfolio of solutions, including artificial intelligence, security, cloud and data center, networking, and collaboration, as well as managed, consultative and professional services, ePlus works closely with organizations across many industries to successfully navigate business challenges. With a long list of industry-leading partners and more than 2,200 employees, our expertise has been honed over more than three decades, giving us specialized yet broad levels of experience and knowledge. ePlus is headquartered in Virginia, with locations in the United States, United Kingdom, Europe, and Asia‐Pacific. For more information, visit www.eplus.com, call 888-482-1122, or email info@eplus.com. Connect with ePlus on LinkedIn, X, Facebook, and Instagram.
ePlus, Where Technology Means More®.
ePlus® and ePlus products referenced herein are either registered trademarks or trademarks of ePlus inc. in the United States and/or other countries. The names of other companies and products mentioned herein may be the trademarks of their respective owners.
Forward-looking statements
Statements in this press release that are not historical facts may be deemed to be “forward-looking statements,” including, among other things, statements regarding the future financial performance of ePlus. Actual and anticipated future results may vary materially due to certain risks and uncertainties, including, without limitation, exposure to fluctuation in foreign currency rates, interest rates, and inflation, including as a result of national and international political instability fostering uncertainty and volatility in the global economy, which may cause increases in our costs and wages and our ability to increase prices to our customers, negative impacts to the arrangements that have pricing commitments over the term of an agreement and/or the loss of key lenders or constricting credit markets as a result of changing interest rates, which may result in adverse changes in our results of operations and financial position; significant adverse changes in our relationship with one or more of our larger customer accounts or vendors, including decreased account profitability, reductions in contracted services, or a loss of such relationships; a material decrease in the credit quality of our customer base, or a material increase in our credit losses, including by the federal government’s actual or attempted termination for convenience, other contract termination or non-performance; our ability to remain secure during a cybersecurity attack or other information technology (“IT”) outage, including disruptions in our, our vendors or other third party’s IT systems and data and audio communication networks; our ability to secure our own and our customers’ electronic and other confidential information, while maintaining compliance with evolving data privacy and regulatory laws and regulations and appropriately providing required notice and disclosure of cybersecurity incidents when and if necessary; ongoing remote work trends, and the increase in cybersecurity attacks that have occurred while employees work remotely and our ability to adequately train our personnel to prevent a cyber event; the possibility of a reduction of vendor incentives provided to us; our dependence on key personnel to maintain certain customer relationships, and our ability to hire, train, and retain sufficient qualified personnel by recruiting and retaining highly skilled, competent personnel, and vendor certifications; risks relating to use or capabilities of artificial intelligence (“AI”) including social and ethical risks; our ability to manage a diverse product set of solutions, including AI products and services, in highly competitive markets with a number of key vendors; changes in the IT industry and/or rapid changes in product offerings, including the proliferation of the cloud, infrastructure as a service (“IaaS”), software as a service (“SaaS”), platform as a service (“PaaS”), and AI; supply chain issues, including a shortage of IT products, may increase our costs or cause a delay in fulfilling customer orders, or increase our need for working capital, or delay completing professional services, or purchasing IT products or services needed to support our internal infrastructure or operations, resulting in an adverse impact on our financial results; our inability to identify acquisition candidates, perform sufficient due diligence prior to completing an acquisition, successfully integrate a completed acquisition, or identify an opportunity for or successfully completing a business disposition, may affect our earnings; our ability to raise capital, maintain or increase as needed our lines of credit with vendors or our floor plan facility, obtain debt for our financing transactions, or the effect of those changes on our common stock price; our ability to implement comprehensive plans for the integration of sales forces, cost containment, asset rationalization, systems integration, and other key strategies; and other risks or uncertainties detailed in our reports filed with the Securities and Exchange Commission. All information set forth in this press release is current as of the date of this release and ePlus undertakes no duty or obligation to update this information either as a result of new information, future events or otherwise, except as required by applicable U.S. securities law.
ePlus inc. AND SUBSIDIARIES
UNAUDITED CONSOLIDATED BALANCE SHEETS
(in thousands, except per share amounts)
December 31, 2024
March 31, 2024
ASSETS
Current assets:
Cash and cash equivalents
$253,074
$253,021
Accounts receivable—trade, net
594,175
644,616
Accounts receivable—other, net
62,280
46,884
Inventories
99,021
139,690
Financing receivables—net, current
148,758
102,600
Deferred costs
67,945
59,449
Other current assets
51,445
27,269
Total current assets
1,276,698
1,273,529
Financing receivables and operating leases—net
87,636
79,435
Deferred tax asset
6,087
5,620
Property, equipment and other assets–net
104,778
89,289
Goodwill
202,794
161,503
Other intangible assets—net
87,783
44,093
TOTAL ASSETS
$1,765,776
$1,653,469
LIABILITIES AND STOCKHOLDERS’ EQUITY
LIABILITIES
Current liabilities:
Accounts payable
$313,046
$315,676
Accounts payable—floor plan
115,744
105,104
Salaries and commissions payable
52,727
43,696
Deferred revenue
154,273
134,596
Non-recourse notes payable—current
24,173
23,288
Other current liabilities
36,848
34,630
Total current liabilities
696,811
656,990
Non-recourse notes payable—long-term
9,622
12,901
Other liabilities
97,003
81,799
TOTAL LIABILITIES
803,436
751,690
COMMITMENTS AND CONTINGENCIES
STOCKHOLDERS’ EQUITY
Preferred stock, $0.01 per share par value; 2,000 shares authorized; none outstanding
–
–
Common stock, $0.01 per share par value; 50,000 shares authorized; 26,703
outstanding at December 31, 2024 and 26,952 outstanding at March 31, 2024
276
274
Additional paid-in capital
192,087
180,058
Treasury stock, at cost, 880 shares at December 31, 2024 and
447 shares at March 31, 2024
(57,639)
(23,811)
Retained earnings
825,760
742,978
Accumulated other comprehensive income—foreign currency
translation adjustment
1,856
2,280
Total Stockholders’ Equity
962,340
901,779
TOTAL LIABILITIES AND STOCKHOLDERS’ EQUITY
$1,765,776
$1,653,469
ePlus inc. AND SUBSIDIARIES
UNAUDITED CONSOLIDATED STATEMENTS OF OPERATIONS
(in thousands, except per share amounts)
Three Months Ended December 31,
Nine Months Ended December 31,
2024
2023
2024
2023
Net sales
Product
$397,318
$434,371
$1,275,172
$1,457,636
Services
113,647
74,684
295,503
213,205
Total
510,965
509,055
1,570,675
1,670,841
Cost of sales
Product
297,434
328,908
959,027
1,116,046
Services
72,646
46,337
188,291
134,347
Total
370,080
375,245
1,147,318
1,250,393
Gross profit
140,885
133,810
423,357
420,448
Selling, general, and administrative
104,181
89,381
296,760
272,331
Depreciation and amortization
7,676
5,399
18,260
15,821
Interest and financing costs
517
983
1,639
3,054
Operating expenses
112,374
95,763
316,659
291,206
Operating income
28,511
38,047
106,698
129,242
Other income (expense), net
3,650
366
6,302
673
Earnings before taxes
32,161
38,413
113,000
129,915
Provision for income taxes
8,028
11,131
30,218
36,122
Net earnings
$24,133
$27,282
$82,782
$93,793
Net earnings per common share—basic
$0.91
$1.02
$3.12
$3.53
Net earnings per common share—diluted
$0.91
$1.02
$3.10
$3.52
Weighted average common shares outstanding—basic
26,495
26,618
26,568
26,598
Weighted average common shares outstanding—diluted
26,620
26,697
26,727
26,665
Technology Business
Three Months Ended December 31,
Nine Months Ended December 31,
2024
2023
Change
2024
2023
Change
(in thousands)
(in thousands)
Net sales
Product
$379,472
$419,478
(9.5 %)
$1,226,397
$1,418,581
(13.5 %)
Professional services
69,497
40,044
73.6 %
168,676
113,870
48.1 %
Managed services
44,150
34,640
27.5 %
126,827
99,335
27.7 %
Total
493,119
494,162
(0.2 %)
1,521,900
1,631,786
(6.7 %)
Gross profit
Product
84,046
91,919
(8.6 %)
271,910
308,059
(11.7 %)
Professional services
27,841
17,332
60.6 %
68,879
47,852
43.9 %
Managed services
13,160
11,015
19.5 %
38,333
31,006
23.6 %
Total
125,047
120,266
4.0 %
379,122
386,917
(2.0 %)
Selling, general, and administrative
100,441
86,001
16.8 %
284,575
261,694
8.7 %
Depreciation and amortization
7,676
5,381
42.7 %
18,260
15,747
16.0 %
Interest and financing costs
–
217
(100.0 %)
–
1,428
(100.0 %)
Operating expenses
108,117
91,599
18.0 %
302,835
278,869
8.6 %
Operating income
$16,930
$28,667
(40.9 %)
$76,287
$108,048
(29.4 %)
Gross billings
$849,546
$796,986
6.6 %
$2,491,482
$2,495,451
(0.2) %
Adjusted EBITDA
$27,498
$36,725
(25.1 %)
$103,803
$132,170
(21.5) %
Technology Business Gross Billings by Type
Three Months Ended December 31,
Nine Months Ended December 31,
2024
2023
Change
2024
2023
Change
(in thousands)
(in thousands)
Networking
$214,762
$251,322
(14.5 %)
$716,087
$839,638
(14.7 %)
Cloud
207,762
181,559
14.4 %
644,888
641,120
0.6 %
Security
190,808
189,476
0.7 %
506,256
480,159
5.4 %
Collaboration
22,381
23,180
(3.4 %)
102,074
97,111
5.1 %
Other
76,513
55,473
37.9 %
193,650
203,805
(5.0 %)
Product gross billings
712,226
701,010
1.6 %
2,162,955
2,261,833
(4.4 %)
Service gross billings
137,320
95,976
43.1 %
328,527
233,618
40.6 %
Total gross billings
$849,546
$796,986
6.6 %
$2,491,482
$2,495,451
(0.2 %)
Technology Business Net Sales by Type
Three Months Ended December 31,
Nine Months Ended December 31,
2024
2023
Change
2024
2023
Change
(in thousands)
(in thousands)
Networking
$181,367
$209,936
(13.6 %)
$602,883
$723,760
(16.7 %)
Cloud
116,864
120,253
(2.8 %)
375,431
427,365
(12.2 %)
Security
53,919
58,822
(8.3 %)
143,133
156,504
(8.5 %)
Collaboration
8,391
13,608
(38.3 %)
47,278
53,647
(11.9 %)
Other
18,931
16,859
12.3 %
57,672
57,305
0.6 %
Total product
379,472
419,478
(9.5 %)
1,226,397
1,418,581
(13.5 %)
Professional services
69,497
40,044
73.6 %
168,676
113,870
48.1 %
Managed services
44,150
34,640
27.5 %
126,827
99,335
27.7 %
Total net sales
$493,119
$494,162
(0.2 %)
$1,521,900
$1,631,786
(6.7 %)
Technology Business Net Sales by Customer End Market
Three Months Ended December 31,
Nine Months Ended December 31,
2024
2023
Change
2024
2023
Change
(in thousands)
(in thousands)
Telecom, Media, & Entertainment
$126,201
$139,551
(9.6 %)
$352,624
$405,192
(13.0 %)
SLED
71,412
60,108
18.8 %
261,195
264,419
(1.2 %)
Technology
71,293
83,951
(15.1 %)
235,387
268,302
(12.3 %)
Healthcare
58,670
55,504
5.7 %
212,185
214,182
(0.9 %)
Financial Services
46,217
38,816
19.1 %
130,701
174,391
(25.1 %)
All other
119,326
116,232
2.7 %
329,808
305,300
8.0 %
Total net sales
$493,119
$494,162
(0.2 %)
$1,521,900
$1,631,786
(6.7 %)
Financing Business Segment
Three Months Ended December 31,
Nine Months Ended December 31,
2024
2023
Change
2024
2023
Change
(in thousands)
(in thousands)
Portfolio earnings
$4,466
$3,701
20.7 %
$13,491
$10,113
33.4 %
Transactional gains
8,477
8,107
4.6 %
24,272
16,335
48.6 %
Post-contract earnings
4,743
2,685
76.6 %
10,163
11,357
(10.5 %)
Other
160
400
(60.0 %)
849
1,250
(32.1 %)
Net sales
17,846
14,893
19.8 %
48,775
39,055
24.9 %
Gross profit
15,838
13,544
16.9 %
44,235
33,531
31.9 %
Selling, general, and administrative
3,740
3,380
10.7 %
12,185
10,637
14.6 %
Depreciation and amortization
–
18
(100.0 %)
–
74
(100.0 %)
Interest and financing costs
517
766
(32.5 %)
1,639
1,626
0.8 %
Operating expenses
4,257
4,164
2.2 %
13,824
12,337
12.1 %
Operating income
$11,581
$9,380
23.5 %
$30,411
$21,194
43.5 %
Adjusted EBITDA
$11,651
$9,464
23.1 %
$30,612
$21,466
42.6 %
ePlus inc. AND SUBSIDIARIES
RECONCILIATION OF NON-GAAP INFORMATION
We included reconciliations below for the following non-GAAP financial measures: (i) Adjusted EBITDA, (ii) Adjusted EBITDA for business segments, (iii) non-GAAP Net Earnings and (iv) non-GAAP Net Earnings per Common Share – Diluted.
We define Adjusted EBITDA as net earnings calculated in accordance with US GAAP, adjusted for the following: interest and financing costs, depreciation and amortization, share-based compensation, acquisition related expenses, provision for income taxes, and other income (expense). Adjusted EBITDA presented for the technology business segments and the financing business segment is defined as operating income calculated in accordance with US GAAP, adjusted for interest and financing costs, share-based compensation, acquisition related expenses, and depreciation and amortization. We consider the interest on notes payable from our financing business segment and depreciation expense presented within cost of sales, which includes depreciation on assets financed as operating leases, to be operating expenses. As such, they are not included in the amounts added back to net earnings in the Adjusted EBITDA calculation.
Non-GAAP net earnings and non-GAAP net earnings per common share – diluted are based on net earnings calculated in accordance with GAAP, adjusted to exclude other (income) expense, share based compensation, acquisition related expenses, and acquisition related amortization expenses, and the related tax effects.
We use the above non-GAAP financial measures as supplemental measures of our performance to gain insight into our operating performance and performance trends. We believe that such non-GAAP financial measures provide management and investors a useful measure for period-to-period comparisons of our business and operating results by excluding items that management believes are not reflective of our underlying operating performance. Accordingly, we believe that such non-GAAP financial measures provide useful information to investors and others in understanding and evaluating our operating results.
Our use of non-GAAP information as analytical tools has limitations, and you should not consider them in isolation or as substitutes for analysis of our financial results as reported under GAAP. In addition, other companies, including companies in our industry, might calculate adjusted EBITDA, non-GAAP net earnings and non-GAAP net earnings per common share or similarly titled measures differently, which may reduce their usefulness as comparative measures.
Three Months Ended December 31,
Nine Months Ended December 31,
2024
2023
2024
2023
(in thousands)
Consolidated
Net earnings
$24,133
$27,282
$82,782
$93,793
Provision for income taxes
8,028
11,131
30,218
36,122
Share based compensation
2,933
2,526
8,385
7,145
Acquisition related expenses
29
–
1,072
–
Interest and financing costs
–
217
–
1,428
Depreciation and amortization [1]
7,676
5,399
18,260
15,821
Other (income) expense, net [2]
(3,650)
(366)
(6,302)
(673)
Adjusted EBITDA
$39,149
$46,189
$134,415
$153,636
Technology Business Segments
Operating income
$16,930
$28,667
$76,287
$108,048
Share based compensation
2,863
2,460
8,184
6,947
Depreciation and amortization [1]
7,676
5,381
18,260
15,747
Acquisition related expenses
29
–
1,072
–
Interest and financing costs
–
217
–
1,428
Adjusted EBITDA
$27,498
$36,725
$103,803
$132,170
Financing Business Segment
Operating income
$11,581
$9,380
$30,411
$21,194
Share based compensation
70
66
201
198
Depreciation and amortization [1]
–
18
–
74
Adjusted EBITDA
$11,651
$9,464
$30,612
$21,466
Three Months Ended December 31,
Nine Months Ended December 31,
2024
2023
2024
2023
(in thousands)
GAAP: Earnings before taxes
$32,161
$38,413
$113,000
$129,915
Share based compensation
2,933
2,526
8,385
7,145
Acquisition related expenses
29
–
1,072
–
Acquisition related amortization expense [3]
5,983
3,856
14,180
11,348
Other (income) expense [2]
(3,650)
(366)
(6,302)
(673)
Non-GAAP: Earnings before provision for income taxes
37,456
44,429
130,335
147,735
GAAP: Provision for income taxes
8,028
11,131
30,218
36,122
Share based compensation
734
733
2,263
2,005
Acquisition related expenses
7
–
300
–
Acquisition related amortization expense [3]
1,495
1,115
3,788
3,173
Other (income) expense, net [2]
(913)
(106)
(1,656)
(190)
Tax benefit (expense) on restricted stock
21
10
513
226
Non-GAAP: Provision for income taxes
9,372
12,883
35,426
41,336
Non-GAAP: Net earnings
$28,084
$31,546
$94,909
$106,399
Three Months Ended December 31,
Nine Months Ended December 31,
2024
2023
2024
2023
GAAP: Net earnings per common share – diluted
$0.91
$1.02
$3.10
$3.52
Share based compensation
0.08
0.07
0.23
0.19
Acquisition related expenses
–
–
0.03
–
Acquisition related amortization expense [3]
0.17
0.10
0.39
0.30
Other (income) expense, net [2]
(0.10)
–
(0.17)
(0.01)
Tax benefit (expense) on restricted stock
–
(0.00)
(0.02)
(0.01)
Total non-GAAP adjustments – net of tax
0.15
0.16
0.46
0.47
Non-GAAP: Net earnings per common share – diluted
$1.06
$1.18
$3.56
$3.99
[1] Amount consists of depreciation and amortization for assets used internally.
[2] Interest income and foreign currency transaction gains and losses.
[3] Amount consists of amortization of intangible assets from acquired businesses.
View original content to download multimedia:https://www.prnewswire.com/news-releases/eplus-reports-third-quarter-and-first-nine-months-results-302369308.html
SOURCE EPLUS INC.

You may like
Technology
Truth-seeking: the Turning Point in Zunyi
Published
42 minutes agoon
October 19, 2026By

BEIJING, Oct. 18, 2026 /PRNewswire/ — An interview from China.org.cn with Wang Xiaohui and David Ferguson on the Long March:
Wang Xiaohui:
When you march toward your ideals but encounter repeated setbacks and failures, do you have the courage to pause, reflect on the path taken, and chart a new way forward?
David Ferguson:
If I continually encountered setbacks on the road to my ideals, I would stop and reflect seriously on whether my methods need adjusted or my direction needs corrected. This is a matter of being honest with oneself and honest about one’s shortcomings. Granted, this requires as much courage as setting out in the first place — because what you have to confront is not only the judgment of others, but your own ingrained reluctance to accept that you might have got it wrong.
Wang Xiaohui:
The waters of the Xiangjiang River ran crimson in the winter of 1934.
To cover the Red Army’s main force as they crossed the river, Chen Shuxiang, then Commander of the 34th Division of the Fifth Army Corps, led his troops to fight against vastly superior enemy forces until they ran out of ammunition and supplies. Severely wounded, Chen was captured alive. On the way to the enemy camp to be paraded for merit, Chen seized a moment of the enemy’s unawareness, tore his own intestines through his abdominal wound, and died a heroic death. He was only 29 years old.
The Battle of Xiangjiang River was the deadliest campaign for the Red Army since the start of the Long March. In less than two months, their troop strength plummeted from over 86,000 to just over 30,000.
At that critical moment, doubts and discontent among officers and soldiers with the military leadership peaked.
During the fights against the previous four Kuomintang (KMT) “encirclement” campaigns, the Red Army adopted Mao Zedong’s strategy of “luring the enemy in deep.” With flexible tactics in mobile warfare, the Red Army worked miracles of defeating superior enemies time and again. Yet, the tide turned completely during the KMT’s fifth “encirclement.”
At that time, the CPC was a branch of the Communist International (Comintern). After 1927, the Comintern instructed the CPC to adopt an urban-centered path in its revolution, for it was how Russia’s October Revolution had achieved victory. Affected by this directive, during the Fifth Counter-Campaign against “Encirclement and Suppression”, Bo Gu and Otto Braun, who held actual command of the Red Army, insisted on launching offensive operations to seize major cities.
Otto Braun also mechanically applied European conventional warfare tactics, forcing the Red Army into rigid positional and fortress battles. In the Battle of Guangchang, the poorly equipped Red Army fought head-on against enemy tanks and artillery on open terrain, resulting in more than 5,000 casualties, about one-fourth of all participating troops.
Successive military defeats forced the Red Army to launch a strategic shift. However, Bo Gu and Otto Braun insisted that everything be evacuated, including heavy equipment: printing presses, currency-making machines, and arms-manufacturing facilities… When crossing the Xiangjiang River, troops were slowed down by these cumbersome supplies, and numerous soldiers even laid down their lives for protecting these assets. Chen Shuxiang and his 34th Division wrote the gravest footnote to this bloody sacrifice.
By the banks of the Xiangjiang River, the spark of hope in the eyes of the Red Army soldiers was nearly quenched by the cold water. Could the rigid foreign doctrines truly guide the Red Army and China’s revolution? What path lay ahead?
History often unfolds in paradoxes: when all hope seems lost, a historical turning point is quietly emerging.
After the Battle of Xiangjiang River, Mao firmly opposed the original plan drafted by Bo Gu and Otto Braun to march towards Hunan. Instead, he proposed to advance to Guizhou where enemy defenses were weak. There, the Red Army broke through the natural barrier of the Wujiang River, and captured Zunyi. On Jan. 15, 1935, the CPC Central Committee convened an enlarged Political Bureau meeting in an old mansion, later known to the world as the Zunyi Conference.
Inside the modest living room on the second floor, a charcoal brazier expelled the winter chill. The CPC leadership sat around a long table to review why the Red Army had fallen into passive positions since 1933. Bo Gu attributed the defeats solely to the enemy’s overwhelming strength, while other leading officials like Zhou Enlai and Zhang Wentian pinpointed flawed military command as the fundamental cause.
Mao Zedong also made a pivotal speech.
As a revolutionary forged in rural base-area practice, Mao always sought truth from real combat experience. Citing victories from the previous four counter-“encirclement” campaigns, he rebutted Bo Gu’s opinions and criticized the flawed strategies of passive defense and abandoning mobile warfare tactics. In plain, incisive language, he pointed out that “the soldiers also needed to march, eat and sleep,” and that Braun’s rigid commands were completely divorced from the realities of China’s revolutionary warfare.
Throughout the whole meeting, Bo Gu remained dejected; Braun sat near the door and lit one cigarette after another. Never had these “true Bolsheviks” faced such rigorous criticism before.
The intensive confrontation lasted three days. In the end, Mao Zedong was elected to the leadership of the Red Army and the CPC Central Committee, putting an end to the wrong guidance. This marked a life-and-death turning point in the history of the Communist Party of China.
The Zunyi Conference freed the CPC from the Comintern’s intervention, enabling the Party to independently master the destiny of China’s revolution. From then on, the Red Army turned peril into safety, and China’s revolution emerged from despair toward new life.
David Ferguson:
When faced with major setbacks, the Communist Party of China was not crushed; instead, it demonstrated the courage to confront and correct its own mistakes, thereby turning adversity into opportunity. For any ruling party, this kind of courage is exceptionally rare.
Throughout history, guided by the principle of seeking truth from facts, the Party has always corrected errors, updated systems and adjusted course. By doing so, it has guaranteed social progress. This is precisely the secret to success that has made the Party resilient and invincible.
Wang Xiaohui:
No grand undertaking advances without setbacks. Faced with obstacles and defeats, the CPC demonstrated extraordinary courage and wisdom. They sought truth from facts, corrected wrong courses, and led the revolution towards triumph.
The Zunyi Conference Spirit, embodied in firm conviction, adherence to truth, independence and self-reliance, solidarity and unity, was forged amid blood and fire. It has shaped the unique spiritual character of the CPC. In the years that followed, these timeless values continued to evolve and sustain the Party in the face of trials and challenges, endowing it with enduring vitality.
China Mosaic
http://www.china.org.cn/video/node_7230027.htm
Faith: The Spark Born by the Yudu Riverside
http://www.china.org.cn/2026-10/17/content_118737624.shtml
View original content to download multimedia:https://www.prnewswire.com/news-releases/truth-seeking-the-turning-point-in-zunyi-302912139.html
SOURCE China.org.cn
Technology
GMIF2026: AI Inference Powers the “Token Factory” and Drives System-Level Rethinking of Memory & Storage
Published
42 minutes agoon
October 19, 2026By
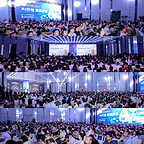
SHENZHEN, China, Oct. 18, 2026 /PRNewswire/ — The 5th GMIF Innovation Summit (Global Memory Innovation Forum 2026, GMIF2026) recently concluded at the Renaissance Shenzhen Bay Hotel. Co-hosted by the Shenzhen Memory Industry Association (SMIA) and the School of Integrated Circuits at Peking University, the summit was themed “The Future Built on AI Memory and Storage.” Now in its fifth edition, GMIF has grown from a regional industry gathering into a benchmark for the global semiconductor memory ecosystem, with diversified programs including keynote sessions, an investment forum, product exhibitions, a global livestream, and a golf friendship match, all centered on the value of memory and storage in the token economy and the AI inference era.
In the opening remarks by Rixin Sun, President of Shenzhen Memory Industry Association (SMIA), GMIF’s growth over five consecutive editions was traced from its early days to today. As a platform for global exchange, GMIF is built around the memory value chain, linking wafer IDMs and players in controllers, modules, packaging and testing, equipment and materials, and end applications to promote technical exchange, supply-demand matching, and ecosystem cooperation.
President Sun noted that as AI evolves from generative to agentic, inference efficiency, data scheduling, and system coordination have become shared priorities. Collaboration across the value chain is no longer a traditional supply-demand relationship, but a deeper partnership built around workload requirements, joint product definition, and scenario validation. Looking ahead, GMIF will pursue a more specialized and differentiated format, connecting memory companies with AI compute and end-application players worldwide.
Capital Meets Technology: Memory & Storage Moves to the Center of AI Infrastructure
As AI shifts from model training to large-scale commercial inference, the token is becoming a new unit of value. Inference demands low latency, high concurrency, and sustained throughput, which places memory and storage bandwidth, capacity, and energy efficiency among the variables that shape overall system efficiency and cost.
Daniel Yen of Morgan Stanley projected that global data center capital expenditure will stay strong in the coming years, with more than half of cloud data center capex expected to go to memory & storage (excluding HBM) by 2027. Yen identified six innovation paths to overcome the “memory wall” challenge: process migration, design changes, advanced packaging, memory peripherals, PIM/CIM, and new materials.
Prof. Yimao Cai, Dean of the School of Integrated Circuits at Peking University, pointed out that HBM remains central to high-end AI compute, but yield, cost, and thermal constraints limit broader adoption. NAND-based high-bandwidth technologies such as HBF have become a major research focus because of their cost advantage, and hybrid multi-media architectures could balance performance, capacity, and cost for deploying models with hundreds of billions of parameters.
Kevin Yoon, CVP & CTO of Samsung Memory China at Samsung Electronics, described how agents are generating massive KV cache demand and driving rapid iteration of tiered storage, citing Samsung’s work on Z-NAND, PCIe Gen6 SSDs, and ultra-high-capacity data center SSDs. Maya Zhang, Senior Director of Product Marketing from Sandisk, called this the first year of the “inference boom.” As inference reaches commercial scale, AI data centers are shifting from cost centers to value and capacity centers, and the evaluation framework is moving from TCO to TVO. NAND is becoming a strategic core component of AI, and the SSD is becoming a “token battery” that greatly improves the economics of the industry through token reuse.
Solidigm and Arm focused on the evolution of system-level design. Benny Ni, GAR Sales VP at Solidigm, noted high-capacity QLC SSDs are being adopted faster, and that memory offloading has moved from an alternative to a core design paradigm for data centers, while liquid cooling has become a prerequisite for unlocking high-end storage performance. John Xavier Lionel, Head of Global Storage Business at Arm, shared competition in the AI era is shifting from simply chasing higher TOPS to building a more efficient system balance among compute, memory, storage, and data movement. Arm’s cloud-edge-device continuum framework balances power, capacity, bandwidth, latency, security, and cost constraints at each tier, so that “the right AI workload runs in the right place.”
Moving from the cloud to the edge, Stanley Huang, AVP of Silicon Motion, stressed that devices are the ultimate carrier of AI experiences and that intelligent storage directly determines real-world device performance. Its PerformaShape technology allocates resources flexibly across different agents and greatly improves read/write consistency.
Sam Sun, Chairman of BIWIN, explained that large-scale AI inference is extending memory demand from data centers to the edge and endpoints, where differing needs in capacity, performance, power, size, and reliability are pushing storage from general-purpose specifications toward deep matching with specific scenarios and platforms. Drawing on full-stack capabilities from media selection and controller and firmware development to advanced packaging, testing, and volume delivery, BIWIN works closely with customers, platforms, and chip makers to tailor products to each use case, shortening development and validation cycles and improving system space, energy efficiency, and performance.
Token Factories Move Enterprise AI from Pilot to Production
As the token becomes the core unit of value, producing tokens efficiently and at low cost has become a shared challenge for enterprise AI adoption worldwide, and the “token factory” is emerging as a new industry paradigm. Tao Zhou, General Manager of the Server Division of Lenovo ISG China, said 80% of enterprises have deployed at least one type of agent, yet fewer than 40% of projects can scale and deliver positive ROI. Lenovo has built a full-stack “token factory” paradigm spanning data governance, compute optimization, and security management to address this.
A solid token factory depends on underlying storage media and architecture. Numbers Law’s PMD (Parallel Magnetic Drive) technology and NEXWISE‘s “KuberCloud” token factory solution contributed to full-stack capability from hardware to compute scheduling and model operations. Infplane, Maxio, and Genstoraige lowered the deployment threshold for large on-device models through AI SSD tiered offloading and memory expansion.
Real-world applications are also deepening. SYNCORE has achieved vehicle-cloud embodied intelligence across the whole vehicle. Dify, with its private agent architecture, and Paratera, with its MaaS compute service platform, are moving AI from basic compute supply toward deeper industry intelligence services, accelerating the industrialization of AI.
40 Companies Showcase the Core of the AI Memory & Storage Chain
The concurrent exhibition brought together 40 companies across the full value chain, from memory chips and controllers to compute servers, AIDC services, packaging and testing equipment, and system applications, presenting the latest advances in AI memory and storage from around the world.
Memory IDMs and controller makers led with new products. SanDisk featured its iNAND AT EU752 automotive UFS 4.1, SN861 enterprise NVMe SSD, and BiCS8 QLC NAND. Silicon Motion introduced the SM8466 PCIe Gen6 16-channel controller and the SM2524XT controller for edge SSDs. Maxio, YEESTOR, and other Chinese controller makers showed flagship PCIe Gen4/Gen5 and UFS controllers with enhanced LDPC, a sign that China’s controller portfolio is taking shape and benchmarking itself against leading international standards.
Compute and token factory solutions were another highlight. Lenovo exhibited its WenTian series of AI training-and-inference integrated servers. NEXWISE presented its full-stack token factory hardware and software, with heterogeneous compute management and token-based billing. Paratera showed its intelligent compute cloud and supercomputing cloud services, and Numbers Law demonstrated its PMD (Parallel Magnetic Drive) technology, aimed at sharply raising HDD IOPS and throughput. Infplane, Genstoraige, and Quanxing introduced KV cache offload and memory-fusion AI SSD solutions that use storage to share the compute load and significantly cut deployment costs.
Module makers and full-scenario solution providers brought a wide range of products. BIWIN exhibited enterprise SSDs, CXL products, wide-temperature industrial storage, and embedded products spanning AI cloud, edge, and device. KingSpec, POWEV, Topdisk, Barycn, Jielong Storage, HIKSEMI, and others presented industrial-grade, automotive-grade, server, and embedded product families, demonstrating strong volume production and reliable delivery.
Equipment, testing, and materials suppliers rounded out the floor. Attach Point, MICROVIEW, and Maxwell Technologies showed die attach and bonding equipment for 2.5D/3D advanced packaging. OKN Technology, Acroview Technology, Hongjingwei, and Tytantest introduced test and burn-in systems covering SSD, DRAM, and NAND that can accurately reproduce high-load AI I/O scenarios. Hemei Jingyi and Silergy brought storage IC package substrates and dedicated power management ICs. From advanced packaging equipment to test validation to core components, this supporting ecosystem lays the manufacturing foundation for volume production of AI memory and storage and for Chinese suppliers expanding overseas.
GMIF2026 Annual Awards Unveiled: Global Memory & Storage Leaders Build an Open, Collaborative Ecosystem
To recognize companies that have made outstanding contributions to the memory and storage value chain, the summit established the GMIF2026 Annual Awards, which cover memory, compute, packaging and testing equipment, test systems, and end applications across AI infrastructure, and were judged on technological innovation, industry contribution, market service, and real-world results.
Honorees, including Samsung Semiconductor, SanDisk, Solidigm, CXMT, Arm, Lenovo, Dify, Silicon Motion, Infplane, Genstoraige, Numbers Law, Paratera, SYNCORE, NEXWISE, Maxio Technology, BIWIN, Topdisk, KingSpec, POWEV, Quanxing Technology, OKN Technology, Attach Point, COMIX, Barycn, LKAUTO, Maxwell Technologies, Hemei Jingyi, Silergy, Heyan Technology, ExTripod Electronics, UNIMOS, GBAT, and Tytantest, were recognized for standout achievements in technology breakthroughs, product deployment, ecosystem building, and the industry chain.
Global Livestream and Golf Friendship Match Extend the Boundaries of Industry Cooperation
To join the global ecosystem and expand international cooperation, the summit featured a special Global Livestream by Memory Brands on LinkedIn, Facebook, and YouTube. Eight brands presented online: BIWIN, Silicon Motion, Quanxing Technology, OKN Technology, KingSpec, Maxwell Technologies, ExTripod Electronics, and Silergy. They gave overseas audiences a direct look at China’s latest advances in memory chips, advanced packaging, test systems, and other core AI infrastructure components, connecting technology standards, supply chain resources, and market demand across regions.
The momentum carried into the next day. The GMIF2026 “BIWIN Cup” golf friendship match, exclusively sponsored by BIWIN, brought senior executives from across the global memory value chain to the course. After a day of intensive discussion at the main forum, the setting was more relaxed, but the conversations among technology, capital, and markets carried on, helping speed practical cooperation across borders and sectors.
Conclusion
Across the GMIF program, one message stood out: global AI competition is moving beyond the “single-point era” of peak GPU performance into a “system-level era” that integrates storage, compute, networking, and software. In the token economy, memory and storage is shedding its auxiliary role and becoming the strategic foundation of AI inference.
This edition of GMIF brought together capital outlook, frontier technology, product innovation, real-world practice, and ecosystem collaboration, and, with the awards, livestream, and networking events, carried the conversation from ideas to product showcases, overseas exposure, and business deals. Going forward, GMIF will stay focused on the industry’s frontier issues and connect key players across the global memory value chain, promoting joint standards, technology development, and market expansion to open a new chapter for the AI memory and storage industry.
About GMIF
Global Memory Innovation Forum (GMIF) is a premier annual gathering that connects the global memory and storage community. Featuring diverse activities including keynote speeches, roundtable dialogues, supply-demand match-making, product showcases, industry rankings, awards programs, and global livestreaming, GMIF brings together key enterprises across the memory and storage chain, technical experts, terminal companies and investment institutions to exchange insights, build partnerships, and create business opportunities. Learn more about GMIF, please visit https://www.gmif.com.cn/. Follow us on LinkedIn, YouTube and Facebook.
Media Contact:
Carina Gu, wenjing.gu@gmif.com.cn
View original content to download multimedia:https://www.prnewswire.com/news-releases/gmif2026-ai-inference-powers-the-token-factory-and-drives-system-level-rethinking-of-memory–storage-302912123.html
SOURCE Shenzhen Memory Industry Association (SMIA)

Truth-seeking: the Turning Point in Zunyi
Truth-seeking: the Turning Point in Zunyi

GMIF2026: AI Inference Powers the “Token Factory” and Drives System-Level Rethinking of Memory & Storage

Send Rakhi to UK swiftly with UK Gifts Portal

Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

Nullmax and Renesas Forge Strategic Partnership to Deliver Competitive ADAS Solutions for the Global Market

Why You Should Build on #NEAR – Co-founder Illia Polosukhin at CV Labs
Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

NEAR End of Year Town Hall 2021: The Open Web World, MetaBUILD 2 Hackathon and 2021 recap
Trending
-
 Coin Market5 days ago
‘Bunker mode’ won’t protect your crypto, critics say
-
 Technology5 days ago
Solidion Technology Reaffirms Commitment to Address Growing Energy Storage Needs of AI Data Centers
-
 Technology5 days ago
TVU Networks to Showcase Connected Live Video Ecosystem at Broadcast India Show 2026
-
 Technology5 days ago
PEGATRON Brings AI Infrastructure from Design to Deployment at OCP Global Summit 2026
-
 Coin Market4 days ago
Organizations join forces to fight Illinois crypto tax, after 6-month pause
-
 Technology5 days ago
SUS ENVIRONMENT Draws International Attention for Transforming Waste-to-Energy Plants into Sustainable Urban Assets
-
 Coin Market5 days ago
Can crypto users trust the supply chain behind hardware wallets?
-
 Technology5 days ago
A $2.1 Trillion Wellness Industry Never Built a Daily Practice for Black Children. So This Atlanta Family Did.