
Technology
PTC ANNOUNCES FIRST FISCAL QUARTER 2025 RESULTS

Published
2 years agoon
By
Solid ARR and Cash Flow
BOSTON, Feb. 5, 2025 /PRNewswire/ — PTC (NASDAQ: PTC) today reported financial results for its first fiscal quarter ended December 31, 2024.
“In Q1’25, we delivered solid year-over-year constant currency ARR growth of 11% and cash flow growth above 25%, which was in-line with our guidance. Our differentiated strategy leverages our unique portfolio to help product companies accelerate their time to market and manage increasing complexity. It’s an exciting time because our products are at the epicenter of driving business transformation at our customers,” said Neil Barua, President and CEO, PTC.
“In order to better serve the needs of our customers and strengthen our ability to drive consistent growth, in Q1’25, we began the realignment of our go-to-market organization to align with the vertical industries we serve. We will continue to focus on optimizing how we operate, so we can increase customer value while also enhancing shareholder returns,” concluded Barua.
First Fiscal Quarter 2025 Highlights
Key operating and financial highlights are set forth below. The definitions of our operating and non-GAAP financial measures and reconciliations of non-GAAP financial measures to comparable GAAP measures are included below and in the reconciliation tables at the end of this press release.
$ in millions
Q1’25
Q1’24
YoY Change
Q1’25
Guidance
ARR as reported
$2,205
$2,057
7 %
Constant currency ARR (FY’25 Plan FX rates1)
$2,277
$2,059
11 %
~10.5% growth
Operating cash flow
$238
$187
27 %
~$234
Free cash flow
$236
$183
29 %
~$230
Revenue2
$565
$550
3%3
$540 to $570
Operating margin2
20 %
22 %
(110 bps)
Non-GAAP operating margin2
34 %
36 %
(240 bps)
Earnings per share2
$0.684
$0.55
23 %
$0.28 to $0.52
Non-GAAP earnings per share2
$1.10
$1.11
(0 %)
$0.75 to $0.95
Total cash and cash equivalents
$196
$265
(26 %)
Gross debt5
$1,548
$2,267
(32 %)
1
On a constant currency basis, using our FY’25 Plan foreign exchange rates (rates as of September 30, 2024) for all periods.
2
Revenue and, as a result, operating margin and earnings per share are impacted under ASC 606.
3
In Q1’25, revenue grew 2% year over year on a constant currency basis.
4
Q1’25 GAAP EPS included a non-cash tax benefit of $5.4 million or $0.04, due to the release of a tax reserve related to prior years.
5
Gross debt excludes unamortized debt issuance costs.
“In a selling environment that continued to be challenging, our Q1’25 ARR grew 11% year over year on a constant currency basis. Our Q1’25 cash flow was solid, with operating cash flow growing 27% year over year and free cash flow growing 29% year over year, driven by ARR growth and a disciplined process for incremental investment in our business. Additionally, as we indicated, we resumed share repurchases, buying back $75 million worth of our stock in Q1,” said Kristian Talvitie, CFO.
“Given our differentiated product portfolio, the resilience of our subscription business model, the actions we have taken over time to align our investments with market opportunities, and allowing that our go-to-market changes are expected to take time to have their intended effect, we expect Q2’25 constant currency ARR growth of approximately 9.5%. Supported by ARR growth, the predictability of our cash collections, the disciplined budgeting structure we have in place, and being mindful of foreign exchange rate fluctuations, we expect Q2’25 free cash flow of approximately $270 million. We also intend to continue to execute on our share repurchase program, with approximately $75 million of buy backs expected in Q2’25,” Talvitie concluded.
Full Fiscal Year 2025 and Second Fiscal Quarter Guidance
$ in millions
FY’25 Previous
Guidance
FY’25
Guidance
FY’25 YoY
Growth
Guidance
Q2’25
Guidance
Constant currency ARR (FY’25 Plan FX rates1)
9% to 10% growth
9% to 10% growth
9% to 10%
~9.5% growth
Operating cash flow
$850 to $8652
$850 to $8652
13% to 15%
~$2742
Free cash flow
$835 to $8502
$835 to $8502
14% to 16%
~$2702
Revenue
$2,505 to $2,605
$2,430 to $2,530
6% to 10%
$590 to $620
Earnings per share
$3.68 to $4.57
$3.36 to $4.24
8% to 36%
$0.79 to $1.05
Non-GAAP earnings per share
$5.60 to $6.30
$5.30 to $6.00
4% to 18%
$1.30 to $1.50
1
On a constant currency basis, using our FY’25 Plan foreign exchange rates (rates as of September 30, 2024) for all periods.
2
FY’25 cash flow guidance includes approximately $20 million of outflows related to go-to-market realignment, of which $11 million was paid out in Q1’25 and approximately $4 million is expected in Q2’25.
Reconciliation of Operating Cash Flow Guidance to Free Cash Flow Guidance
$ in millions
FY’25
Guidance
Q2’25
Guidance
Operating cash flow
$850 to $865
~$274
Capital expenditures
~$15
~$4
Free cash flow
$835 to $850
~$270
Reconciliation of EPS Guidance to Non-GAAP EPS Guidance
FY’25
Guidance
Q2’25
Guidance
Earnings per share
$3.36 to $4.24
$0.79 to $1.05
Stock-based compensation expense
$1.90 to $1.66
$0.48 to $0.40
Intangible asset amortization expense
~$0.65
~$0.16
Impairment charges to right-of-use lease assets
~$0.04
~$0.04
Income tax adjustments related to the reconciling items
($0.65) to ($0.59)
($0.17) to ($0.15)
Non-GAAP Earnings per share
$5.30 to $6.00
$1.30 to $1.50
FY’25 financial guidance includes the following assumptions:
We provide ARR guidance on a constant currency basis, using our FY’25 Plan foreign exchange rates (rates as of September 30, 2024) for all periods.We expect churn to remain low.For cash flow, due to largely similar invoicing seasonality, and consistent with the past 4 years, we expect the majority of our collections to occur in the first half of our fiscal year and for fiscal Q4 to be our lowest cash flow generation quarter.Compared to FY’24, at our FY’25 ARR guidance, FY’25 GAAP operating expenses are expected to increase approximately 4% and FY’25 non-GAAP operating expenses are expected to increase approximately 5%, primarily due to investments to drive future growth.Cash flow guidance includes approximately $20 million of outflows related to go-to-market realignment.Capital expenditures are expected to be approximately $15 million.Cash interest payments are expected to be approximately $90 million.Cash tax payments are expected to be approximately $110 million.GAAP and non-GAAP tax rates are expected to be approximately 25%.GAAP P&L results are expected to include the items below, totaling approximately $284 million to $314 million, as well as their related tax effects:approximately $200 million to $230 million of stock-based compensation expense,approximately $79 million of intangible asset amortization expense, andapproximately $5 million of impairment charges to right-of-use lease assets related to facilities subleasing activities.Our long-term goal, assuming our Debt/EBITDA ratio is below 3x, is to return approximately 50% of our free cash flow to shareholders via share repurchases, while also taking into consideration the interest rate environment and strategic opportunities.We currently intend to repurchase approximately $300 million of our common stock in FY’25 and retire the $500 million senior notes due in Q2’25.We currently expect our fully diluted share count to be approximately flat in FY’25.
PTC’s First Fiscal Quarter Results Conference Call
The Company will host a conference call to discuss results at 5:00 pm ET on Wednesday, February 5, 2025. To participate in the live conference call, dial (888) 330-2508 or (240) 789-2735, provide the passcode 7328695, and press # or log in to the webcast, available on PTC’s Investor Relations website. A replay will also be available.
Important Information About Our Operating and Non-GAAP Financial Measures
Non-GAAP Financial Measures
We provide supplemental non-GAAP financial measures to our financial results. We use these non-GAAP financial measures, and we believe that they assist our investors, to make period-to-period comparisons of our operating performance because they provide a view of our operating results without items that are not, in our view, indicative of our operating results. These non-GAAP financial measures should not be construed as an alternative to GAAP results as the items excluded from the non-GAAP financial measures often have a material impact on our operating results, certain of those items are recurring, and others often recur. Management uses, and investors should consider, our non-GAAP financial measures only in conjunction with our GAAP results.
Non-GAAP operating expense, non-GAAP operating margin, non-GAAP gross profit, non-GAAP gross margin, non-GAAP net income and non-GAAP EPS exclude the effect of the following items: stock-based compensation; amortization of acquired intangible assets; acquisition and transaction-related charges included in general and administrative expenses; restructuring and other charges and credits, net; non-operating charges and credits shown in the reconciliation provided; and income tax adjustments. Additional information about the items we exclude from our non-GAAP financial measures and the reasons we exclude them can be found in “Non-GAAP Financial Measures” in our Annual Report on Form 10-K for the fiscal year ended September 30, 2024.
Free Cash Flow: We provide information on free cash flow to enable investors to assess our ability to generate cash without incurring additional external financings and to evaluate our performance against our announced long-term goals and intent to return approximately 50% of our free cash flow to shareholders via stock repurchases. Free cash flow is cash provided by (used in) operations net of capital expenditures. Free cash flow is not a measure of cash available for discretionary expenditures.
Constant Currency (CC): We present CC information to provide a framework for assessing how our underlying business performed excluding the effects of foreign currency exchange rate fluctuations. To present CC information, FY’25 and comparative prior period results for entities reporting in currencies other than United States dollars are converted into United States dollars using the foreign exchange rate as of September 30, 2024, rather than the actual exchange rates in effect during that period.
Operating Measure
ARR: ARR (Annual Run Rate) represents the annualized value of our portfolio of active subscription software, SaaS, hosting, and support contracts as of the end of the reporting period. We calculate ARR as follows:
We consider a contract to be active when the product or service contractual term commences (the “start date”) until the right to use the product or service ends (the “expiration date”). Even if the contract with the customer is executed before the start date, the contract will not count toward ARR until the customer right to receive the benefit of the products or services has commenced.For contracts that include annual values that increase over time as there are additional deliverables in subsequent periods, which we refer to as ramp contracts, we include in ARR only the annualized value of components of the contract that are considered active as of the date of the ARR calculation. We do not include the future committed increases in the contract value as of the date of the ARR calculation.As ARR includes only contracts that are active at the end of the reporting period, ARR does not reflect assumptions or estimates regarding future customer renewals or non-renewals.Active contracts are annualized by dividing the total active contract value by the contract duration in days (expiration date minus start date), then multiplying that by 365 days (or 366 days for leap years).
We believe ARR is a valuable operating measure to assess the health of a subscription business because it is aligned with the amount that we invoice the customer on an annual basis. We invoice customers annually for the current year of the contract. A customer with a one-year contract will typically be invoiced for the total value of the contract at the beginning of the contractual term, while a customer with a multi-year contract will be invoiced for each annual period at the beginning of each year of the contract.
ARR increases by the annualized value of active contracts that commence in a reporting period and decreases by the annualized value of contracts that expire in the reporting period.
As ARR is not annualized recurring revenue, it is not calculated based on recognized or unearned revenue and is not affected by variability in the timing of revenue under ASC 606, particularly for on-premises license subscriptions where a substantial portion of the total value of the contract is recognized at a point in time upon the later of when the software is made available, or the subscription term commences.
ARR should be viewed independently of recognized and unearned revenue and is not intended to be combined with, or to replace, either of those items. Investors should consider our ARR operating measure only in conjunction with our GAAP financial results.
Because ARR is independent of recognized and unearned revenue, deferred ARR should not be viewed as a measurement of revenue which will be recognized in future periods.
Forward-Looking Statements
Statements in this document that are not historic facts, including statements about our future financial and growth expectations and targets, potential stock repurchases, and the expected effect of our go-to-market realignment, are forward-looking statements that involve risks and uncertainties that could cause actual results to differ materially from those projected. These risks include: the macroeconomic and/or global manufacturing climates may not improve or may deteriorate due to, among other factors, the effects of recently imposed import tariffs and threats of additional import tariffs, volatile foreign exchange rates, high interest rates or increases in interest rates and inflation, tightening of credit standards and availability, geopolitical uncertainty, including the effects of the conflicts between Russia and Ukraine and in the Middle East, and tensions with China, any of which could cause customers to delay or reduce purchases of new software, reduce the number of subscriptions they carry, or delay payments to us, which would adversely affect ARR and/or our financial results and cash flow; our investments in our software solutions may not drive expansion of those solutions and/or generate the ARR and/or cash flow we expect if customers are slower to adopt those solutions than we expect or if they adopt competing solutions; our go-to-market realignment and other strategic initiatives to improve organizational and operational efficiency may not do so when or as we expect and may disrupt our business to a greater extent than we expect; other uses of cash or our credit facility limits could limit or preclude the return of 50% of free cash flow to shareholders via share repurchases, or could change the amount and timing of any share repurchases; and foreign exchange rates may differ materially from those we expect. In addition, our assumptions concerning our future GAAP and non-GAAP effective income tax rates are based on estimates and other factors that could change, including changes to tax laws in the U.S. and other countries and the geographic mix of our revenue, expenses, and profits. Other risks and uncertainties that could cause actual results to differ materially from those projected are detailed from time to time in reports we file with the Securities and Exchange Commission, including our most recent Annual Report on Form 10-K, Quarterly Reports on Form 10-Q, and other filings with the U.S. Securities and Exchange Commission.
About PTC (NASDAQ: PTC)
PTC (NASDAQ: PTC) is a global software company that enables industrial and manufacturing companies to digitally transform how they engineer, manufacture, and service the physical products that the world relies on. Headquartered in Boston, Massachusetts, PTC employs over 7,000 people and supports more than 30,000 customers globally. For more information, please visit www.ptc.com.
PTC Investor Relations Contact
Matt Shimao
SVP, Investor Relations
mshimao@ptc.com
investor@ptc.com
PTC Inc.
UNAUDITED CONSOLIDATED STATEMENTS OF INCOME
(in thousands, except per share data)
Three Months Ended
December 31,
December 31,
2024
2023
Revenue:
Recurring revenue
$
524,311
$
506,027
Perpetual license
9,405
8,440
Professional services
31,412
35,747
Total revenue (1)
565,128
550,214
Cost of revenue (2)
111,797
110,020
Gross margin
453,331
440,194
Operating expenses:
Sales and marketing (2)
157,532
136,924
Research and development (2)
115,516
105,783
General and administrative (2)
53,319
69,206
Amortization of acquired intangible assets
11,440
10,363
Restructuring and other credits, net
–
(795)
Total operating expenses
337,807
321,481
Operating income
115,524
118,713
Other expense, net
(22,370)
(33,114)
Income before income taxes
93,154
85,599
Provision (benefit) for income taxes
10,922
19,212
Net income
$
82,232
$
66,387
Earnings per share:
Basic
$
0.68
$
0.56
Weighted average shares outstanding
120,243
119,124
Diluted
$
0.68
$
0.55
Weighted average shares outstanding
121,145
120,250
(1) See supplemental financial data for revenue by license, support and cloud services, and professional services.
(2) See supplemental financial data for additional information about stock-based compensation.
PTC Inc.
SUPPLEMENTAL FINANCIAL DATA FOR REVENUE AND STOCK-BASED COMPENSATION
(in thousands, except per share data)
Revenue by license, support and services is as follows:
Three Months Ended
December 31,
December 31,
2024
2023
License revenue (1)
$
172,754
$
183,998
Support and cloud services revenue
360,962
330,469
Professional services revenue
31,412
35,747
Total revenue
$
565,128
$
550,214
(1) License revenue includes the portion of subscription revenue allocated to license.
The amounts in the income statement include stock-based compensation as follows:
Three Months Ended
December 31,
December 31,
2024
2023
Cost of revenue
$
5,913
$
5,089
Sales and marketing
18,068
16,127
Research and development
16,155
14,238
General and administrative
15,715
23,559
Total stock-based compensation
$
55,851
$
59,013
PTC Inc.
NON-GAAP FINANCIAL MEASURES AND RECONCILIATIONS (UNAUDITED)
(in thousands, except per share data)
Three Months Ended
December 31,
December 31,
2024
2023
GAAP gross margin
$
453,331
$
440,194
Stock-based compensation
5,913
5,089
Amortization of acquired intangible assets included in cost of revenue
8,300
9,566
Non-GAAP gross margin
$
467,544
$
454,849
GAAP operating income
$
115,524
$
118,713
Stock-based compensation
55,851
59,013
Amortization of acquired intangible assets
19,740
19,929
Acquisition and transaction-related charges
215
2,506
Restructuring and other credits, net
–
(795)
Non-GAAP operating income (1)
$
191,330
$
199,366
GAAP net income
$
82,232
$
66,387
Stock-based compensation
55,851
59,013
Amortization of acquired intangible assets
19,740
19,929
Acquisition and transaction-related charges
215
2,506
Restructuring and other credits, net
–
(795)
Income tax adjustments (2)
(24,691)
(14,038)
Non-GAAP net income
$
133,347
$
133,002
GAAP diluted earnings per share
$
0.68
$
0.55
Stock-based compensation
0.46
0.49
Amortization of acquired intangibles
0.16
0.17
Acquisition and transaction-related charges
0.00
0.02
Restructuring and other credits, net
–
(0.01)
Income tax adjustments (2)
(0.20)
(0.12)
Non-GAAP diluted earnings per share
$
1.10
$
1.11
(1) Operating margin impact of non-GAAP adjustments:
Three Months Ended
December 31,
December 31,
2024
2023
GAAP operating margin
20.4
%
21.6
%
Stock-based compensation
9.9
%
10.7
%
Amortization of acquired intangibles
3.5
%
3.6
%
Acquisition and transaction-related charges
0.0
%
0.5
%
Restructuring and other credits, net
0.0
%
(0.1)
%
Non-GAAP operating margin
33.9
%
36.2
%
(2) Income tax adjustments reflect the tax effects of non-GAAP adjustments which are calculated by applying the applicable tax rate by jurisdiction to the non-GAAP adjustments listed above. Additionally, adjustments exclude a $5.4 million benefit in Q1’25 and $3.6 million charge in Q1’24 related to the non-cash tax impact of tax reserves related to prior years in foreign jurisdictions.
PTC Inc.
UNAUDITED CONDENSED CONSOLIDATED BALANCE SHEETS
(in thousands)
December 31,
September 30,
2024
2024
ASSETS
Cash and cash equivalents
$
196,338
$
265,808
Accounts receivable, net
694,807
861,953
Property and equipment, net
71,069
75,187
Goodwill and acquired intangible assets, net
4,295,528
4,359,367
Lease assets, net
128,357
133,317
Other assets
689,265
687,910
Total assets
$
6,075,364
$
6,383,542
LIABILITIES AND STOCKHOLDERS’ EQUITY
Deferred revenue
$
726,167
$
775,274
Debt, net of deferred issuance costs
1,543,991
1,748,572
Lease obligations
175,890
181,754
Other liabilities
399,495
463,544
Stockholders’ equity
3,229,821
3,214,398
Total liabilities and stockholders’ equity
$
6,075,364
$
6,383,542
PTC Inc.
UNAUDITED CONDENSED CONSOLIDATED STATEMENTS OF CASH FLOWS
(in thousands)
Three Months Ended
December 31,
December 31,
2024
2023
Cash flows from operating activities:
Net income
$
82,232
$
66,387
Stock-based compensation
55,851
59,013
Depreciation and amortization
25,823
27,222
Amortization of right-of-use lease assets
7,928
7,724
Operating lease liability
(3,850)
(4,953)
Accounts receivable
131,353
153,950
Accounts payable and accruals
(15,336)
(64,687)
Deferred revenue
(27,810)
(29,094)
Income taxes
(13,528)
13,467
Other
(4,234)
(41,688)
Net cash provided by operating activities
238,429
187,341
Capital expenditures
(2,767)
(4,563)
Acquisition of businesses, net of cash acquired(1)
–
(93,457)
Borrowings (payments) on debt, net(2)
(205,125)
558,404
Repurchases of common stock
(75,000)
–
Deferred acquisition payment(3)
–
(620,040)
Payments of withholding taxes in connection with vesting of stock-based awards
(42,789)
(50,326)
Settlement of net investment hedges
28,308
(7,347)
Other financing & investing activities
(1,410)
–
Foreign exchange impact on cash
(9,201)
6,689
Net change in cash, cash equivalents, and restricted cash
(69,555)
(23,299)
Cash, cash equivalents, and restricted cash, beginning of period
266,466
288,798
Cash, cash equivalents, and restricted cash, end of period
$
196,911
$
265,499
Supplemental cash flow information:
Cash paid for interest(3)
$
15,398
$
44,757
(1) In Q1’24, we acquired pure-systems for $93 million, net of cash acquired.
(2) In Q1’24, we borrowed $740 million to fund the ServiceMax deferred acquisition payment and the pure-systems acquisition and made $181 million in payments on our debt.
(3) In Q1’24, we made a payment of $650 million to settle the ServiceMax deferred acquisition payment liability, of which $620 million is a financing outflow and $30 million is an operating outflow and included in cash paid for interest.
PTC Inc.
NON-GAAP FINANCIAL MEASURES AND RECONCILIATIONS (UNAUDITED)
(in thousands)
Three Months Ended
December 31,
December 31,
2024
2023
Cash provided by operating activities
$
238,429
$
187,341
Capital expenditures
(2,767)
(4,563)
Free cash flow
$
235,662
$
182,778
View original content to download multimedia:https://www.prnewswire.com/news-releases/ptc-announces-first-fiscal-quarter-2025-results-302369330.html
SOURCE PTC Inc.

You may like

BEIJING, Oct. 18, 2026 /PRNewswire/ — An interview from China.org.cn with Wang Xiaohui and David Ferguson on the Long March:
Wang Xiaohui:
When you march toward your ideals but encounter repeated setbacks and failures, do you have the courage to pause, reflect on the path taken, and chart a new way forward?
David Ferguson:
If I continually encountered setbacks on the road to my ideals, I would stop and reflect seriously on whether my methods need adjusted or my direction needs corrected. This is a matter of being honest with oneself and honest about one’s shortcomings. Granted, this requires as much courage as setting out in the first place — because what you have to confront is not only the judgment of others, but your own ingrained reluctance to accept that you might have got it wrong.
Wang Xiaohui:
The waters of the Xiangjiang River ran crimson in the winter of 1934.
To cover the Red Army’s main force as they crossed the river, Chen Shuxiang, then Commander of the 34th Division of the Fifth Army Corps, led his troops to fight against vastly superior enemy forces until they ran out of ammunition and supplies. Severely wounded, Chen was captured alive. On the way to the enemy camp to be paraded for merit, Chen seized a moment of the enemy’s unawareness, tore his own intestines through his abdominal wound, and died a heroic death. He was only 29 years old.
The Battle of Xiangjiang River was the deadliest campaign for the Red Army since the start of the Long March. In less than two months, their troop strength plummeted from over 86,000 to just over 30,000.
At that critical moment, doubts and discontent among officers and soldiers with the military leadership peaked.
During the fights against the previous four Kuomintang (KMT) “encirclement” campaigns, the Red Army adopted Mao Zedong’s strategy of “luring the enemy in deep.” With flexible tactics in mobile warfare, the Red Army worked miracles of defeating superior enemies time and again. Yet, the tide turned completely during the KMT’s fifth “encirclement.”
At that time, the CPC was a branch of the Communist International (Comintern). After 1927, the Comintern instructed the CPC to adopt an urban-centered path in its revolution, for it was how Russia’s October Revolution had achieved victory. Affected by this directive, during the Fifth Counter-Campaign against “Encirclement and Suppression”, Bo Gu and Otto Braun, who held actual command of the Red Army, insisted on launching offensive operations to seize major cities.
Otto Braun also mechanically applied European conventional warfare tactics, forcing the Red Army into rigid positional and fortress battles. In the Battle of Guangchang, the poorly equipped Red Army fought head-on against enemy tanks and artillery on open terrain, resulting in more than 5,000 casualties, about one-fourth of all participating troops.
Successive military defeats forced the Red Army to launch a strategic shift. However, Bo Gu and Otto Braun insisted that everything be evacuated, including heavy equipment: printing presses, currency-making machines, and arms-manufacturing facilities… When crossing the Xiangjiang River, troops were slowed down by these cumbersome supplies, and numerous soldiers even laid down their lives for protecting these assets. Chen Shuxiang and his 34th Division wrote the gravest footnote to this bloody sacrifice.
By the banks of the Xiangjiang River, the spark of hope in the eyes of the Red Army soldiers was nearly quenched by the cold water. Could the rigid foreign doctrines truly guide the Red Army and China’s revolution? What path lay ahead?
History often unfolds in paradoxes: when all hope seems lost, a historical turning point is quietly emerging.
After the Battle of Xiangjiang River, Mao firmly opposed the original plan drafted by Bo Gu and Otto Braun to march towards Hunan. Instead, he proposed to advance to Guizhou where enemy defenses were weak. There, the Red Army broke through the natural barrier of the Wujiang River, and captured Zunyi. On Jan. 15, 1935, the CPC Central Committee convened an enlarged Political Bureau meeting in an old mansion, later known to the world as the Zunyi Conference.
Inside the modest living room on the second floor, a charcoal brazier expelled the winter chill. The CPC leadership sat around a long table to review why the Red Army had fallen into passive positions since 1933. Bo Gu attributed the defeats solely to the enemy’s overwhelming strength, while other leading officials like Zhou Enlai and Zhang Wentian pinpointed flawed military command as the fundamental cause.
Mao Zedong also made a pivotal speech.
As a revolutionary forged in rural base-area practice, Mao always sought truth from real combat experience. Citing victories from the previous four counter-“encirclement” campaigns, he rebutted Bo Gu’s opinions and criticized the flawed strategies of passive defense and abandoning mobile warfare tactics. In plain, incisive language, he pointed out that “the soldiers also needed to march, eat and sleep,” and that Braun’s rigid commands were completely divorced from the realities of China’s revolutionary warfare.
Throughout the whole meeting, Bo Gu remained dejected; Braun sat near the door and lit one cigarette after another. Never had these “true Bolsheviks” faced such rigorous criticism before.
The intensive confrontation lasted three days. In the end, Mao Zedong was elected to the leadership of the Red Army and the CPC Central Committee, putting an end to the wrong guidance. This marked a life-and-death turning point in the history of the Communist Party of China.
The Zunyi Conference freed the CPC from the Comintern’s intervention, enabling the Party to independently master the destiny of China’s revolution. From then on, the Red Army turned peril into safety, and China’s revolution emerged from despair toward new life.
David Ferguson:
When faced with major setbacks, the Communist Party of China was not crushed; instead, it demonstrated the courage to confront and correct its own mistakes, thereby turning adversity into opportunity. For any ruling party, this kind of courage is exceptionally rare.
Throughout history, guided by the principle of seeking truth from facts, the Party has always corrected errors, updated systems and adjusted course. By doing so, it has guaranteed social progress. This is precisely the secret to success that has made the Party resilient and invincible.
Wang Xiaohui:
No grand undertaking advances without setbacks. Faced with obstacles and defeats, the CPC demonstrated extraordinary courage and wisdom. They sought truth from facts, corrected wrong courses, and led the revolution towards triumph.
The Zunyi Conference Spirit, embodied in firm conviction, adherence to truth, independence and self-reliance, solidarity and unity, was forged amid blood and fire. It has shaped the unique spiritual character of the CPC. In the years that followed, these timeless values continued to evolve and sustain the Party in the face of trials and challenges, endowing it with enduring vitality.
China Mosaic
http://www.china.org.cn/video/node_7230027.htm
Faith: The Spark Born by the Yudu Riverside
http://www.china.org.cn/2026-10/17/content_118737624.shtml
View original content to download multimedia:https://www.prnewswire.com/news-releases/truth-seeking-the-turning-point-in-zunyi-302912139.html
SOURCE China.org.cn
Technology
GMIF2026: AI Inference Powers the “Token Factory” and Drives System-Level Rethinking of Memory & Storage
Published
2 minutes agoon
October 19, 2026By
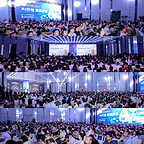
SHENZHEN, China, Oct. 18, 2026 /PRNewswire/ — The 5th GMIF Innovation Summit (Global Memory Innovation Forum 2026, GMIF2026) recently concluded at the Renaissance Shenzhen Bay Hotel. Co-hosted by the Shenzhen Memory Industry Association (SMIA) and the School of Integrated Circuits at Peking University, the summit was themed “The Future Built on AI Memory and Storage.” Now in its fifth edition, GMIF has grown from a regional industry gathering into a benchmark for the global semiconductor memory ecosystem, with diversified programs including keynote sessions, an investment forum, product exhibitions, a global livestream, and a golf friendship match, all centered on the value of memory and storage in the token economy and the AI inference era.
In the opening remarks by Rixin Sun, President of Shenzhen Memory Industry Association (SMIA), GMIF’s growth over five consecutive editions was traced from its early days to today. As a platform for global exchange, GMIF is built around the memory value chain, linking wafer IDMs and players in controllers, modules, packaging and testing, equipment and materials, and end applications to promote technical exchange, supply-demand matching, and ecosystem cooperation.
President Sun noted that as AI evolves from generative to agentic, inference efficiency, data scheduling, and system coordination have become shared priorities. Collaboration across the value chain is no longer a traditional supply-demand relationship, but a deeper partnership built around workload requirements, joint product definition, and scenario validation. Looking ahead, GMIF will pursue a more specialized and differentiated format, connecting memory companies with AI compute and end-application players worldwide.
Capital Meets Technology: Memory & Storage Moves to the Center of AI Infrastructure
As AI shifts from model training to large-scale commercial inference, the token is becoming a new unit of value. Inference demands low latency, high concurrency, and sustained throughput, which places memory and storage bandwidth, capacity, and energy efficiency among the variables that shape overall system efficiency and cost.
Daniel Yen of Morgan Stanley projected that global data center capital expenditure will stay strong in the coming years, with more than half of cloud data center capex expected to go to memory & storage (excluding HBM) by 2027. Yen identified six innovation paths to overcome the “memory wall” challenge: process migration, design changes, advanced packaging, memory peripherals, PIM/CIM, and new materials.
Prof. Yimao Cai, Dean of the School of Integrated Circuits at Peking University, pointed out that HBM remains central to high-end AI compute, but yield, cost, and thermal constraints limit broader adoption. NAND-based high-bandwidth technologies such as HBF have become a major research focus because of their cost advantage, and hybrid multi-media architectures could balance performance, capacity, and cost for deploying models with hundreds of billions of parameters.
Kevin Yoon, CVP & CTO of Samsung Memory China at Samsung Electronics, described how agents are generating massive KV cache demand and driving rapid iteration of tiered storage, citing Samsung’s work on Z-NAND, PCIe Gen6 SSDs, and ultra-high-capacity data center SSDs. Maya Zhang, Senior Director of Product Marketing from Sandisk, called this the first year of the “inference boom.” As inference reaches commercial scale, AI data centers are shifting from cost centers to value and capacity centers, and the evaluation framework is moving from TCO to TVO. NAND is becoming a strategic core component of AI, and the SSD is becoming a “token battery” that greatly improves the economics of the industry through token reuse.
Solidigm and Arm focused on the evolution of system-level design. Benny Ni, GAR Sales VP at Solidigm, noted high-capacity QLC SSDs are being adopted faster, and that memory offloading has moved from an alternative to a core design paradigm for data centers, while liquid cooling has become a prerequisite for unlocking high-end storage performance. John Xavier Lionel, Head of Global Storage Business at Arm, shared competition in the AI era is shifting from simply chasing higher TOPS to building a more efficient system balance among compute, memory, storage, and data movement. Arm’s cloud-edge-device continuum framework balances power, capacity, bandwidth, latency, security, and cost constraints at each tier, so that “the right AI workload runs in the right place.”
Moving from the cloud to the edge, Stanley Huang, AVP of Silicon Motion, stressed that devices are the ultimate carrier of AI experiences and that intelligent storage directly determines real-world device performance. Its PerformaShape technology allocates resources flexibly across different agents and greatly improves read/write consistency.
Sam Sun, Chairman of BIWIN, explained that large-scale AI inference is extending memory demand from data centers to the edge and endpoints, where differing needs in capacity, performance, power, size, and reliability are pushing storage from general-purpose specifications toward deep matching with specific scenarios and platforms. Drawing on full-stack capabilities from media selection and controller and firmware development to advanced packaging, testing, and volume delivery, BIWIN works closely with customers, platforms, and chip makers to tailor products to each use case, shortening development and validation cycles and improving system space, energy efficiency, and performance.
Token Factories Move Enterprise AI from Pilot to Production
As the token becomes the core unit of value, producing tokens efficiently and at low cost has become a shared challenge for enterprise AI adoption worldwide, and the “token factory” is emerging as a new industry paradigm. Tao Zhou, General Manager of the Server Division of Lenovo ISG China, said 80% of enterprises have deployed at least one type of agent, yet fewer than 40% of projects can scale and deliver positive ROI. Lenovo has built a full-stack “token factory” paradigm spanning data governance, compute optimization, and security management to address this.
A solid token factory depends on underlying storage media and architecture. Numbers Law’s PMD (Parallel Magnetic Drive) technology and NEXWISE‘s “KuberCloud” token factory solution contributed to full-stack capability from hardware to compute scheduling and model operations. Infplane, Maxio, and Genstoraige lowered the deployment threshold for large on-device models through AI SSD tiered offloading and memory expansion.
Real-world applications are also deepening. SYNCORE has achieved vehicle-cloud embodied intelligence across the whole vehicle. Dify, with its private agent architecture, and Paratera, with its MaaS compute service platform, are moving AI from basic compute supply toward deeper industry intelligence services, accelerating the industrialization of AI.
40 Companies Showcase the Core of the AI Memory & Storage Chain
The concurrent exhibition brought together 40 companies across the full value chain, from memory chips and controllers to compute servers, AIDC services, packaging and testing equipment, and system applications, presenting the latest advances in AI memory and storage from around the world.
Memory IDMs and controller makers led with new products. SanDisk featured its iNAND AT EU752 automotive UFS 4.1, SN861 enterprise NVMe SSD, and BiCS8 QLC NAND. Silicon Motion introduced the SM8466 PCIe Gen6 16-channel controller and the SM2524XT controller for edge SSDs. Maxio, YEESTOR, and other Chinese controller makers showed flagship PCIe Gen4/Gen5 and UFS controllers with enhanced LDPC, a sign that China’s controller portfolio is taking shape and benchmarking itself against leading international standards.
Compute and token factory solutions were another highlight. Lenovo exhibited its WenTian series of AI training-and-inference integrated servers. NEXWISE presented its full-stack token factory hardware and software, with heterogeneous compute management and token-based billing. Paratera showed its intelligent compute cloud and supercomputing cloud services, and Numbers Law demonstrated its PMD (Parallel Magnetic Drive) technology, aimed at sharply raising HDD IOPS and throughput. Infplane, Genstoraige, and Quanxing introduced KV cache offload and memory-fusion AI SSD solutions that use storage to share the compute load and significantly cut deployment costs.
Module makers and full-scenario solution providers brought a wide range of products. BIWIN exhibited enterprise SSDs, CXL products, wide-temperature industrial storage, and embedded products spanning AI cloud, edge, and device. KingSpec, POWEV, Topdisk, Barycn, Jielong Storage, HIKSEMI, and others presented industrial-grade, automotive-grade, server, and embedded product families, demonstrating strong volume production and reliable delivery.
Equipment, testing, and materials suppliers rounded out the floor. Attach Point, MICROVIEW, and Maxwell Technologies showed die attach and bonding equipment for 2.5D/3D advanced packaging. OKN Technology, Acroview Technology, Hongjingwei, and Tytantest introduced test and burn-in systems covering SSD, DRAM, and NAND that can accurately reproduce high-load AI I/O scenarios. Hemei Jingyi and Silergy brought storage IC package substrates and dedicated power management ICs. From advanced packaging equipment to test validation to core components, this supporting ecosystem lays the manufacturing foundation for volume production of AI memory and storage and for Chinese suppliers expanding overseas.
GMIF2026 Annual Awards Unveiled: Global Memory & Storage Leaders Build an Open, Collaborative Ecosystem
To recognize companies that have made outstanding contributions to the memory and storage value chain, the summit established the GMIF2026 Annual Awards, which cover memory, compute, packaging and testing equipment, test systems, and end applications across AI infrastructure, and were judged on technological innovation, industry contribution, market service, and real-world results.
Honorees, including Samsung Semiconductor, SanDisk, Solidigm, CXMT, Arm, Lenovo, Dify, Silicon Motion, Infplane, Genstoraige, Numbers Law, Paratera, SYNCORE, NEXWISE, Maxio Technology, BIWIN, Topdisk, KingSpec, POWEV, Quanxing Technology, OKN Technology, Attach Point, COMIX, Barycn, LKAUTO, Maxwell Technologies, Hemei Jingyi, Silergy, Heyan Technology, ExTripod Electronics, UNIMOS, GBAT, and Tytantest, were recognized for standout achievements in technology breakthroughs, product deployment, ecosystem building, and the industry chain.
Global Livestream and Golf Friendship Match Extend the Boundaries of Industry Cooperation
To join the global ecosystem and expand international cooperation, the summit featured a special Global Livestream by Memory Brands on LinkedIn, Facebook, and YouTube. Eight brands presented online: BIWIN, Silicon Motion, Quanxing Technology, OKN Technology, KingSpec, Maxwell Technologies, ExTripod Electronics, and Silergy. They gave overseas audiences a direct look at China’s latest advances in memory chips, advanced packaging, test systems, and other core AI infrastructure components, connecting technology standards, supply chain resources, and market demand across regions.
The momentum carried into the next day. The GMIF2026 “BIWIN Cup” golf friendship match, exclusively sponsored by BIWIN, brought senior executives from across the global memory value chain to the course. After a day of intensive discussion at the main forum, the setting was more relaxed, but the conversations among technology, capital, and markets carried on, helping speed practical cooperation across borders and sectors.
Conclusion
Across the GMIF program, one message stood out: global AI competition is moving beyond the “single-point era” of peak GPU performance into a “system-level era” that integrates storage, compute, networking, and software. In the token economy, memory and storage is shedding its auxiliary role and becoming the strategic foundation of AI inference.
This edition of GMIF brought together capital outlook, frontier technology, product innovation, real-world practice, and ecosystem collaboration, and, with the awards, livestream, and networking events, carried the conversation from ideas to product showcases, overseas exposure, and business deals. Going forward, GMIF will stay focused on the industry’s frontier issues and connect key players across the global memory value chain, promoting joint standards, technology development, and market expansion to open a new chapter for the AI memory and storage industry.
About GMIF
Global Memory Innovation Forum (GMIF) is a premier annual gathering that connects the global memory and storage community. Featuring diverse activities including keynote speeches, roundtable dialogues, supply-demand match-making, product showcases, industry rankings, awards programs, and global livestreaming, GMIF brings together key enterprises across the memory and storage chain, technical experts, terminal companies and investment institutions to exchange insights, build partnerships, and create business opportunities. Learn more about GMIF, please visit https://www.gmif.com.cn/. Follow us on LinkedIn, YouTube and Facebook.
Media Contact:
Carina Gu, wenjing.gu@gmif.com.cn
View original content to download multimedia:https://www.prnewswire.com/news-releases/gmif2026-ai-inference-powers-the-token-factory-and-drives-system-level-rethinking-of-memory–storage-302912123.html
SOURCE Shenzhen Memory Industry Association (SMIA)

Truth-seeking: the Turning Point in Zunyi
Truth-seeking: the Turning Point in Zunyi

GMIF2026: AI Inference Powers the “Token Factory” and Drives System-Level Rethinking of Memory & Storage

Send Rakhi to UK swiftly with UK Gifts Portal

Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

Nullmax and Renesas Forge Strategic Partnership to Deliver Competitive ADAS Solutions for the Global Market

Why You Should Build on #NEAR – Co-founder Illia Polosukhin at CV Labs
Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

NEAR End of Year Town Hall 2021: The Open Web World, MetaBUILD 2 Hackathon and 2021 recap
Trending
-
 Coin Market5 days ago
‘Bunker mode’ won’t protect your crypto, critics say
-
 Technology5 days ago
Solidion Technology Reaffirms Commitment to Address Growing Energy Storage Needs of AI Data Centers
-
 Technology5 days ago
TVU Networks to Showcase Connected Live Video Ecosystem at Broadcast India Show 2026
-
 Coin Market4 days ago
Organizations join forces to fight Illinois crypto tax, after 6-month pause
-
 Technology5 days ago
PEGATRON Brings AI Infrastructure from Design to Deployment at OCP Global Summit 2026
-
 Technology5 days ago
SUS ENVIRONMENT Draws International Attention for Transforming Waste-to-Energy Plants into Sustainable Urban Assets
-
 Coin Market5 days ago
Can crypto users trust the supply chain behind hardware wallets?
-
 Technology5 days ago
A $2.1 Trillion Wellness Industry Never Built a Daily Practice for Black Children. So This Atlanta Family Did.