
Technology
Verra Mobility Announces Fourth Quarter and Full Year 2024 Financial Results

Published
2 years agoon
By
Full year 2024 revenue of $879.2 millionFull year 2024 net income of $31.4 millionFull year 2024 net cash provided from operations of $223.6 millionEstablishing fiscal year 2025 guidance
MESA, Ariz., Feb. 27, 2025 /PRNewswire/ — Verra Mobility Corporation (NASDAQ: VRRM), a leading provider of smart mobility technology solutions, announced today the financial results for the fourth quarter and full year ended December 31, 2024.
“We delivered a solid fourth quarter, highlighted by strong earnings and cash flow generation,” said David Roberts, President and CEO, Verra Mobility. “Resilient fourth quarter travel demand drove continued strength in Commercial Services and increased demand for automated traffic enforcement drove solid performance in Government Solutions. Our business fundamentals are strong and intact. Travel demand appears resilient and is expected to be a source of ongoing strength for Commercial Services. We expect that our strong sales bookings in Government Solutions will drive solid revenue growth over the foreseeable future and, we expect our Parking Solutions business to exit 2025 on a strong run-rate. Based on these factors, we anticipate that our long-term outlook remains intact relative to the 2026 Revenue and Adjusted EBITDA targets that we provided at our July 2022 Investor Day.”
Fourth Quarter 2024 Financial Highlights
Revenue: Total revenue for the fourth quarter of 2024 was $221.5 million, an increase of 5% compared to $211.0 million for the fourth quarter of 2023. Service revenue growth was 4%, driven by 4% growth in our Commercial Services segment and 5% growth from our Government Solutions segment. Commercial Services revenue growth was due to increases in travel volume, product adoption and tolling activity, and the growth in Government Solutions service revenue was driven by the expansion of school bus stop arm, bus lane and maintenance programs. Parking Solutions service revenue declined by $0.7 million, or 4% compared to the fourth quarter of 2023, as increased revenue from software as a service product offerings was offset by reduction in professional services revenue related to parking management solutions.Net (loss) income and Earnings Per Share (EPS): Net loss for the fourth quarter of 2024 was $(66.7) million, or $(0.41) per share, based on 163.3 million diluted weighted average shares outstanding. Net income for the comparable 2023 period was $3.0 million, or $0.02 per share, based on 168.6 million diluted weighted average shares outstanding. The net loss for the fourth quarter of 2024 is primarily attributable to an impairment loss of $97.1 million as a result of our 2024 impairment assessment of goodwill in our Parking Solutions segment.Adjusted EPS*: Adjusted EPS for the fourth quarter of 2024 was $0.33 per share compared to $0.24 per share for the fourth quarter of 2023.Adjusted EBITDA*: Adjusted EBITDA was $102.0 million for the fourth quarter of 2024 compared to $91.3 million for the same period last year. Adjusted EBITDA margin was 46% and 43% of total revenue for 2024 and 2023, respectively.Net Cash Provided from Operations: Cash provided by operating activities increased by approximately $4.8 million from $35.7 million for the three months ended December 31, 2023 to $40.5 million for the three months ended December 31, 2024 due primarily to increased revenue, lower selling and general expenses and changes in deferred income taxes offset by changes in working capital, mainly related to accrued liabilities.Free Cash Flow*: Free Cash Flow was $21.6 million for the fourth quarter of 2024 compared to $19.2 million for the same period last year.
*Non-GAAP measure; refer to “Non-GAAP Financial Measures” further below for explanatory notes and a reconciliation to the most directly comparable GAAP measure.
We report our results of operations based on three operating segments:
Commercial Services offers automated toll and violations management and title and registration solutions to rental car companies, fleet management companies and other large fleet owners.Government Solutions delivers automated safety solutions to municipalities, school districts and government agencies, including services and technology that enable photo enforcement cameras to detect and process traffic violations related to speed, red-light, school bus and city bus lane management.Parking Solutions provides an integrated suite of parking software, transaction processing and hardware solutions to universities, municipalities, parking operators, healthcare facilities and transportation hubs in the United States and Canada.
Fourth Quarter 2024 Segment Detail
The Commercial Services segment generated total revenue of $98.7 million, a 4% increase compared to $94.5 million in the same period in 2023. Segment profit was $64.6 million, a 4% increase from $62.2 million in the prior year period. The increases in revenue and segment profit compared to the prior year period resulted from increased travel volume as well growth in revenue contributed from processing violations, titles and registrations and higher tolling activity for our fleet management customers. The segment profit margin was 65% for the fourth quarter of 2024 and 66% for the fourth quarter of 2023.The Government Solutions segment generated total revenue of $103.2 million, a 10% increase compared to $94.0 million in the same period in 2023. The increase was due to a 5% increase in recurring service revenue over the prior year quarter, primarily driven by the expansion of school bus stop arm, bus lane and maintenance programs. In addition, product revenue increased approximately $4.7 million from the prior year period. The segment profit was $34.6 million in 2024 compared to $24.1 million in the prior year period with segment profit margins of 34% for 2024 and 26% for 2023. The increase in segment profit was primarily attributable to a $3.9 million write-down of installation and service parts in the fourth quarter of 2023 that did not occur in the 2024 period as well as lower credit loss expense in the fourth quarter of 2024 as compared to the prior year period.The Parking Solutions segment generated total revenue of $19.7 million, a 13% decrease compared to $22.5 million in the same period in 2023 due to a reduction in service revenue and a decrease in one-time product sales compared to the prior year quarter. The segment profit was $2.8 million compared to $5.0 million in the prior year period with segment profit margins of 14% for 2024 and 22% for 2023. The decrease in segment profit was primarily due to lower revenue and an increase in selling and general expenses.
Full Year 2024 Financial Highlights
Revenue: Total revenue for the fiscal year 2024 was $879.2 million, an increase of 8% compared to $817.3 million for fiscal year 2023. Service revenue growth was 7%, driven by 9% growth in Commercial Services segment and 7% growth from our Government Solutions segment. Commercial Services revenue growth was due to increases in travel volume, product adoption and tolling activity, and the growth in Government Solutions service revenue was driven by the expansion of speed, maintenance and bus lane programs. Parking Solutions service revenue declined by $0.7 million, or 1% compared to fiscal year 2023, as increased revenue from software as a service product offerings was offset by reduction in professional services related to parking management solutions.Net income and Earnings Per Share (EPS): Net income for fiscal year 2024 was $31.4 million, or $0.19 per share, based on 167.7 million diluted weighted average shares outstanding. Net income for the comparable 2023 period was $57.0 million, or $0.36 per share, based on 160.0 million diluted weighted average shares outstanding. The $25.6 million decrease in net income was primarily due to the impairment to goodwill in our Parking Solutions segment recorded in fiscal year 2024, partially offset by the change in fair value of the private placement warrants liability in the prior fiscal year without a comparable amount in fiscal year 2024.Adjusted EPS*: Adjusted EPS for fiscal year 2024 was $1.23 per share compared to $1.08 per share for fiscal year 2023.Adjusted EBITDA*: Adjusted EBITDA was $401.6 million for fiscal year 2024 compared to $371.5 million for the same period last year. Adjusted EBITDA margin was 46% and 45% of total revenue for 2024 and 2023, respectively.Net Cash Provided from Operations: Cash provided by operating activities increased by approximately $17.5 million from $206.1 million for fiscal year 2023 to $223.6 million for fiscal year 2024. This was primarily from increased revenue, lower expenses from interest and change in the fair value of private placement warrants, changes in deferred income taxes and lower accounts receivables year over year partially offset by decreases in other working capital changes, mainly related to accrued liabilities.Free Cash Flow*: Free Cash Flow was $152.8 million for fiscal year 2024 compared to $149.1 million for the same period last year. Free Cash Flow for fiscal year 2024 includes an after-tax legal settlement cost of approximately $22.1 million.
Liquidity: As of December 31, 2024, cash and cash equivalents were $77.6 million, and we generated $223.6 million in net cash provided by operating activities for the year ended December 31, 2024.
Net Debt and Net Leverage*: As of December 31, 2024, Net Debt was $968.0 million and Net Leverage was 2.4x, as compared to $918.3 million and 2.5x as of December 31, 2023.
*Non-GAAP measure; refer to “Non-GAAP Financial Measures” further below for explanatory notes and a reconciliation to the most directly comparable GAAP measure.
Share Repurchases
In October 2023, our Board of Directors authorized a share repurchase program for up to an aggregate amount of $100.0 million of our outstanding shares of Class A Common Stock over an 18-month period in open market, accelerated share repurchase (“ASR”) or privately negotiated transactions. In June 2024, we entered into a share repurchase agreement with a stockholder, pursuant to which we repurchased, directly from the stockholder, 2.0 million shares of our Class A Common Stock for an aggregate purchase price of $51.5 million. During the fourth quarter of 2024, we repurchased approximately 1.5 million shares through open market transactions and paid $35.8 million. In December 2024, our Board of Directors increased the authorization to repurchase up to an additional $100 million of our shares under the existing October 2023 program, providing us with approximately $112.7 million available for repurchases. On December 11, 2024, we entered into an ASR agreement with a third-party financial institution and paid $112.7 million to receive an initial delivery of 3,821,958 shares of our Class A Common Stock. The final settlement is expected to occur in the first quarter of 2025, at which time, we expect to receive additional shares calculated using a volume-weighted average price over the term of the ASR agreement. We paid a total of $200.0 million for share repurchases during fiscal year 2024. All repurchased shares were subsequently retired.
Cancellation of the Interest Rate Swap
We exercised our option to cancel our interest rate swap agreement, effective the end of the third quarter of 2024. The interest rate swap was previously used to hedge our exposure to higher interest rates associated with the variable portion of the interest rate on our term loan.
Goodwill Impairment
We recorded a $97.1 million impairment to goodwill in our Parking Solutions segment during fiscal year 2024, which is presented in a separate line item on the consolidated statements of operations. This impairment was in connection with our 2024 assessment of goodwill where the Parking Solutions reporting unit’s carrying value exceeded the estimated fair value.
Term Loan Refinancing
In February 2024, we entered into a third amendment and in October 2024, a fourth amendment to refinance our term loan. Pursuant to these amendments, the interest rate on the term loan was reduced by an aggregate 1.00% to Secured Overnight Financing Rate (“SOFR”) plus 2.25% from SOFR plus 3.25% with the SOFR floor unchanged at 0.00%. The credit spread adjustment in the term loan, ranging from approximately 0.1% to 0.7%, was eliminated. In addition, the term loan agreement was amended to no longer require the repayment of principal in quarterly installments, with principal now required to be repaid at maturity in fiscal year 2028.
2025 Full Year Guidance
Any guidance that we provide is subject to change as a variety of factors can affect actual operating results. Certain of the factors that may impact our actual operating results are identified below in the safe harbor language included within Forward-Looking Statements of this press release.
We are providing the following forward-looking guidance, which includes Adjusted EBITDA, Adjusted EPS, Free Cash Flow, and Net Leverage, all of which are non-GAAP financial measures (defined below):
Total Revenue of $925 million to $935 millionAdjusted EBITDA of $410 million to $420 millionAdjusted EPS of $1.30 to $1.35Free Cash Flow of $175 million to $185 millionNet Leverage of approximately 2.0x
Underlying Assumptions for 2025 Full Year Guidance
Weighted average fully diluted share count expected to be approximately 163 million shares for the full year 2025Effective tax rate (including state taxes) is expected to be 28.5% to 29.5%, with approximately $65 million in total cash taxes expected to be paid in 2025. The effective tax rate for Non-GAAP adjustments is provided in the Reconciliation of Net (Loss) Income to Adjusted Net Income and Calculation of Adjusted EPSDepreciation and amortization expense expected to be approximately $110 million for 2025Total interest expense, net expected to be approximately $70 million, of which approximately $65 million is expected to be net cash interest paidChange in working capital (change in operating assets and liabilities) is expected to result in a use of cash of approximately $15 million for 2025Capital expenditures (purchases of installation and service parts and property and equipment) are expected to be approximately $90 million for 2025
Conference Call Details
Date: February 27, 2025
Time: 5:00 p.m. Eastern Time
To access this conference call by telephone, register here to receive dial-in numbers and a unique PIN to join the call.
Webcast Information: Available live in the “Investor Relations” section of our website at http://ir.verramobility.com.
A replay of the call will also be made available on the Investor Relations website. A copy of the earnings call presentation will be posted to our website.
About Verra Mobility
Verra Mobility is a leading provider of smart mobility technology solutions that make transportation safer, smarter and more connected. We sit at the center of the mobility ecosystem, bringing together vehicles, hardware, software, data and people to enable safe, efficient solutions for customers globally. Our transportation safety systems and parking management solutions protect lives, improve urban and motorway mobility and support healthier communities. We also solve complex payment, utilization and compliance challenges for fleet owners and rental car companies. We are headquartered in Arizona, and operate in North America, Europe, Asia and Australia. For more information, please visit www.verramobility.com.
Forward-Looking Statements
This press release contains forward-looking statements which address our expected future business and financial performance, and may contain words such as “goal,” “target,” “future,” “estimate,” “expect,” “anticipate,” “intend,” “plan,” “believe,” “seek,” “project,” “may,” “should,” “will” or similar expressions. Forward-looking statements include statements regarding changes and trends in the market for our products and services, including expected resilience of travel demand and impact on our Commercial Services segment, expected strong sales bookings in our Government Solutions segment and a strong run-rate in our Parking Solutions segment, expected operating results and metrics, such as revenue growth, expansion plans and opportunities, 2025 full year guidance, including expected total revenue, Adjusted EBITDA, Adjusted EPS, Free Cash Flow and Net Leverage, the underlying assumptions for the 2025 full year guidance, including expected weighted average fully-diluted share count, effective tax rate and cash taxes, expected depreciation and amortization, expected interest expense, net and total net cash interest, expected change in working capital and expected capital expenditures, and our ability to meet our long-term outlook, including 2026 revenue and Adjusted EBITDA targets. Forward-looking statements involve risks and uncertainties and a number of factors could cause actual results to differ materially from those currently anticipated. These factors include, but are not limited to, the impact of negative industry and macroeconomic conditions on our customers or the Company; customer concentration in our Commercial Services and Government Solutions segments including risks impacting such segments, including travel demand and legislation; risks related to our contract with the New York City Department of Transportation, which comprises a material portion of our revenue and was extended through December 31, 2025, including risks related to winning the competitive procurement process for a new contract or if we win the competitive procurement at materially different terms and pricing as our current contract; our reliance on specialized third-party providers; risks and uncertainties related to our government contracts, including legislative changes, termination rights, delays in payments, audits and investigations; decreases in the prevalence or political acceptance of, or an increase in governmental restrictions regarding, automated and other similar methods of photo enforcement, parking solutions or the use of tolling; our ability to successfully implement our acquisition strategy or integrate acquisitions; failure in or breaches of our networks or systems, including as a result of cyber-attacks or other incidents; risks and uncertainties related to our international operations/our ability to develop and successfully market new products and technologies into new markets; our failure to acquire necessary intellectual property or adequately protect our intellectual property; our ability to manage our substantial level of indebtedness; our ability to maintain an effective system of internal controls; our ability to properly perform under our contracts and otherwise satisfy our customers; decreased interest in outsourcing from our customers; our ability to keep up with technological developments and changing customer preferences; our ability to compete in a highly competitive and rapidly evolving market; risks and uncertainties related to our share repurchase program; risks and uncertainties related to litigation, disputes and regulatory investigations; our reliance on specialized third-party vendors and service providers; and other risks and uncertainties indicated from time to time in documents we filed or will file with the Securities and Exchange Commission (the “SEC”). In addition, no assurance can be given that any plan, initiative, projection, goal, commitment, expectation, or prospect set forth in this release can or will be achieved. This press release should be read in conjunction with the information included in our other press releases, reports and other filings with the SEC. Additional information regarding the factors that may cause actual results to differ materially from these forward-looking statements is available in our SEC filings, including our 2024 Annual Report on Form 10-K. These forward-looking statements speak only as of the date of this release and except to the extent required by applicable law, we do not assume any obligation to update or revise any forward-looking statement, whether as a result of new information, future events and developments or otherwise. Understanding the information contained in these filings is important in order to fully understand our reported financial results and our business outlook for future periods.
Additional Information
We periodically provide information for investors on our corporate website, www.verramobility.com, and our investor relations website, ir.verramobility.com.
We intend to use our website including our quarterly earnings presentation as a means of disclosing material non-public information, additional financial and operating metrics and for complying with disclosure obligations under Regulation FD. Accordingly, investors should monitor our website, in addition to following our press releases, SEC filings and public conference calls and webcasts.
Non-GAAP Financial Measures
In addition to disclosing financial results that are determined in accordance with U.S. generally accepted accounting principles (“GAAP”), we also disclose certain non-GAAP financial information in this press release. These financial measures are not recognized measures under GAAP and are not intended to be, and should not be, considered in isolation or as a substitute for, or superior to, the financial information prepared and presented in accordance with GAAP. EBITDA, Adjusted EBITDA, Free Cash Flow, Adjusted Net Income, Adjusted EPS, Adjusted EBITDA Margin, Net Debt, and Net Leverage are non-GAAP financial measures as defined by SEC rules. These non-GAAP financial measures may be determined or calculated differently by other companies. As a result, they may not be comparable to similarly titled performance measures presented by other companies. Reconciliations of these non-GAAP measurements to the most directly comparable GAAP financial measurements have been provided in the financial statement tables included in this press release, and investors are encouraged to review the reconciliations.
We are not providing a quantitative reconciliation of Adjusted EBITDA, Adjusted EPS, Free Cash Flow or Net Leverage which are included in our 2025 financial guidance above, in reliance on the “unreasonable efforts” exception for forward-looking non-GAAP measures set forth in SEC rules because certain financial information, the probable significance of which cannot be determined, is not available and cannot be reasonably estimated without unreasonable effort and expense. In this regard, we are unable to provide a reconciliation of forward-looking Adjusted EBITDA to GAAP net (loss) income, Adjusted EPS to net (loss) income per share, Free Cash Flow to net cash provided by operating activities and Net Leverage, due to the inherent difficulty in forecasting and quantifying certain amounts that are necessary for such reconciliation. Due to the uncertainty of estimates and assumptions used in preparing forward-looking non-GAAP measures, we caution investors that actual results could differ materially from these non-GAAP financial projections.
We use the non-GAAP metrics EBITDA, Adjusted EBITDA, Free Cash Flow, Adjusted Net Income, Adjusted EPS, Adjusted EBITDA Margin to measure our performance from period to period, to evaluate and fund incentive compensation programs and to compare our results to those of our competitors. We use the non-GAAP metrics Free Cash Flow in connection with managing the business and we use the non-GAAP metrics “Net Debt” and “Net Leverage” to understand our overall leverage position and to evaluate capital allocation decisions. In addition, we also believe that these non-GAAP measures provide useful information to investors regarding financial and business trends related to our results of operations and that when non-GAAP financial information is viewed with GAAP financial information, investors are provided with a more meaningful understanding of our ongoing operating performance, liquidity and leverage relative to other periods. These non-GAAP measures have certain limitations as analytical tools and should not be used as substitutes for net (loss) income, cash flows from operations, earnings per share, other consolidated income, cash flow or debt data prepared in accordance with GAAP.
EBITDA and Adjusted EBITDA
We define “EBITDA” as net (loss) income adjusted to exclude interest expense, net, income taxes, depreciation and amortization. “Adjusted EBITDA” further excludes certain non-cash expenses and non-recurring items.
Free Cash Flow
We define “Free Cash Flow” as net cash flow provided by operating activities less purchases of installation and service parts and property and equipment.
Adjusted Net Income
We define “Adjusted Net Income” as net (loss) income adjusted to exclude amortization of intangibles and certain non-cash or non-recurring expenses such as change in fair value of private placement warrants, change in fair value of interest rate swap, loss on extinguishment of debt, among other items.
Adjusted EPS
We define “Adjusted EPS” as Adjusted Net Income divided by the diluted weighted average shares for the period.
Adjusted EBITDA Margin
We define “Adjusted EBITDA Margin” as Adjusted EBITDA as a percentage of total revenue.
Net Debt
We define “Net Debt” as total long-term debt (including current portion of long-term debt) excluding original issue discounts and unamortized deferred financing costs, less cash and cash equivalents.
Net Leverage
We define “Net Leverage” as Net Debt divided by the trailing twelve months Adjusted EBITDA as of the current quarter-end.
Additional Metrics
Recurring Revenue or Recurring Service Revenue
We define “Recurring Revenue” or “Recurring Service Revenue” as all revenue other than product sales for each of our segments, as we typically generate revenue on a recurring monthly basis under long-term contracts with our customers. This includes our Commercial Services segment where we generate service revenue through processing of tolls, violations, and titles and registrations.
VERRA MOBILITY CORPORATION
CONDENSED CONSOLIDATED BALANCE SHEETS
(Unaudited)
December 31,
(In thousands, except per share data)
2024
2023
Assets
Current assets:
Cash and cash equivalents
$
77,560
$
136,309
Restricted cash
3,594
3,413
Accounts receivable (net of allowance for credit losses of $17.0 million and $18.5
million at December 31, 2024 and 2023, respectively)
206,503
197,824
Unbilled receivables
48,193
37,065
Inventory
15,502
17,966
Prepaid expenses and other current assets
42,647
46,961
Total current assets
393,999
439,538
Installation and service parts, net
36,631
22,895
Property and equipment, net
141,601
123,248
Operating lease assets
29,895
33,523
Intangible assets, net
232,297
301,025
Goodwill
735,615
835,835
Other non-current assets
44,451
33,919
Total assets
$
1,614,489
$
1,789,983
Liabilities and Stockholders’ Equity
Current liabilities:
Accounts payable
$
91,224
$
78,749
Deferred revenue
29,374
28,788
Accrued liabilities
73,980
93,119
Tax receivable agreement liability, current portion
5,163
5,098
Current portion of long-term debt
—
9,019
Total current liabilities
199,741
214,773
Long-term debt, net of current portion
1,034,211
1,029,113
Operating lease liabilities, net of current portion
25,757
29,124
Tax receivable agreement liability, net of current portion
42,977
48,369
Asset retirement obligations
15,493
14,580
Deferred tax liabilities, net
14,699
18,360
Other long-term liabilities
16,486
14,197
Total liabilities
1,349,364
1,368,516
Commitments and contingencies
Stockholders’ equity
Preferred stock, $0.0001 par value
—
—
Common stock, $0.0001 par value
16
17
Additional paid-in capital
551,955
557,513
Accumulated deficit
(269,287)
(125,887)
Accumulated other comprehensive loss
(17,559)
(10,176)
Total stockholders’ equity
265,125
421,467
Total liabilities and stockholders’ equity
$
1,614,489
$
1,789,983
VERRA MOBILITY CORPORATION
CONDENSED CONSOLIDATED STATEMENTS OF OPERATIONS
AND COMPREHENSIVE (LOSS) INCOME
(Unaudited)
Three Months Ended December 31,
Year Ended December 31,
(In thousands, except per share data)
2024
2023
2024
2023
Service revenue
$
209,671
$
201,818
$
841,676
$
783,595
Product sales
11,829
9,195
37,531
33,715
Total revenue
221,500
211,013
879,207
817,310
Cost of service revenue, excluding depreciation and
amortization
4,664
4,514
18,988
18,232
Cost of product sales
8,303
7,022
27,058
25,231
Operating expenses
74,368
76,915
295,937
273,288
Selling, general and administrative expenses
52,622
73,056
195,054
198,550
Depreciation, amortization and (gain) loss on disposal of
assets, net
27,857
26,177
109,072
113,195
Goodwill impairment
97,076
—
97,076
—
Total costs and expenses
264,890
187,684
743,185
628,496
(Loss) income from operations
(43,390)
23,329
136,022
188,814
Interest expense, net
16,699
20,859
73,902
86,701
Change in fair value of private placement warrants
—
—
—
24,966
Tax receivable agreement liability adjustment
(257)
(3,077)
(257)
(3,077)
Loss on interest rate swap
—
2,764
494
817
Loss on extinguishment of debt
1,117
—
1,745
3,533
Other income, net
(5,000)
1,643
(18,970)
(11,123)
Total other expenses
12,559
22,189
56,914
101,817
(Loss) income before income taxes
(55,949)
1,140
79,108
86,997
Income tax provision (benefit)
10,707
(1,882)
47,660
29,982
Net (loss) income
$
(66,656)
$
3,022
$
31,448
$
57,015
Other comprehensive (loss) income:
Change in foreign currency translation adjustment
(10,747)
6,250
(7,383)
2,689
Total comprehensive (loss) income
$
(77,403)
$
9,272
$
24,065
$
59,704
Net (loss) income per share:
Basic
$
(0.41)
$
0.02
$
0.19
$
0.36
Diluted
$
(0.41)
$
0.02
$
0.19
$
0.36
Weighted average shares outstanding:
Basic
163,342
166,437
165,090
158,777
Diluted
163,342
168,585
167,717
160,017
VERRA MOBILITY CORPORATION
CONDENSED CONSOLIDATED STATEMENTS OF CASH FLOWS
(Unaudited)
Three Months Ended December 31,
($ in thousands)
2024
2023
Cash Flows from Operating Activities:
Net (loss) income
$
(66,656)
$
3,022
Adjustments to reconcile net (loss) income to net cash provided by operating activities:
Depreciation and amortization
27,543
26,232
Amortization of deferred financing costs and discounts
669
1,079
Tax receivable agreement liability adjustment
(257)
(3,077)
Change in fair value of interest rate swap
—
3,041
Loss on extinguishment of debt
1,117
—
Credit loss expense
1,577
1,501
Deferred income taxes
(8,328)
(19,801)
Stock-based compensation
4,372
5,130
Goodwill impairment
97,076
—
Impairment of long-lived assets and ROU assets
170
4,280
Other
654
53
Changes in operating assets and liabilities:
Accounts receivable
(14,773)
(6,605)
Unbilled receivables
1,925
3,277
Inventory
1,406
2,209
Prepaid expenses and other assets
9,349
(5,109)
Deferred revenue
(170)
(5,875)
Accounts payable and other current liabilities
(9,825)
23,453
Other liabilities
(5,362)
2,920
Net cash provided by operating activities
40,487
35,730
Cash Flows from Investing Activities:
Cash receipts for interest rate swap
—
277
Purchase of intellectual property
—
(500)
Purchases of installation and service parts and property and equipment
(18,847)
(16,484)
Cash proceeds from the sale of assets
158
110
Net cash used in investing activities
(18,689)
(16,597)
Cash Flows from Financing Activities:
Borrowings on long-term debt
36,591
—
Repayment of long-term debt
(41,101)
(2,255)
Payment of debt issuance costs
(276)
(97)
Share repurchases and retirement
(148,479)
—
Proceeds from exercise of stock options
1,587
3,074
Payment of employee tax withholding related to RSUs and PSUs vesting
(175)
(65)
Net cash (used in) provided by financing activities
(151,853)
657
Effect of exchange rate changes on cash and cash equivalents
(2,004)
1,602
Net (decrease) increase in cash, cash equivalents and restricted cash
(132,059)
21,392
Cash, cash equivalents and restricted cash – beginning of period
213,213
118,330
Cash, cash equivalents and restricted cash – end of period
$
81,154
$
139,722
VERRA MOBILITY CORPORATION
CONDENSED CONSOLIDATED STATEMENTS OF CASH FLOWS
(Unaudited)
For the Year Ended December 31,
($ in thousands)
2024
2023
Cash Flows from Operating Activities:
Net income
$
31,448
$
57,015
Adjustments to reconcile net income to net cash provided by operating activities:
Depreciation and amortization
108,525
113,067
Amortization of deferred financing costs and discounts
4,106
4,679
Change in fair value of private placement warrants
—
24,966
Tax receivable agreement liability adjustment
(257)
(3,077)
Change in fair value of interest rate swap
1,316
(320)
Loss on extinguishment of debt
1,745
3,533
Credit loss expense
13,002
9,054
Deferred income taxes
(10,012)
(27,037)
Stock-based compensation
22,958
17,476
Goodwill impairment
97,076
—
Impairment of long-lived assets and ROU assets
170
4,280
Other
1,403
359
Changes in operating assets and liabilities:
Accounts receivable
(22,664)
(42,459)
Unbilled receivables
(11,987)
(6,252)
Inventory
1,917
1,148
Prepaid expenses and other assets
5,926
(2,161)
Deferred revenue
1,231
(2,400)
Accounts payable and other current liabilities
(16,425)
50,512
Other liabilities
(5,836)
3,718
Net cash provided by operating activities
223,642
206,101
Cash Flows from Investing Activities:
Cash receipts (payments) for interest rate swap
822
(1,137)
Purchase of intellectual property
—
(500)
Purchases of installation and service parts and property and equipment
(70,856)
(56,985)
Cash proceeds from the sale of assets
314
332
Net cash used in investing activities
(69,720)
(58,290)
Cash Flows from Financing Activities:
Borrowings on long-term debt
36,591
—
Repayment of long-term debt
(45,610)
(181,519)
Payment of debt issuance costs
(716)
(459)
Proceeds from the exercise of warrants
—
161,408
Share repurchases and retirement
(199,979)
(100,000)
Proceeds from exercise of stock options
4,288
5,919
Payment of employee tax withholding related to RSUs and PSUs vesting
(6,001)
(3,142)
Net cash used in financing activities
(211,427)
(117,793)
Effect of exchange rate changes on cash and cash equivalents
(1,063)
589
Net (decrease) increase in cash, cash equivalents and restricted cash
(58,568)
30,607
Cash, cash equivalents and restricted cash – beginning of period
139,722
109,115
Cash, cash equivalents and restricted cash – end of period
$
81,154
$
139,722
VERRA MOBILITY CORPORATION
RECONCILIATION OF NET (LOSS) INCOME TO ADJUSTED EBITDA (Unaudited)
Three Months Ended December 31,
For the Year Ended December 31,
($ in thousands)
2024
2023
2024
2023
Net (loss) income
$
(66,656)
$
3,022
$
31,448
$
57,015
Interest expense, net
16,699
20,859
73,902
86,701
Income tax provision (benefit)
10,707
(1,882)
47,660
29,982
Depreciation and amortization
27,543
26,232
108,525
113,067
EBITDA
(11,707)
48,231
261,535
286,765
Transaction and other related expenses (i)
1,245
145
5,369
629
Transformation expenses (ii)
1,892
935
4,444
3,241
Change in fair value of private placement warrants (iii)
—
—
—
24,966
Legal accrual/settlement (iv)
8,250
31,500
8,250
31,500
Tax settlement payment related to a prior acquisition(v)
—
5,652
—
5,652
Goodwill impairment (vi)
97,076
—
97,076
—
Tax receivable agreement liability adjustment (vii)
(257)
(3,077)
(257)
(3,077)
Loss on interest rate swap (viii)
—
2,764
494
817
Loss on extinguishment of debt (ix)
1,117
—
1,745
3,533
Stock-based compensation (x)
4,372
5,130
22,958
17,476
Adjusted EBITDA
$
101,988
$
91,280
$
401,614
$
371,502
Adjusted EBITDA Margin
46
%
43
%
46
%
45
%
(i)
Transaction and other related expenses for the three months and the year ended December 31, 2024
primarily related to deal costs incurred for potential acquisitions and debt modification costs related to the
February and October 2024 refinancings on our First Lien term loan.
(ii)
Transformation expenses consist of severance and other employee separation costs related to exit activities
initiated during each respective period.
(iii)
This is related to adjustments to the private placement warrants liability from the re-measurement to fair
value at the end of the reporting period.
(iv)
This relates to accruals for estimated loss contingencies as well as settlements for any legal proceedings.
(v)
This consists of a tax settlement adjustment related to an acquisition that was completed in 2018.
(vi)
This relates to the impairment of goodwill in our Parking Solutions segment further discussed above
(vii)
This consists of adjustments made to our Tax Receivable Agreement liability due to changes in estimates.
(viii)
Loss on interest rate swap was associated with the derivative instrument re-measured to fair value at the
end of each reporting period offset by the related monthly cash receipts/payments.
(ix)
Loss on extinguishment of debt consists of the write-off of pre-existing original issue discounts and
deferred financing costs associated with the refinancing of our debt for the three months and the year ended
December 31, 2024 and from the early repayments of debt for the year ended December 31, 2023.
(x)
Stock-based compensation represents the non-cash charge related to the issuance of awards under the
Verra Mobility Corporation Amended and Restated 2018 Equity Incentive Plan.
RECONCILIATION OF NET CASH PROVIDED BY OPERATING ACTIVITIES TO FREE CASH
FLOW (Unaudited)
Three Months Ended December 31,
For the Year Ended December 31,
($ in thousands)
2024
2023
2024
2023
Net cash provided by operating activities
$
40,487
$
35,730
$
223,642
$
206,101
Purchases of installation and service parts and property
and equipment
(18,847)
(16,484)
(70,856)
(56,985)
Free Cash Flow (1)
$
21,640
$
19,246
$
152,786
$
149,116
(1)
Free Cash Flow for the year ended December 31, 2024 includes an after-tax legal settlement cost of
approximately $22.1 million. The annual estimated effective tax rate to calculate the income tax effect on the
legal settlement adjustment is 30.0%.
RECONCILIATION OF NET (LOSS) INCOME TO ADJUSTED NET INCOME AND CALCULATION
OF ADJUSTED EPS (Unaudited)
Three Months Ended December 31,
For the Year Ended December 31,
(In thousands, except per share data)
2024
2023
2024
2023
Net (loss) income
$
(66,656)
$
3,022
$
31,448
$
57,015
Amortization of intangibles
16,743
16,721
67,003
77,644
Transaction and other related expenses
1,245
145
5,369
629
Transformation expenses
1,892
935
4,444
3,241
Change in fair value of private placement warrants
—
—
—
24,966
Legal accrual/settlement
8,250
31,500
8,250
31,500
Goodwill impairment
97,076
—
97,076
—
Tax settlement payment related to a prior acquisition
—
5,652
—
5,652
Tax receivable agreement liability adjustment
(257)
(3,077)
(257)
(3,077)
Tax receivable agreement imputed interest
—
(3,641)
—
(3,641)
Loss on extinguishment of debt
1,117
—
1,745
3,533
Change in fair value of interest rate swap
—
3,041
1,316
(320)
Stock-based compensation
4,372
5,130
22,958
17,476
Total adjustments before income tax effect
130,438
56,406
207,904
157,603
Income tax effect on adjustments
(9,751)
(19,568)
(32,802)
(42,105)
Total adjustments after income tax effect
120,687
36,838
175,102
115,498
Adjusted Net Income
$
54,031
$
39,860
$
206,550
$
172,513
Adjusted EPS
$
0.33
$
0.24
$
1.23
$
1.08
Diluted weighted average shares outstanding (1)
165,927
168,585
167,717
160,017
Annual estimated effective income tax rate (2)
30
%
31
%
30
%
31
%
(1)
The diluted weighted average shares outstanding used above includes the dilutive effect of common
stock equivalents outstanding for the three months ended December 31, 2024. This differs from the
weighted average shares outstanding used for net loss per share on our condensed consolidated statement
of operations which have an anti-dilutive effect for the three months ended December 31, 2024.
(2)
The annual estimated effective tax rate used above excludes discrete items as they do not impact taxable
income. This rate differs from the period-to-date effective tax rate used on our condensed consolidated
statements of operations which includes the discrete items.
RECONCILIATION OF TOTAL LONG-TERM DEBT TO NET DEBT AND NET LEVERAGE (Unaudited)
($ in thousands)
December 31,
2024
December 31,
2023
Total long-term debt, net of current portion
$
1,034,211
$
1,029,113
Current portion of long-term debt
—
9,019
Total long-term debt
1,034,211
1,038,132
Original issue discounts
2,322
3,646
Unamortized deferred financing costs
9,035
12,809
Total long-term debt, excluding original issue discounts and unamortized
deferred financing costs
1,045,568
1,054,587
Cash and cash equivalents
(77,560)
(136,309)
Net Debt
$
968,008
$
918,278
Net Leverage
2.4x
2.5x
Trailing twelve months adjusted EBITDA
401,614
371,502
Investor Relations Contact
Mark Zindler
mark.zindler@verramobility.com
View original content to download multimedia:https://www.prnewswire.com/news-releases/verra-mobility-announces-fourth-quarter-and-full-year-2024-financial-results-302387610.html
SOURCE Verra Mobility

You may like
Technology
FF EAI Robotics Ecosystem Inc. Announces Details for Its Listing Ceremony and Nasdaq Investor Day, Taking Place on Monday, Oct. 26, at Nasdaq’s MarketSite in NYC
Published
51 minutes agoon
October 21, 2026By
FF EAI Robotics Ecosystem Inc. (NASDAQ: FFR) will hold its official listing ceremony to mark the Company’s name and ticker change, and first Investor Day at the Nasdaq Tower on Monday, Oct. 26. Subject to completion of the transaction, FFR management will provide 2026 full year guidance, share details on FFR’s future strategy and business plan.A video recap of the event will be available at 4:30 p.m. ET on Oct. 26 at www.ff.com
LOS ANGELES, Oct. 20, 2026 /PRNewswire/ — FF EAI Robotics Ecosystem Inc. (NASDAQ: FFR) (“FFR” or the “Company”), a U.S.-based Embodied AI (EAI) robotics company, today announced details for its Nasdaq listing ceremony and first Investor Day, to be held on Oct. 26 at the Nasdaq Tower in NYC. Subject to completion of the transaction, FFR management will provide 2026 full year guidance, share further details on FFR’s future strategy and business plans at this event and will be available to speak with attending investors onsite. A video recap of the event will be available beginning at 4:30 p.m. ET at www.ff.com.
FFR and FFAI recently signed definitive agreements for FFR to acquire FFAI’s robotics assets and business in an all-stock transaction at an approximate $200 million valuation. FFR will issue shares at $2.246 per share, representing an approximately 50% premium to FFR’s closing price on the date the agreements were signed. Upon closing, FFR will become the No. 1 U.S.-listed pure-play “Four-Core Full-Stack AI” humanoid and bionic EAI robotics ecosystem company.
Note: Event materials will be available on the FF IR website at https://investors.ff.com/events-and-presentations
About FF EAI Robotics Ecosystem Inc.
FF EAI Robotics Ecosystem Inc. (NASDAQ: FFR) (renamed from AIxCrypto Holdings, Inc. and AIXC, effective September 30, 2026) is a U.S.-based Embodied AI (EAI) robotics company that is in the process of acquiring the FF EAI Robotics business. Upon completion of the acquisition, the Company will focus on the research and development, manufacturing, commercialization, and deployment of intelligent robotic technologies, products, and industry solutions.
The Company is committed to building a “Four-Core Full-Stack” AI ecosystem covering the full lifecycle of robotics, consisting of EAI Brain & Developer Platform, EAI Devices, Industry Productivity Solutions, and EAI Data Factory. Guided by the technology and product philosophy of “One Brain, Multi-forms, Multi-capabilities,” the Company aims to empower humanoid, biomimetic, and other robotic form factors through a unified EAI Brain, while continuously expanding their multi-task and multi-scenario capabilities. The ecosystem is designed to support the full robotics lifecycle, including R&D, deployment, data collection and training, operations, and commercial applications.
The FF EAI Robotics business has already achieved commercial deliveries of humanoid and biomimetic robotic products. Through its multi-form-factor robotic products, EAI technology platform, closed-loop data capabilities, and industry solutions, the business continues to advance the scaled adoption of robotics across real-world applications. The Company also operates RoboShare, a robot-sharing and services platform designed to connect robotic assets, service capabilities, customer demand, and ecosystem partners, further strengthening its robotics commercialization and service ecosystem.
For more information, visit www.ff.com.
ABOUT FARADAY FUTURE
Founded in 2014, Faraday Future (FF) is a U.S.-based Physical AI ecosystem company dedicated to reshaping the future of robotics and mobility solutions through AI innovation and technologies. FF focuses on two major product strategies within the Embodied AI (EAI) robotics business: EAI humanoid and bionic robots, and EAI automotive-focused robots. By building a “Four-Core Full-Stack AI” ecosystem of EAI Brain and Developer Platform, EAI Devices, Industry Productivity Solutions and EAI Data Factory, FF aims to create an evolutionary flywheel: scaled device delivery, data collection and training, continuous evolution of the EAI Brain, stronger product capability, and even larger-scale delivery and deployment. Through this flywheel, FF seeks to maximize its commercial value and lead to the advancement of Physical AI. For more information, please visit Faraday Future’s official website: https://www.ff.com/
FFR Forward-Looking Statements
This communication, including any presentation, press release, investor materials or other document of which it forms a part (this “Communication”), contains “forward-looking statements” within the meaning of the “safe harbor” provisions of the Private Securities Litigation Reform Act of 1995, as amended, and other securities laws, regarding FF EAI Robotics Ecosystem Inc. (“FFR,” the “Company,” “us,” “our,” or “we”) and our industry. All statements, whether written or oral, other than statements of historical fact, including any financial projections and any statements regarding future events, our strategy, our transition to robotics operations, our plans for RoboShare, our digital asset disposition plans, the proposed acquisition of the FF EAI Robotics business, the projections referenced in this communication, our name and ticker change, any related financing, and the anticipated benefits and timing of the foregoing, our objectives, expectations, or anticipated actions or results, are forward-looking statements. You can often identify forward-looking statements by words such as “may,” “might,” “will,” “shall,” “should,” “expects,” “plans,” “anticipates,” “could,” “intends,” “targets,” “projects,” “contemplates,” “believes,” “estimates,” “predicts,” “potential,” “goal,” “objective,” “seeks,” “likely,” or “continue,” or the negative of these terms or other similar expressions; the absence of these words does not mean a statement is not forward-looking. These statements reflect our current expectations and projections about future events as of the date of this Communication and are necessarily based on estimates and assumptions that, while considered reasonable by management, are inherently uncertain. FFR can give no assurance that such forward-looking statements or financial projections will prove to be correct.
Actual results may differ materially from those expressed or implied by these forward-looking statements as a result of numerous risks and uncertainties, both general and specific, including, but not limited to:
The proposed acquisition transaction and PIPE. The definitive agreements may be terminated in accordance with their terms, and the proposed transactions may not be completed on the terms described or at all; the conditions to closing, including the completion of FFAI’s internal restructuring of the robotics business, the execution of key employee agreements and other customary conditions, and the parties’ ability to satisfy them; the risk that the stockholder approval required under Nasdaq listing rules for the conversion of the preferred stock issued as consideration is not obtained or is delayed, and the effect of the conversion restrictions and the information statement process on the timing of conversion; the timing of the transaction and the costs of pursuing it; the issuance of a substantial number of shares as consideration and the resulting dilution to existing stockholders; the fact that the counterparty is our controlling stockholder, that it will hold a substantial majority of our outstanding shares following closing, that certain members of management serve both companies, and the conflicts of interest inherent in the transaction; the risk that the agreed valuations do not reflect the market value of our shares or of the acquired business; our dependence on the counterparty for transition, supply and support following any closing; the scope and enforceability of the non-competition and governance arrangements; the consequences of the transaction under Nasdaq listing rules, including the possibility that Nasdaq determines that the transaction requires us to satisfy initial listing requirements in connection with a business combination, change of control or change in the nature of our business; the risk that the PIPE financing, on which the transaction is not conditioned, is not completed on the anticipated terms or at all; the risk of litigation relating to the transaction; our ability to integrate and operate the acquired business; and the risk that the acquired business performs differently than anticipated.
Projections. The projections referenced in this communication were prepared by FFAI management for the FF EAI Robotics business on a standalone basis and do not reflect our existing business, transaction-related expenses or the combined company. We have not independently verified them or adopted them as guidance. They were not prepared with a view toward public disclosure or toward compliance with the published guidelines of the Securities and Exchange Commission or the American Institute of Certified Public Accountants regarding prospective financial information, and no independent registered public accounting firm has examined, compiled or performed any procedures with respect to them, and none expresses an opinion or any other form of assurance with respect to them. The projections reflect estimates and assumptions that are inherently uncertain and subject to change, including through due diligence and the review of our special committee and its financial advisor. Actual results are likely to differ, and may differ materially.
Liquidity, capital and going concern. Our limited cash and liquidity position and our history of operating losses and negative operating cash flow; substantial doubt regarding our ability to continue as a going concern, as described in our periodic reports; our need to obtain additional financing on acceptable terms or at all, and the substantial dilution to existing stockholders that additional financing may cause, including any financing completed in connection with the proposed transaction, which may not be completed or may be on less favorable terms than anticipated; our ability to fund operations pending and following the disposition of our digital asset positions; and our ability to satisfy the continued listing requirements of The Nasdaq Stock Market, including stockholders’ equity, minimum bid price and other applicable standards.
Our strategic transition and the disposition of digital assets. Risks associated with a fundamental shift in our business strategy and the redeployment of resources from a digital asset treasury strategy to robotics operations; our ability to execute the disposition of our digital asset positions in an orderly manner and on acceptable terms; the risk that amounts realized on disposition are materially less than carrying value as a result of price volatility, market depth, execution timing, custody or transfer constraints, or other limitations; tax, accounting and regulatory consequences of the dispositions; the continued volatility and regulatory uncertainty associated with digital assets and cryptocurrencies during the wind-down period; the concentration of a substantial portion of our assets in a single equity investment, including an investment in a related party, and the illiquidity, valuation uncertainty, holding-period and transfer restrictions associated with that investment; and risks arising from our relationships and agreements with related parties and significant stockholders.
Our robotics operations business. Our limited operating history in robotics operations and commercialization and the absence of a meaningful revenue history; the early stage of RoboShare and the risk that customer demand, repeat demand, pricing, utilization or unit economics do not develop as anticipated; our dependence on a small number of customers, on a single initial geographic market, and on individual events or engagements, and the risk that the loss of, or a change in the terms of, any such relationship has a disproportionate effect; our dependence on third-party robot owners, operators, suppliers, original equipment manufacturers and local partners, and on their willingness to make robots available on our platform; risks relating to the availability, cost, quality, maintenance, transport, insurance and technological obsolescence of robots and related equipment, and to supply chains, tariffs and trade measures affecting them; and our ability to expand into additional markets and to attract and retain participants on both sides of our marketplace.
Operations, safety and liability. Risks of property damage, personal injury or death arising from the operation of humanoid robots, quadrupeds and other autonomous or semi-autonomous machines in proximity to performers, employees, guests and the public, including at live events and in uncontrolled environments; product liability, premises liability, negligence and related claims and the adequacy, scope, availability and cost of our insurance coverage and of contractual indemnities from customers, owners and suppliers; the allocation of responsibility among us, robot owners, venues, event producers and customers; permitting, licensing, occupational safety and event-specific regulatory requirements; and the reputational consequences of any safety incident.
Technology, data and intellectual property. Systems, network, telecommunications or service disruptions, failures, defects or cyber-attacks; the performance, reliability and autonomy limitations of robotic systems and of the software, models and networks that support them; our collection, use, storage, transmission and protection of personal information, including images and any biometric or biometric-adjacent data captured in the course of robot deployments, and evolving privacy, biometric and artificial intelligence laws and regulations across the jurisdictions in which we operate or intend to operate; our ability to obtain, maintain, protect and enforce our intellectual property rights and to defend against third-party claims of infringement or misappropriation; and our reliance on third-party technology, platforms and licenses.
Legal, regulatory and general. The regulated industries and jurisdictions in which we operate; current or future laws or regulations and new interpretations of existing laws or regulations, including those applicable to digital assets, robotics, autonomous systems, consumer protection, advertising and endorsements; the risk that our marketplace arrangements, or the manner in which they are described, are characterized differently than we intend by regulators or courts; the failure of counterparties to perform their contractual obligations; litigation, regulatory inquiries, investigations and enforcement actions, and their costs and outcomes; business, economic, market and capital-market conditions; competition in our industry; changes in market demand for, and the pricing of, our products and services; our ability to define, design and release new products and services in a timely manner that meet customer needs; our ability to attract, retain and motivate qualified personnel, including key management; our ability to manage our growth and our transition; and our ability to maintain effective internal control over financial reporting and disclosure controls and procedures.
This list of factors is not exhaustive. Additional risks and uncertainties are described more fully in our filings with the U.S. Securities and Exchange Commission (the “SEC”), including our Annual Report on Form 10-K for the year ended December 31, 2025, our Quarterly Reports on Form 10-Q, and our subsequent filings, which are available on the SEC’s website at www.sec.gov. Investors are urged to review the liquidity, capital resources and going concern disclosures contained in those reports.
The forward-looking statements in this Communication speak only as of the date hereof. Except as required by law, neither FFR nor any other person undertakes any obligation to update or revise any forward-looking statement or financial projection set out herein, whether as a result of new information, future events or otherwise. This Communication is provided for informational purposes only, does not constitute an offer to sell or the solicitation of an offer to buy any security, and does not constitute investment, tax or legal advice or any investment recommendation, and does not take into account the investment objectives or financial situation of any person. FFR reserves the right to amend or replace the information contained herein, in whole or in part, at any time, and undertakes no obligation to notify any recipient thereof. Readers are cautioned not to place undue reliance on these forward-looking statements. This caution is made under, and these forward-looking statements are intended to be covered by, the safe-harbor provisions of the Private Securities Litigation Reform Act of 1995.
FFAI FORWARD LOOKING STATEMENTS
Important factors that may affect actual results or outcomes include, among others: the Company’s ability to continue as a going concern and improve its liquidity and financial position; the Company’s ability to pay its outstanding obligations, which it currently lacks; the availability of sufficient share capital to meet its current obligations and execute on its strategy; the willingness of convertible debt investors to fund the Company; demand for the Company’s robotics products; competition in the robotics industry, which includes companies with far superior experience, funding and name recognition; the ability of the Company to build an EAI education ecosystem that serves both the B2C consumer market and the B2B institutional education market; the acceptance by teachers and students of the Company’s robotics products in the education market; the ability of the Company to expand into additional markets for its robotics products; the Company’s reliance on a single OEM for most of its robotics products; the Company’s reliance on Chinese OEMs for all of its robotics products; the possibility of the federal government banning imports of Chinese robotics products; the Company’s ability to get the planned robotics products to comply with all applicable U.S. rules and regulations; the ability of the robotics OEM to timely supply robotics to the Company; tariff uncertainty for imported products, particularly from China; the ability of the Company to close its transaction with FF EAI Robotics Ecosystem Inc. (FFR) for the sale of its robotics business; demand from automobile dealers for robotics products; the Company’s ability to homologate FX vehicles for sale; the Company’s ability to secure the necessary funding to execute on the FX strategy, which is substantial; the Company’s ability to secure an occupancy certificate covering all of its Hanford facility; the Company’s ability to remediate its material weaknesses in internal control over financial reporting and the risks related to the restatement of previously issued consolidated financial statements; the Company’s limited operating history and the significant barriers to growth it faces; the Company’s history of substantial losses and expectation of continued losses; the success of the Company’s payroll expense reduction plan; the Company’s ability to execute on its plans to develop and market its vehicles and the timing of these development programs; the Company’s ability to execute on its plans to enter the robotaxi and cybercab industries; the Company’s estimates of the size of the markets for its vehicles and cost to bring those vehicles to market; the rate and degree of market acceptance of the Company’s vehicles; the Company’s ability to cover future warranty claims; the success of other competing manufacturers; the performance and security of the Company’s vehicles; current and potential litigation involving the Company; the Company’s ability to receive funds from, satisfy the conditions precedent of and close on the various financings described elsewhere by the Company; the result of future financing efforts, the failure of any of which could result in the Company seeking protection under the Bankruptcy Code; the Company’s indebtedness; the Company’s ability to use its “at-the-market” program; insurance coverage; general economic and market conditions impacting demand for the Company’s products; potential negative impacts of a reverse stock split; potential cost, headcount and salary reduction actions may not be sufficient or may not achieve their expected results; circumstances outside of the Company’s control, such as natural disasters, climate change, health epidemics and pandemics, terrorist attacks, and civil unrest; risks related to the Company’s operations in China; the success of the Company’s remedial measures taken in response to the Special Committee findings; the Company’s dependence on its suppliers and contract manufacturer; the Company’s ability to develop and protect its technologies; the Company’s ability to protect against cybersecurity risks; and the ability of the Company to attract and retain employees, any adverse developments in existing legal proceedings or the initiation of new legal proceedings; the volatility of the Company’s stock price; the ability of the Company to maintain its stock price above $1.00; and the ability of the Company to maintain compliance with Nasdaq regulations for continued listing. You should carefully consider the foregoing factors and the other risks and uncertainties described in the “Risk Factors” section of the Company’s Form 10-Q for the quarter ended June 30, 2026, filed with the SEC on August 13, 2026; the quarter ended March 31, 2026, filed with the SEC on May 14, 2026; and Form 10-K filed with the SEC on March 31, 2026, and other documents filed by the Company from time to time with the SEC.
View original content to download multimedia:https://www.prnewswire.com/news-releases/ff-eai-robotics-ecosystem-inc-announces-details-for-its-listing-ceremony-and-nasdaq-investor-day-taking-place-on-monday-oct-26-at-nasdaqs-marketsite-in-nyc-302914833.html
SOURCE FF EAI Robotics Ecosystem Inc.
Technology
Lovense Launches Glint, a Touch-Responsive Butt Plug That Syncs Anal Stimulation with a Partner’s Thrust During Intercourse
Published
51 minutes agoon
October 21, 2026By
For vibrator-loving couples, Glint offers something genuinely new: vibration driven by a partner’s touch.
SINGAPORE, Oct. 20, 2026 /PRNewswire/ — In the middle of sex, reaching for a phone to adjust a partner’s toy can interrupt the very connection the toy is meant to create.
Lovense today announced Glint, a touch-responsive butt plug for couples, designed to enhance intercourse by synchronizing anal stimulation with a partner’s thrust for a more intense, connected dual penetration experience. Its external base responds to a partner’s thrust as well as to touch, translating that contact into responsive anal stimulation in real time.
Glint allows couples to shape the experience through the movement and touch they are already sharing—not through a phone screen. Glint is not simply removing the phone from the experience. It changes what controls the experience: physical touch, contact and movement become the real-time input.
The numbers behind the pause
In a nationally representative U.S. study published by researchers at Indiana University[1], 43.8% of heterosexual men reported having used a vibrator. Among male vibrator users, approximately 94% had used one during partnered sexual activity and 82% during intercourse. The research suggests that vibrators are already part of partnered sex. The next question is not whether couples use them, but how physical interaction can become part of the control.
Grand View Research projects the global sextech market to reach USD 107.85 billion by 2030[2,3], growing at 16.77% annually—nearly twice the projected growth rate of the sex toys market, which is expected to reach USD 62.7 billion at a CAGR of 8.69%. Many of these devices now connect to apps and to other devices.
What makes Glint different
Glint is worn anally. The base stays outside the body and carries a touch sensor that reads how much skin is on it, at what angle and for how long, then moves the vibration across five intensity levels. A light touch can produce a lighter response, while broader or firmer contact can produce a stronger response, depending on the user’s sensitivity setting.
Users set their sensitivity and choose from three response modes in the Lovense Remote app:
Pulse, for rhythmic touch-based feedback;Sustain, for continuous vibration while contact continues;Crescendo, for vibration that builds as contact is maintained.
Glint is 0.84 inches (21.5 mm) across and weighs 55 grams. The small size keeps it comfortable to wear and approachable for people new to anal play. Its compact anal form factor is designed to stay out of the way during intercourse. It runs up to 7,500 vibrations per minute, lasts 95 to 178 minutes on a charge depending on level, charges in about an hour and is IPX7 waterproof. Through Toy Sync, its base can also control other Lovense devices.
Three ways couples will use it
Thrust-synced intercourse. During intercourse, each thrust against the external base is synchronized with anal stimulation in real time. The stimulation follows the couple’s rhythm rather than a preset pattern. With Glint in place, dual penetration feels fuller and more intense.
Touch-led foreplay. One partner wears Glint while the other explores the external base with a fingertip or hand. The wearer feels the response change as contact changes. The wearer can choose whether Touch Response is active and set the sensitivity before play begins.
Two toys, one movement. One partner wears Glint while the other wears a compatible Lovense device, such as Edge 2, Lush 4 or Gush 2 Motion. When the toys are paired through Toy Sync, physical contact with Glint can trigger responsive feedback in both devices, allowing the couple’s movement to shape the shared experience in real time. For example, one partner may wear Glint while the other wears Edge 2, Lovense’s prostate massager, allowing both partners to feel stimulation shaped by the same thrust. Either partner can wear Glint. The wearer remains in control, while the couple creates the rhythm together.
For couples in different locations, Lovense Remote continues to provide long-distance control.
For in-person use, Glint includes Touch Records, which is optional and turned off by default. If enabled, Touch Records lets users review selected interaction data after a session.
The oldest interface
“The simplest thing two people do during sex is touch each other,” said Dan Liu, CEO of Lovense. “With Glint, we wanted to explore what happens when touch becomes a new control layer between two people—so the couple can stay inside the interaction rather than reaching for a screen.”
Since 2010, Lovense has built an ecosystem that turns signals from apps, games and live streams into feedback on connected devices. Glint adds physical touch and movement as another way for signals to reach the body. The app is still there for setup and for partners in different cities; during sex, the couple can leave it on the nightstand.
Availability
Glint launches worldwide on October 20, 2026 and will be available at lovense.com.
About Lovense
Lovense is a connected intimacy technology company founded in 2010. Its ecosystem combines smart intimate devices, the Lovense Remote app, creator and live-streaming tools, platform integrations and developer APIs to help individuals and couples create more connected experiences across distance, content and everyday intimacy.
Reference:
1.Reece M, Herbenick D, et al. Vibrator Use Among Heterosexual Men Varies by Partnership Status. Journal of Sex & Marital Therapy, 2010, 36(5): 389–407.
https://doi.org/10.1080/0092623X.2010.510774
2.Grand View Research, SexTech Market Size To Reach $107.85 Billion By 2030. https://www.grandviewresearch.com/press-release/global-sextech-market
3.Grand View Research, Sex Toys Market Size To Reach $62.7 Billion By 2030. https://www.grandviewresearch.com/press-release/global-sex-toys-market
View original content to download multimedia:https://www.prnewswire.com/news-releases/lovense-launches-glint-a-touch-responsive-butt-plug-that-syncs-anal-stimulation-with-a-partners-thrust-during-intercourse-302914858.html
SOURCE Lovense
Technology
Kontron Launches Two New KBox F-Series Industrial Computers To Bring Greater Flexibility and Scalability to Industrial Edge Computing
Published
2 hours agoon
October 21, 2026By
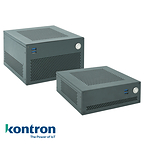
TAIPEI, Oct. 21, 2026 /PRNewswire/ — Kontron, a leading global provider of IoT/Embedded Computing Technology (ECT), expands its KBox F-Series with the KBox F-203-RPS and KBox F-204-RPS, two compact industrial computers designed to address diverse requirements in intelligent Industry 4.0, edge computing and industrial IoT applications.
Both systems are powered by 12th, 13th or 14th Gen Intel® Core™ i9/i7/i5/i3 S-Series socket-type processors with a TDP of up to 65 W and support up to 96 GB DDR5 memory, providing a scalable computing foundation for demanding industrial applications requiring flexible performance configuration and long-term deployment.
The KBox F-203-RPS offers two LAN configurations with either two or four GbE ports, allowing customers to select the connectivity level that best fits their applications. The dual-LAN configuration provides an efficient solution for general industrial computing, equipment control and edge applications, while the four-LAN configuration offers additional network connectivity for applications involving multiple devices or network segments, such as machine vision, industrial automation and IoT gateways.
For applications requiring greater system expandability, the KBox F-204-RPS provides one PCIe x16 or two PCIe x8 expansion slots, offering the flexibility to integrate graphics, networking, AI acceleration or other add-on cards according to specific application requirements. With support for up to four 2.5-inch SATA HDDs/SSDs, it also provides extensive storage scalability for data-intensive workloads. These capabilities make the KBox F-204-RPS particularly suitable for industrial edge computing, machine vision, video processing and applications requiring additional functionality or large local data storage.
Together, the KBox F-203-RPS and KBox F-204-RPS enable customers to select the configuration that best matches their requirements, from a slimmer, network-focused industrial computer to a highly expandable edge computing platform.
To learn more about KBox F-203-RPS and KBox F-204-RPS, refer to https://www.kontron.com/en/products/kbox-f-203-rps/p301099 and https://www.kontron.com/en/products/kbox-f-204-rps/p311867.
About Kontron
At Kontron, we champion IoT and Industry 4.0, by creating secure, state-of-the-art solutions that span hardware, software and services. Our approach speeds market entry, reduces the cost of ownership, and offers longevity, ensuring our role as your trusted partner in the integration of smart technologies. For more information, please visit www.kontron.com, dial +886-2-2799-2789 or email SalesAsia@kontron.com.
View original content to download multimedia:https://www.prnewswire.com/apac/news-releases/kontron-launches-two-new-kbox-f-series-industrial-computers-to-bring-greater-flexibility-and-scalability-to-industrial-edge-computing-302909761.html
SOURCE Kontron


FF EAI Robotics Ecosystem Inc. Announces Details for Its Listing Ceremony and Nasdaq Investor Day, Taking Place on Monday, Oct. 26, at Nasdaq’s MarketSite in NYC

Lovense Launches Glint, a Touch-Responsive Butt Plug That Syncs Anal Stimulation with a Partner’s Thrust During Intercourse

Kontron Launches Two New KBox F-Series Industrial Computers To Bring Greater Flexibility and Scalability to Industrial Edge Computing

Send Rakhi to UK swiftly with UK Gifts Portal

Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

Nullmax and Renesas Forge Strategic Partnership to Deliver Competitive ADAS Solutions for the Global Market

Why You Should Build on #NEAR – Co-founder Illia Polosukhin at CV Labs
Whiteboard Series with NEAR | Ep: 45 Joel Thorstensson from ceramic.network

NEAR End of Year Town Hall 2021: The Open Web World, MetaBUILD 2 Hackathon and 2021 recap
Trending
-

 Coin Market5 days ago
OpenAI model helped itself to testnet crypto, then kept quiet about it
-
 Technology5 days ago
FF EAI Robotics (FFR) and FF Jointly Launch FF Nova, First Embodied AI Humanoid Robot Priced Below $2,500 in U.S., FF Nova Mini, Physical AI Spark Program Curriculum, Nova Reinforcement Learning Developer Program and Developer Community Recruitment
-
 Technology4 days ago
JinkoSolar Unveils Tiger Neo 5.0 All-Black Residential Solar Module with 25.52% Efficiency
-
 Technology4 days ago
Highland and Bath Counties, Virginia Go Live on a Shared Caliber Hosted CAD Environment
-
 Coin Market4 days ago
Bitcoin price steadies around $82K after Fed’s Warsh avoids rate-hike hints
-
 Technology5 days ago
Frost & Sullivan: Netradyne Receives the 2026 Global Commercial Vehicle Video Telematics Product Leadership Recognition for Excellence in AI-Driven Fleet Safety and Operational Intelligence
-
 Near Videos4 days ago
What if you could build a skyscraper with one prompt?
-
Technology5 days ago
/R E P E A T — Media Advisory – Minister Hodgson to deliver remarks and participate in fireside chat/